

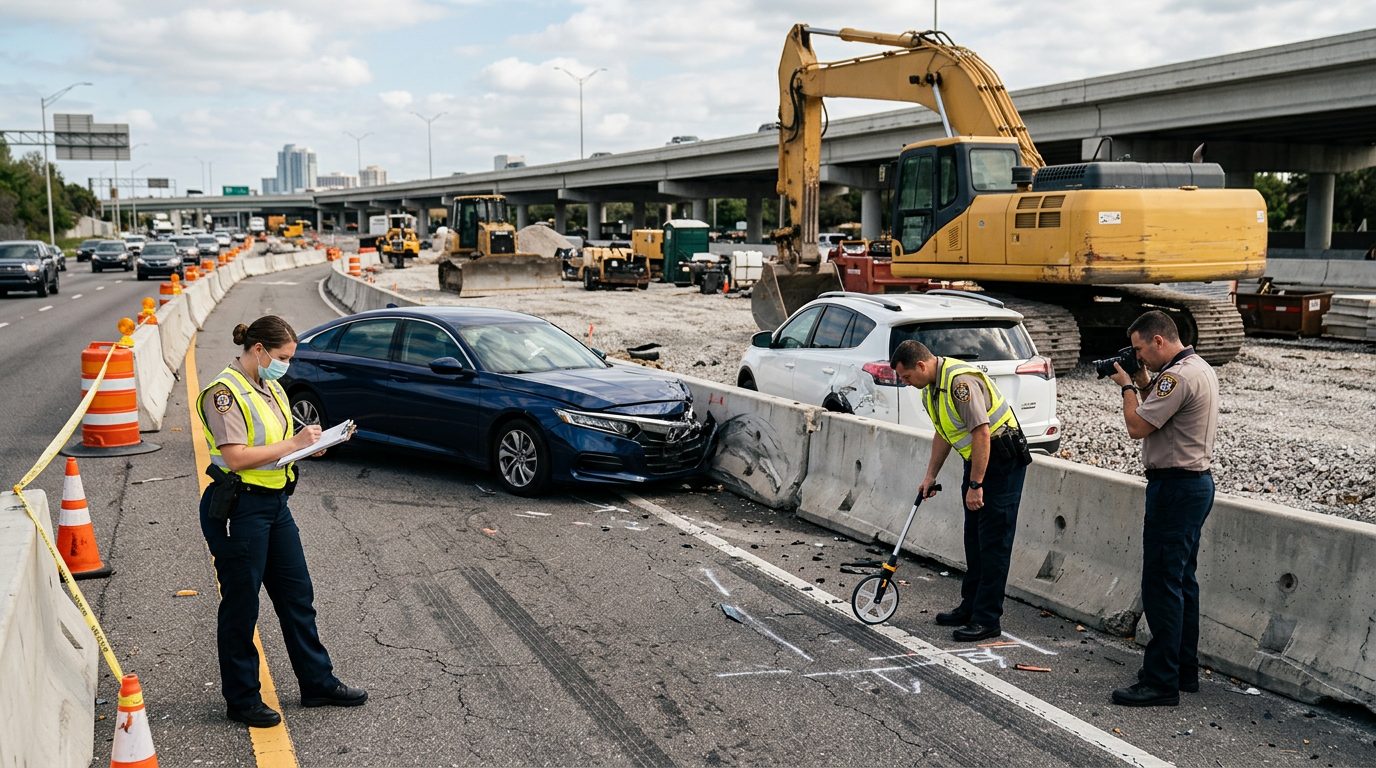
Car Accidents Orlando
Understanding Florida's No-Fault System After a Car Accident
If you've been injured in a car accident in Orlando, Florida's no-fault insurance rules affect your recovery options. Learn how the system works and what steps to take next.
By CHG Lawyers · Published September 25, 2026
Car Accidents in Orlando: Florida’s No-Fault System, Your Rights, and Recovery
If you’ve been in a car accident in Orlando, the first hours matter. So does understanding how Florida’s insurance system works. The I-4 corridor sees constant traffic. Whether it’s a fender-bender on US-17/92 or a serious collision, what you do right away shapes your claim.
This guide explains Florida’s no-fault system in plain language. It walks you through critical steps after a car accident in Orlando. It also tells you when legal guidance becomes essential.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Immediate Actions After an Orlando Car Accident
Safety first. If anyone is injured, call 911 immediately. If vehicles can be moved safely and no one is hurt, move them out of traffic. This prevents secondary crashes.
Exchange information with the other driver: – Full name, phone number, and address – Driver’s license number – Vehicle registration and VIN – Insurance company name and policy number
Document the scene: – Photograph vehicle damage from multiple angles – Capture road conditions, traffic signals, lane markings, and weather – Note the time of day and lighting conditions – Take photos of your injuries, even if minor
Get witness information. Ask anyone who saw the crash for their name, phone number, and what they saw. Witnesses often disappear. Their contact information is irreplaceable.
Request the police report number. If the Florida Highway Patrol or Orlando Police Department responds, get the officer’s name, badge number, and accident report number. This report becomes the official record of the crash.
Drivers in some minor crashes may be able to self-report the crash through the Orlando Police Department.
How Florida’s No-Fault Insurance System Works
Florida is a “no-fault” state. This system confuses most accident victims because it works differently than expected.
Here’s what it means in plain language:
After a crash, your own insurance company pays 80% of reasonable medical expenses and 60% of lost income, up to your PIP policy limit. This happens regardless of who caused the accident. You don’t have to prove the other driver was at fault. Your insurer covers these costs up to your policy limits. This coverage is called “Personal Injury Protection” or PIP coverage.
Example: You’re stopped at a red light on I-4 when another driver rear-ends you. You have $10,000 in PIP coverage. Your medical bills total $8,500. No argument about fault is required.
The catch: No-fault insurance covers only medical expenses and lost wages. It does not cover pain and suffering, permanent disability, loss of quality of life, or future medical costs.
For those damages, you need a separate claim against the at-fault driver. Florida law sets a high bar for this claim.
The 51% Rule: When You Can Sue the Other Driver
Under Florida Statute § 768.81, you can pursue a claim against the other driver only if you are less than 51% responsible for the crash. This is called comparative negligence in Florida.
If you are 51% or more at fault, you generally cannot recover damages from the other driver.
If you are found partially at fault, your recovery is reduced by your percentage of fault.
Example: A driver runs a red light and hits your car. You’re deemed 15% at fault for not seeing the vehicle in time. You can sue the other driver. Any settlement or judgment is reduced by 15%. If you win $100,000, you receive $85,000.
This rule applies to liability claims—the claims you file against the other driver’s insurance. It does not affect your no-fault benefits, which you receive regardless of fault.
Serious Injury Threshold: When No-Fault Insurance Isn’t Enough
Florida law recognizes that some crashes cause permanent, life-altering harm. The state allows you to pursue a claim beyond no-fault insurance if your injury meets the serious injury threshold defined in Florida Statute § 627.737.
You meet this threshold if you have:
- Significant and permanent loss of an important bodily function (such as mobility, speech, or cognitive ability)
Under Florida’s serious injury threshold, you may recover damages for pain, suffering, mental anguish, and inconvenience from bodily injury only if the injury meets the statute’s requirements, such as a significant and permanent loss of an important bodily function (Fla. Stat. § 627.737).
The Financial Reality of Catastrophic Injury
A catastrophic injury isn’t just a medical event. It’s a permanent change to your life and your family’s future.
Consider the lifetime costs of spinal cord injury. Lifetime costs of care for a spinal cord injury can be substantial, and they depend heavily on the level of the injury.
These figures include hospitalization, rehabilitation, medical equipment, home modifications, attendant care, and lost earning capacity.
A 35-year-old earning $60,000 per year who becomes unable to work has lost 30 years of earning capacity. That’s $1.8 million in gross income, before taxes. Add the cost of a wheelchair-accessible vehicle, home modifications, ongoing medical care, and assistive technology. The financial impact is staggering.
Families often face impossible choices: one parent leaves work to provide care. Medical debt accumulates. Savings are depleted. A claim against the at-fault driver exists precisely because the law recognizes that no-fault insurance alone cannot address this reality.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
How to Document Your Claim
Immediately after the crash: – Photograph your injuries (even minor ones) and repeat as they heal – Keep all medical records, test results, and imaging (X-rays, MRIs, CT scans) – Save all receipts for medical treatment, medications, and medical equipment – Document lost wages (pay stubs, employer statements, tax returns) – Keep all communications with insurance companies (emails, letters, recorded calls) – Write down what you remember about the crash while it’s fresh
Ongoing: – Follow all medical treatment recommendations – Keep a journal of your symptoms, pain levels, and how the injury affects your daily life – Note any permanent changes (inability to work, need for assistance, lifestyle changes) – Save receipts for any out-of-pocket expenses related to the crash
This documentation becomes the evidence in your claim. Insurance companies and, if necessary, a jury will rely on it.
The Timeline: No-Fault vs. Liability Claims
No-fault claims typically move quickly. Your insurer pays medical bills and wage loss directly to providers and you. The process usually takes weeks to a few months.
Liability claims for serious injuries take longer. The process typically unfolds as follows:
-
Investigation (weeks to months): Your attorney and the at-fault driver’s insurer gather evidence—police reports, medical records, witness statements, expert opinions.
-
Demand letter (1–3 months): Your attorney sends a detailed claim to the at-fault driver’s insurer. It explains the crash, your injuries, and the damages you’re seeking.
-
Negotiation (1–6 months): The insurer responds with a counteroffer. Back-and-forth negotiation occurs. Many claims settle at this stage.
-
Lawsuit (if necessary, 6 months to 2+ years): If settlement fails, your attorney files a lawsuit. Discovery (exchange of evidence) occurs. Expert witnesses may be retained. The case may be tried before a jury or settled before trial.
Statute of limitations: You have 2 years from the date of the accident to file a lawsuit. Do not wait. Delay weakens your claim. Memories fade, evidence is lost, and witnesses become harder to locate.
When to Reach Out for Legal Guidance
You should consider consulting with a personal injury attorney if:
- Your injuries are serious or permanent
- Medical expenses exceed $10,000
- You’ve lost time from work or cannot return to your job
- The at-fault driver’s insurance company is disputing fault
- You’re unsure whether your injury meets Florida’s serious injury threshold
- The crash involved multiple vehicles, commercial vehicles, or unclear liability
- You’ve been injured by a rideshare driver, commercial truck driver, or on someone else’s property
An attorney can help you understand what you’re truly entitled to. They can navigate negotiations with insurance companies and protect your rights.
Frequently Asked Questions
What should I do immediately after a car accident in Orlando?
Check for injuries and call 911 if anyone is hurt. Move to safety if possible. Exchange information with the other driver. Take photos of the scene and vehicle damage. Get witness contact information. Request the police report number from the responding officer.
How does Florida’s no-fault insurance system work?
Your own insurance (Personal Injury Protection, or PIP) covers your medical bills and lost wages after a crash, regardless of who caused it, up to your policy limits. PIP pays 80% of reasonable medical expenses and 60% of lost income, up to the $10,000 policy limit, if you get initial care within 14 days of the crash; however, medical benefits are limited to $2,500 unless a qualified provider determines that you have an emergency medical condition (Fla. Stat. § 627.736). You don’t have to prove fault to receive these benefits. However, no-fault insurance does not cover pain and suffering or permanent disability.
What is the 51% rule in Florida?
Under Florida’s comparative fault law, you can pursue a claim against the other driver only if you are less than 51% responsible for the crash. If you’re 51% or more at fault, you generally cannot recover from the other driver. If you’re partially at fault, your recovery is reduced by your percentage of fault.
When can I sue the other driver after a car accident?
Florida requires drivers to carry $10,000 in personal injury protection (PIP) and $10,000 in property damage liability; bodily injury liability coverage is not generally required (Fla. Stat. §§ 324.022, 627.736). You have 2 years from the date of the accident to file a lawsuit.
What damages can I recover in a serious injury claim?
You can recover pain and suffering, permanent disability, loss of quality of life, lost earning capacity (past and future), future medical costs, assistive equipment, home modifications, and emotional distress.
How long does a car accident settlement take in Florida?
No-fault claims typically resolve within weeks to a few months. Liability claims for serious injuries can take several months to over a year, depending on complexity, the parties’ positions, and whether a lawsuit is filed.
Are all car accidents public record in Florida?
Yes, police accident reports are generally public records. You can request yours from the Orlando Police Department or the Florida Highway Patrol using the report number and crash date.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
What Comes Next
The financial and emotional reality of catastrophic injury is permanent. You deserve to understand what you’re entitled to and what your options are.
People in your situation reach out regularly to discuss what happened and what comes next. Contact us for a free case evaluation. We’ll listen to your story, explain how Florida’s system works in your case, and tell you what you can do.
What to Do Immediately After a Car Accident
Check for Injuries & Call for Help
Assess yourself and passengers for injuries. Call 911 if anyone is hurt. Move to a safe location if possible and turn on hazard lights.
Document the Scene
Take photos of vehicle damage, the accident scene, road conditions, and traffic signs. Get the police report number from the responding officer.
Exchange Information
Collect the other driver's name, phone number, address, insurance company, policy number, and vehicle details. Get contact information from any witnesses.
Seek Medical Attention
Get evaluated by a doctor even if you feel fine. Some injuries appear hours or days later. Keep all medical records and receipts.
How Florida's No-Fault System Works
Personal Injury Protection (PIP) Coverage
Florida law requires all drivers to carry PIP insurance. This coverage pays for your medical bills and lost wages up to your policy limit, regardless of who caused the accident.
Filing a Claim
Report the accident to your insurance company promptly. Provide the police report number, medical records, and documentation of expenses. Your insurer will review and process your claim.
When You Can Sue the Other Driver
Florida allows you to pursue a claim against the at-fault driver's insurance if your injuries are serious or your medical expenses exceed your PIP limit. Catastrophic injuries—permanent disability, disfigurement, or significant scarring—may qualify.
Catastrophic Injury Claims
If you've suffered a spinal cord injury, paralysis, traumatic brain injury, amputation, or severe burn, you may have grounds for a larger claim beyond no-fault benefits. These cases require thorough documentation and legal guidance.
Important: Time Matters
Insurance companies and at-fault drivers have deadlines for responding to claims. Delaying action can affect your recovery. If your injuries are serious or your claim is denied, contact an attorney promptly to protect your rights.
Common Questions About Orlando Car Accidents
What if I'm partially at fault?
Florida follows comparative negligence rules. You may still recover damages even if you share some responsibility, though your recovery may be reduced by your percentage of fault.
What if the other driver is uninsured?
Your own uninsured motorist (UM) coverage may help cover your medical bills and damages. Your PIP coverage also applies regardless of the other driver's insurance status.
How long do I have to file a claim?
While PIP claims have specific timelines, the deadline to file a lawsuit against an at-fault driver depends on the type of claim. Don't wait—contact an attorney to understand your deadlines.
What if my injuries are permanent?
Permanent injuries—including spinal cord damage, paralysis, traumatic brain injury, or severe scarring—may entitle you to compensation beyond no-fault benefits. An attorney can evaluate your case.
Why Choose CHG Personal Injury Lawyers
Focus on Catastrophic Injury Cases
We focus on serious and catastrophic injuries—spinal cord injuries, paralysis, traumatic brain injuries, amputations, severe burns, and other life-altering harm. We understand the long-term impact these injuries have on your life.
Florida-Based and Serving Florida
Based in Florida, we handle car accident cases throughout the state.
Thorough Case Investigation
We gather police reports, medical records, witness statements, and accident reconstruction data to build a strong case. We work with medical professionals to document the full extent of your injuries.
No Attorney’s Fees Unless There Is a Recovery
We handle cases on a contingency basis. You pay no attorney fees unless we recover compensation for you. We advance costs and work to maximize your recovery.