

Car Accident Claims
Your Pre-Existing Back Injury Doesn't Disqualify Your Claim
Florida law protects you when a car accident makes an old injury worse. Learn how to pursue fair compensation for your aggravated condition.
By CHG Lawyers · Published September 16, 2026
Pre-Existing Back Conditions and Car Accident Claims: What Your Prior Injury Actually Means for Your Payout
The short answer: a pre-existing back condition does not eliminate your car accident claim. If a car accident aggravates, worsens, or reactivates a prior back injury—whether a herniated disc, chronic pain, or old strain—you have a valid legal claim for the new or additional harm caused by the crash. The defendant and their insurance company cannot simply refuse to pay because you had a prior condition.
Many injured people fear that their medical history will disqualify them or drastically reduce their settlement. That fear is understandable—but it’s not how Florida law works.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
The Eggshell Plaintiff Doctrine: Your Legal Protection
Florida courts protect injured people with pre-existing conditions through a legal principle called the eggshell plaintiff doctrine. Here’s what it means in plain language: if you were already vulnerable because of a prior back injury, and a car accident caused new harm or worsened your condition, the at-fault driver is responsible for the full extent of that damage—not just what would have happened to someone without your history.
The doctrine comes from a straightforward principle: a tortfeasor (the person at fault) takes their victim as they find them. The defendant took the risk of hitting you as you actually were—with your actual body and your actual medical history. If that history made you more vulnerable to serious injury, that’s their legal responsibility, not yours.
Florida courts have consistently upheld this rule. The at-fault driver cannot escape liability by arguing, “Well, if this person hadn’t had a prior back injury, the accident wouldn’t have caused so much damage.” That argument fails. The driver caused the collision. They are liable for all injuries that result, even if the injured person was more vulnerable than average.
Your prior condition does not shield the defendant from liability. It does not reduce what they legally owe you.
Pre-Existing vs. New Injury: What the Medical Evidence Must Show
Here’s where medical documentation becomes critical. Insurance adjusters and defense attorneys will distinguish between two things:
- Your baseline condition before the accident (stable, dormant, or even asymptomatic)
- The new or worsened injury caused by the crash
If you had a stable back condition and the accident reactivated it or made it significantly worse, the accident is the legal cause of your current damages. You are entitled to compensation for that aggravation, worsening, or reactivation—not just for a completely new injury.
Real-world examples:
- You had a prior herniated disc that wasn’t causing pain. The car accident causes acute pain, imaging shows new nerve compression, and you need physical therapy. You have a claim for the aggravation.
- You had chronic back pain managed with occasional ibuprofen. After the accident, you need regular physical therapy, prescription pain medication, and specialist visits. You have a claim for the worsening.
- You had a back strain years ago that fully resolved. The accident reactivates it, causing pain and functional loss. You have a claim for the reactivation.
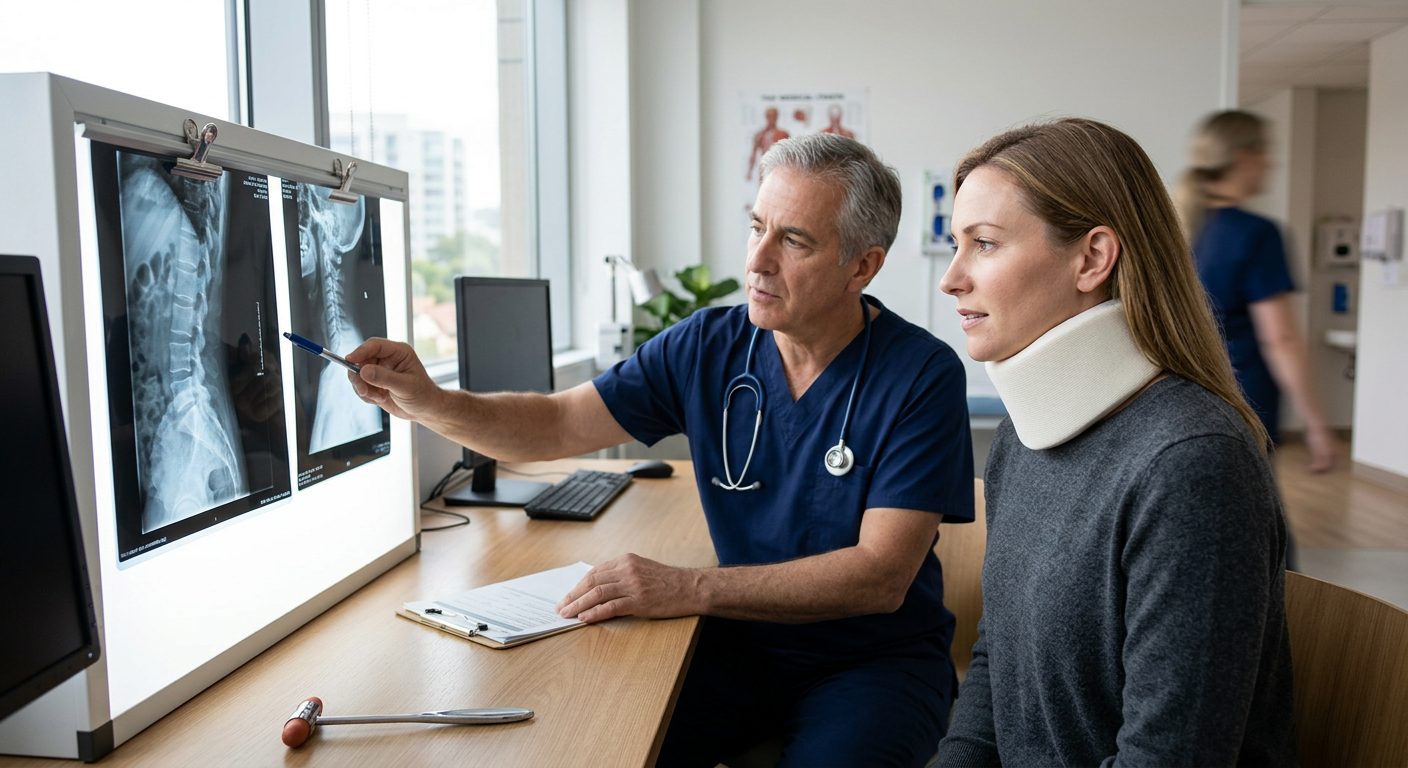
Medical records—imaging (MRI, CT scans, X-rays), doctor’s notes, treatment records before and after the accident—are essential to proving what changed as a result of the crash. Without clear documentation, an adjuster can argue that your current pain is “just” your old condition. With strong medical evidence, you prove causation and protect your full claim value.
Why Insurance Companies Highlight Pre-Existing Conditions
Defense adjusters will bring up your prior back injury as a negotiation tactic—not because it legally eliminates your claim, but because they hope to reduce the settlement offer.
They may argue: “Some or all of your current pain is just your old condition, not the accident. We shouldn’t have to pay for that.”
This is a common lowball strategy. It’s not legally sound under Florida’s eggshell plaintiff doctrine, but it works if you don’t have strong medical evidence to counter it.
A pre-existing condition does make your case slightly more complex because you must prove causation: that the accident caused new harm or worsening, not that your old condition simply flared up on its own. But that burden is not unreasonable. Doctors can review your medical history, compare your baseline to your post-accident condition, and state clearly whether the accident aggravated your back.
Strong medical evidence—doctor’s statements, imaging comparisons, treatment records—defeats the insurance company’s lowball tactic and supports your full claim value.
Settlement Amounts Vary Widely: What Factors Actually Matter
Settlement value for a car accident injury depends on multiple factors, and a pre-existing condition does not automatically lower the payout. Instead, it requires clear medical documentation showing what the accident did to you.
Factors that influence settlement value:
- Type and severity of the injury
- Extent and duration of medical treatment
- Whether the injury is permanent or temporary
- Lost wages and reduced earning capacity
- Impact on your ability to work, exercise, or perform daily activities
- Strength of liability evidence
- Available insurance coverage (the at-fault driver’s policy limit)
- Your percentage of fault (if any)
What do car accident injuries actually settle for? The answer varies widely because every case is different:
- Minor soft-tissue injuries (whiplash, mild strains): typically $5,000–$15,000
- Moderate back injuries with ongoing physical therapy or specialist care: typically $25,000–$100,000
- Severe back injuries with permanent nerve damage, chronic pain, or significant loss of function: typically $100,000–$500,000+
- Catastrophic spinal cord injuries causing paralysis or permanent impairment: typically $500,000–$25 million+
Your specific payout depends on your specific case. A pre-existing back condition that was significantly worsened by an accident—requiring new surgery, permanent medication, or loss of work capacity—may result in a higher settlement because the accident caused substantial, permanent aggravation.
Important: These ranges are based on typical outcomes, not guarantees. Your actual settlement depends on the unique facts of your case, the strength of your medical evidence, and the insurance coverage available.
Medical Evidence You’ll Need to Prove Aggravation
To prove that a car accident aggravated your pre-existing back condition, gather:
- Pre-accident medical records: imaging (X-rays, MRI, CT scans), doctor visits, treatment notes, and documented pain levels showing your baseline condition and whether it was stable or improving
- Post-accident medical records: imaging, exam findings, and doctor’s notes documenting new symptoms, worsening of existing symptoms, or changes in your functional ability
- A doctor’s opinion explicitly linking the accident to the aggravation or worsening of your back condition (this is critical)
- Treatment records showing ongoing care, physical therapy, specialist visits, medication changes, or new interventions after the crash
- Lost income documentation if the injury forced you to miss work, reduce your hours, or change your job
- Evidence of permanent impact: if the accident caused lasting changes to your ability to work, exercise, or perform household tasks
If your pre-existing condition required surgery or long-term treatment after the accident that wouldn’t have been necessary otherwise, that significantly strengthens your claim because it demonstrates the accident caused substantial new harm.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
How Much Should You Settle For?
There is no single “right” number. Settlement value depends on your specific injury, treatment, lost income, and the strength of the liability case.
Do not accept the first offer. Insurance companies typically open low, especially when a pre-existing condition is involved. They’re testing to see if you’ll accept less because you’re worried about your medical history.
Your settlement should cover:
- All medical expenses (past treatment and reasonably anticipated future care)
- Lost wages and reduced earning capacity
- Compensation for pain, suffering, and reduced quality of life
- Any permanent impairment or ongoing disability
If your pre-existing condition was stable or dormant before the accident and the crash caused significant worsening, your settlement must reflect the full impact of that aggravation—not just immediate medical bills.
Common Mistakes to Avoid
Don’t minimize or hide your pre-existing condition. Adjusters will find your medical history anyway. Dishonesty undermines your credibility and can damage your case.
Don’t accept a settlement that only covers immediate medical bills. If your back injury requires ongoing treatment, causes chronic pain, or has permanently changed your ability to work, your settlement must account for that long-term impact.
Don’t negotiate directly with the insurance company without understanding how pre-existing conditions affect your case. The adjuster’s framing may not be legally accurate. They’re motivated to minimize your payout, not to explain your rights fairly.
Don’t assume your claim is worthless because you had a prior back problem. Many successful claims involve pre-existing conditions that were aggravated by an accident. Your medical history does not eliminate your right to compensation.
Insurance Coverage and Policy Limits
The at-fault driver’s insurance policy limit is the maximum the insurance company will pay, regardless of your actual damages.
If your damages exceed the policy limit, you may have a claim against the at-fault driver’s personal assets or against your own underinsured motorist (UIM) coverage—a coverage that protects you when the other driver doesn’t have enough insurance.
A pre-existing condition does not change this entitlement. You are still entitled to the full value of your claim, limited only by available insurance coverage.
Understanding the policy limits early helps set realistic expectations for settlement negotiations and prevents you from accepting an offer that’s far below what your case is actually worth.
Statute of Limitations: When You Must File
In Florida, most personal-injury claims arising on or after March 24, 2023, must be filed within two years of the injury. Claims that arose before that date generally had four years.
Do not wait. Gather your medical records, document your damages, and consult with an attorney as soon as possible after your accident. The sooner you act, the fresher the evidence and the stronger your case.
Comparative Fault in Florida
Florida follows a modified comparative-fault rule: if you are found to be more than 50% at fault for the accident, you generally recover nothing. If you are 50% or less at fault, your damages are reduced by your percentage of fault.
A pre-existing condition does not affect this rule. Your liability for the accident is separate from your medical history. If the other driver was clearly at fault, your prior back injury doesn’t change that.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
Frequently Asked Questions
Does a pre-existing condition reduce my car accident settlement?
Not automatically. Florida law protects you through the eggshell plaintiff doctrine. If the accident aggravated your pre-existing condition, you have a valid claim for that aggravation. Settlement value depends on the injury, treatment, and damages—not on whether a prior condition existed.
Can insurance deny my claim because I had a prior back injury?
No. Insurance companies may try to argue that your current pain is “just” your old condition, but that’s a negotiation tactic, not a legal defense. With strong medical evidence, you prove the accident caused new harm or worsening.
What medical evidence do I need to prove a pre-existing condition was aggravated?
Pre-accident medical records showing your baseline condition, post-accident records showing new or worsened symptoms, and a doctor’s opinion linking the accident to the aggravation. Treatment records and lost-income documentation strengthen your case.
How much of my settlement will I actually receive?
That depends on your specific damages, the strength of your case, and available insurance coverage. An attorney can explain realistic expectations based on your injury, treatment, and the other driver’s policy limits.
What if my damages exceed the at-fault driver’s insurance policy limit?
You may have a claim against their personal assets or against your own underinsured motorist coverage, which protects you when the other driver doesn’t have enough insurance.
Next Steps: Get a Clear Picture of Your Claim
If a car accident aggravated a back condition you already had, you may still have a valid claim—and you deserve to understand what it’s actually worth. Many people in your situation—injured in a car accident and worried that a prior back injury will disqualify them or drastically reduce their payout—benefit from discussing their specific circumstances with an attorney who focuses on car accident injuries before making any decisions about settlement or next steps.
Contact CHG Personal Injury Lawyers for a free case evaluation. We’ll review your medical history, the accident details, the insurance company’s position, and explain what your claim is actually worth based on the facts of your case and the law. You’ll have a clear picture of your options and what to do next.
How We Help You Navigate a Pre-Existing Injury Claim
The Eggshell Plaintiff Doctrine Protects You
Florida law recognizes that accident victims have different vulnerabilities. If a car crash aggravates your pre-existing back condition, you can recover compensation for that aggravation—even if someone without your history would have suffered less harm.
We Separate Pre-Existing From New Injury
Insurance companies will scrutinize your medical history. We document what your back condition was before the accident, what treatment you received, and how the crash made it worse. This clear record protects your claim.
Medical Evidence Tells Your Story
Your doctors' notes, imaging, and testimony establish the link between the accident and your worsening symptoms. We work with your medical team to build a record that shows the crash caused real, measurable harm to your back.
Settlement Value Reflects Your Actual Damages
Compensation is based on your injury, treatment costs, lost wages, and pain and suffering—not on whether a prior condition existed. We calculate what your aggravated condition is truly worth.
Common Questions About Pre-Existing Injuries and Car Accident Payouts
Will the insurance company deny my claim because of my pre-existing back injury?
Not automatically. Insurance companies cannot simply reject your claim because you had a prior condition. However, they will argue that the accident caused minimal new harm. We counter that argument by proving the crash aggravated your existing injury and caused measurable, compensable damage.
How do we prove the accident made my back injury worse?
Medical records are key. We gather your pre-accident treatment history, imaging, and doctor's notes—then compare them to post-accident medical evidence. If your symptoms worsened, your treatment intensified, or your doctors document new or increased pain after the crash, that establishes aggravation.
What if I didn't seek treatment immediately after the accident?
A delay in treatment can complicate your claim, but it doesn't automatically disqualify it. Some people experience delayed pain or don't realize an injury has worsened until days or weeks later. We explain the gap and use medical evidence to show the connection between the crash and your condition.
How much is my claim worth if I had a pre-existing back injury?
Settlement value depends on the severity of aggravation, your medical treatment, lost income, and pain and suffering—not on whether a prior condition existed. We evaluate your specific damages and pursue fair compensation based on the harm the accident caused.
Don't Delay—Act Quickly
The sooner you seek medical treatment and document your injuries, the stronger your claim. Insurance companies move fast, and evidence can fade. If you've been in a car accident and your back injury has worsened, contact us right away to protect your rights.
Ready to Discuss Your Claim?
Related practice areas
- Car Accident Settlements in Florida: What Your Case May Be Worth
- What Documents Prove the Value of a Car Accident Injury Claim?
- Herniated Disc From a Car Accident: What Your Claim May Involve
- How Insurance Adjusters Value a Car Accident Settlement Offer
- Spinal Cord Injuries: A Guide for Victims and Families Facing Paralysis
- Paralysis