

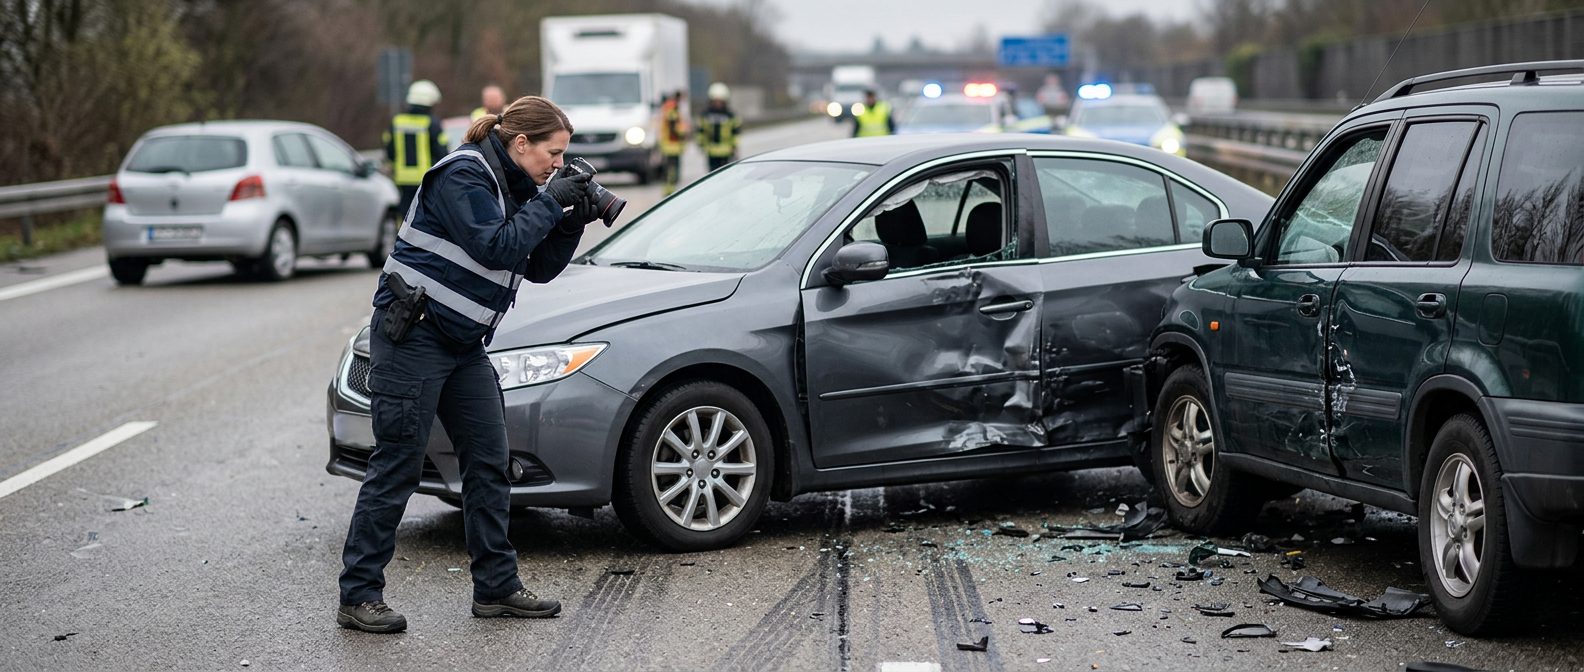
Car Accident Claims
Car Accident Settlement Payout: What's Reasonable?
Understanding how settlements are calculated, what factors matter, and how to recognize a fair offer.
By CHG Lawyers · Published September 25, 2026
What Is a Reasonable Payout for a Car Accident Injury?
A reasonable car accident settlement covers your documented medical costs, lost wages, and property damage. It also includes fair compensation for pain, suffering, and any lasting effects.
What counts as “reasonable” depends on several factors: how serious your injury is, how clear the liability (who caused the crash) is, the at-fault driver’s insurance limits, and Florida law. There’s no fixed number.
Accepting too little leaves you paying costs the other driver should cover. Demanding unreasonably high amounts stalls negotiation and may force you into a trial you didn’t want.
If you're weighing a settlement offer or unsure whether your injuries justify a higher payout, people in your situation reach out regularly. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Settlement Ranges by Injury Severity
The amount you can reasonably expect depends heavily on how serious your injury is.
Minor injuries (soft tissue damage, minor fractures, brief treatment) typically settle for $5,000–$25,000. These cases involve short recovery periods, modest medical bills, and little or no lost work time.
Moderate injuries (significant fractures, extended physical therapy, some lost wages) typically range from $25,000–$100,000. Treatment lasts weeks or months. You may miss substantial work time but eventually return to normal function.
Serious injuries (permanent scarring, chronic pain, ongoing medical care, substantial lost wages) typically settle for $100,000–$500,000+. These injuries cause lasting effects but don’t prevent independent living.
Catastrophic injuries (spinal cord damage, paralysis, traumatic brain injury, amputation, severe burns) often command $500,000–$2,000,000+ or higher. These injuries permanently alter your life. They require lifelong care and eliminate or severely limit your earning capacity. In the catastrophic-injury cases our attorneys handle, settlements reflect the full scope of lifetime medical, rehabilitation, and personal care costs—not just immediate treatment.
Wrongful death settlements vary widely based on the victim’s age, earning capacity, and dependents, but often reach substantial amounts. Families left behind after fatal crashes face both emotional devastation and financial hardship. Settlements should reflect both.
These ranges are illustrative, not promises. Your case is unique. Only a detailed review of your specific damages can determine what’s reasonable for you.
How Insurance Companies Calculate Payout Amounts
Insurers use a structured approach to value claims. Understanding their method helps you evaluate their offers.
Economic damages (hard, documented costs) include:
- Medical bills: emergency care, surgery, hospitalization, imaging, lab work
- Ongoing treatment: physical therapy, mental health counseling, specialist visits
- Prescription medications and medical equipment (braces, wheelchairs, adaptive devices)
- Lost wages (time already missed from work)
- Lost earning capacity (reduced ability to earn in the future due to permanent injury)
- Property damage (vehicle repair or replacement, rental car costs)
Non-economic damages (subjective, harder to quantify) include:
- Pain and suffering during recovery
- Emotional distress, anxiety, depression
- Loss of enjoyment of life (inability to do activities you loved)
- Permanent scarring or disfigurement
- Loss of consortium (impact on your spouse or family relationships)
Insurers typically use one of two methods to calculate non-economic damages:
The multiplier method: Total economic damages × 1.5 to 5 (or higher for severe injuries). A minor injury might use a 1.5× multiplier. A serious, permanent injury might use 4× or 5×.
Example: $20,000 in medical bills and lost wages × 3 = $60,000 in pain and suffering, for a total of $80,000.
The per diem method: A daily rate for pain and suffering × number of days of recovery or ongoing impact.
Example: $200 per day × 180 days = $36,000 in non-economic damages.
Coverage limits cap your recovery: Your settlement cannot exceed the at-fault driver’s liability insurance limit, even if your damages are higher. The policy limit caps what the insurer pays, not what the at-fault party owes; your own UM/UIM coverage may add to the recovery. If they carry $50,000 in coverage and your damages total $150,000, you can only recover $50,000 from their insurer—unless you have underinsured motorist (UIM) coverage on your own policy, which can bridge the gap.
Key Factors That Affect Your Settlement Amount
Several factors push settlement value up or down:
-
Severity and permanence: Permanent injuries command higher payouts than temporary ones. A broken arm that heals fully is worth less than a spinal cord injury that causes lifelong paralysis.
-
Medical documentation: Clear, detailed medical records and evidence of ongoing treatment increase credibility and value. Gaps in care or failure to follow doctor’s orders reduce settlement offers.
-
Liability: If the other driver clearly caused the crash, your position is strong. If fault is shared, your recovery is reduced under Florida’s comparative fault law.
-
Insurance coverage limits: The at-fault driver’s policy limit is your ceiling. If they have $25,000 coverage, that’s your maximum from their insurer.
-
Lost income and earning capacity: Documented wage loss and reduced future earning power increase settlement value significantly. A 35-year-old earning $80,000 annually who suffers a permanent injury has decades of lost earning capacity ahead.
-
Age and life expectancy: Younger victims with longer lives ahead often receive higher awards for permanent injury. They face more years of medical care and lost opportunity.
-
Pre-existing conditions: Insurers may argue prior injuries reduce settlement. Medical evidence proving the crash caused or worsened your current injury is critical.
Is $50,000 a Good Settlement for a Car Accident?
It depends entirely on your damages.
If your medical bills total $8,000, lost wages $5,000, and pain and suffering is reasonable, then $50,000 may be generous.
If your medical bills are $60,000, you’ve lost significant work time, and you have permanent injury, then $50,000 is likely far too low.
For minor to moderate injuries with documented costs under $20,000, a $50,000 offer can be reasonable. For serious or permanent injuries, $50,000 rarely covers your full damages.
Always compare any offer to your actual out-of-pocket costs plus a realistic multiplier (1.5 to 5) for pain and suffering. If the offer falls short, counter with documentation.
How Much of a Settlement Will You Actually Receive?
The gross settlement amount isn’t what you take home.
If you hired an attorney: Your settlement is reduced by attorney fees (typically 25–40% on contingency), court costs, medical liens (amounts hospitals or doctors claim from your recovery), and outstanding medical bills.
Example: $100,000 settlement → 33% attorney fee ($33,000) → $67,000 remaining → minus $5,000 medical lien → minus $2,000 court costs → you receive approximately $60,000.
If you settled without an attorney: You avoid attorney fees but still owe any outstanding medical bills, liens, or subrogation claims (your insurer’s right to recover costs they paid on your behalf).
Structured settlements: Some payouts are divided into a lump sum now and periodic payments over time. This affects your immediate cash and tax treatment.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Economic vs. Non-Economic Damages: What’s Included?
Understanding the difference helps you evaluate settlement offers fairly.
Economic damages are quantifiable, documented losses:
- Medical treatment, surgery, hospitalization, emergency care
- Physical therapy, rehabilitation, ongoing specialist visits
- Prescription medications and medical devices
- Home care or in-home nursing
- Lost wages and lost future earning capacity
- Vehicle repair or replacement
- Rental car costs and transportation to appointments
Non-economic damages are subjective, harder to prove, but often substantial:
- Pain and suffering during recovery and ongoing
- Emotional distress, anxiety, depression, PTSD
- Loss of enjoyment of life (inability to work, exercise, socialize, or pursue hobbies)
- Permanent scarring, disfigurement, or visible injury
- Loss of consortium (damage to your marriage or family relationships)
- Reduced quality of life and independence
Non-economic damages often exceed economic damages in serious injury cases. They reflect the true human cost of the injury—the life you’ve lost, not just the bills you’ve paid.
How Insurance Strategy and Coverage Limits Affect Your Payout
Your recovery is constrained by the at-fault driver’s insurance and your own coverage.
At-fault driver’s liability limits: If they carry $25,000 in coverage and your damages are $100,000, you can only recover $25,000 from their insurer. You could pursue them personally for the remaining $75,000, but personal assets are often uncollectible.
Your own underinsured motorist (UIM) coverage: If your policy includes UIM, it bridges the gap. If you have $100,000 in UIM coverage and the at-fault driver’s limit is $25,000, your UIM policy can pay up to $75,000 more (depending on your policy terms).
Uninsured motorist coverage: Protects you if the at-fault driver has no insurance at all.
Comparative fault: Under Florida law, if you’re found 20% at fault for the crash, your recovery is reduced by 20%. If you’re found more than 50% at fault, you recover nothing.
Settlement negotiation: Insurers typically open with a low offer. Your response, supported by medical records and documented damages, drives the final number.
Steps to Ensure You Get a Reasonable Settlement
-
Seek immediate medical care: Document all injuries and treatment. Gaps in care weaken your claim and give insurers ammunition to minimize your payout.
-
Keep detailed records: Medical bills, receipts, pay stubs, photos of injuries and vehicle damage, police report, witness statements, and a journal of your pain and recovery.
-
Don’t accept the first offer: Insurers expect negotiation. Counter with documented damages and a realistic multiplier based on injury severity.
-
Understand your damages: Calculate economic losses precisely (add up every bill). Research comparable cases for non-economic damages in your injury category.
-
Know the at-fault driver’s coverage limits: Your settlement cannot exceed their policy limits without pursuing them personally.
-
Avoid social media: Posts about your recovery, activities, or emotions can be used to minimize your claim. Insurers monitor social media actively.
-
Consider legal representation: Attorneys often secure higher settlements than unrepresented claimants, even after fees are deducted.
Do You Need a Lawyer for a Car Accident Settlement?
It depends on your injury’s severity and the complexity of your case.
For minor injuries with clear liability and low damages (under $10,000), you may negotiate directly with the insurer and avoid attorney fees.
Insurers take unrepresented claimants less seriously and make lower initial offers.
For catastrophic injuries, permanent disability, or complex liability: Legal representation is strongly advisable. These cases involve substantial damages, complex medical causation, and often require expert witnesses or litigation.
Contingency representation: Most personal injury attorneys work on contingency—no upfront cost. They take a percentage (typically 25–40%) only if you recover. There’s no financial risk to consulting one.
Frequently Asked Questions
How long does a settlement take?
Minor cases typically resolve in 3–6 months. Moderate cases take 6–12 months. Serious cases take 1–3 years or longer if litigation becomes necessary.
Can I negotiate after receiving an offer?
Yes. Insurers expect negotiation. Counter with evidence of higher damages, medical records, and comparable case values.
What if the insurer denies my claim?
You can appeal, file a complaint with the Florida Department of Financial Services, or pursue litigation.
Do I have to accept a settlement?
No. You can reject an offer and file a lawsuit, though litigation is slower and carries the risk of losing at trial.
What if I’m partially at fault?
Florida’s comparative fault law reduces your recovery by your percentage of fault (Fla. Stat. § 768.81(6)). You can still recover if you’re 50% or less at fault.
Can I settle directly with the at-fault driver?
Typically you settle with their insurance company, not them personally. The insurer has a contractual duty to defend and settle claims on their policyholder’s behalf.
Why Work With CHG Personal Injury Lawyers on Your Settlement
Our practice focuses exclusively on personal injury cases, including car accidents ranging from minor injuries to catastrophic, life-altering harm. We’re Florida-based with experience handling cases nationwide, giving us deep knowledge of Florida’s comparative fault law and how insurers operate in this state (Fla. Stat. § 768.81(6)).
Our licensed Florida attorneys handle negotiation, documentation, and litigation if settlement talks stall. We work on contingency—no upfront cost. We recover a percentage only if you do. We explain your damages, settlement strategy, and what to expect at each stage, so you’re never in the dark.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Get Your Settlement Evaluated
If you’re weighing a settlement offer or unsure whether your injuries justify a higher payout, people in your situation reach out regularly. We offer a free case evaluation where we review your accident, injuries, and damages to give you a realistic range for your case—with no obligation and no cost. Contact us today to get started.
What Affects Your Settlement Amount
Medical Expenses
All treatment costs—emergency care, surgery, hospitalization, therapy, medications, and ongoing medical needs—form the foundation of your claim.
Lost Wages & Earning Capacity
Income lost during recovery, plus reduced earning potential if injuries prevent you from returning to your prior job or earning level.
Pain, Suffering & Quality of Life
Compensation for physical pain, emotional trauma, lost enjoyment of activities, and permanent disability or disfigurement.
Liability & Fault
How clearly the other driver caused the crash, evidence of negligence, and any comparative fault on your part all influence settlement value (Fla. Stat. § 768.81(6)).
How to Evaluate a Settlement Offer
Review the Math
Verify that all medical bills, receipts, pay stubs, and therapy records are included. Insurers sometimes undercount or omit expenses.
Compare to Similar Cases
Settlements for comparable injuries in your area provide a benchmark. Severity, age, occupation, and prognosis all matter.
Account for Future Costs
If your injury is permanent, factor in ongoing medical care, equipment, home modifications, and long-term disability needs.
Don't Rush
Insurers count on injured people accepting low offers quickly. Take time to gather evidence and understand the full scope of your damages.
Red Flag: Settling Too Soon
Accepting an offer before you know the full extent of your injuries—especially in cases involving head, neck, or spinal injuries—can leave you without compensation for complications that emerge months or years later. Once you settle, you typically cannot reopen the claim.
Common Settlement Questions
How long does settlement take?
Minor cases often resolve in 3–6 months. Moderate cases may take 6–12 months. Serious or catastrophic injuries can take 1–3 years or longer if litigation is necessary.
Can I negotiate after receiving an offer?
Yes. Insurers expect negotiation. You can counter with medical records, evidence of higher damages, and comparable case values to support a higher settlement.
What if the insurer denies my claim?
A denial doesn't end your case. You have options, including filing a complaint with your state's insurance regulator or pursuing a lawsuit.
Do I have to accept the first offer?
No. The first offer is rarely the best offer. Most claims benefit from negotiation, especially when you have strong evidence of liability and damages.
Why the Settlement Process Matters
Your Recovery Comes First
A fair settlement should cover not just today's bills, but the full cost of your recovery and any permanent impact on your life.
You're Not Alone in This
Insurance companies have teams of adjusters and lawyers. You deserve someone in your corner who understands your injuries and fights for fair value.
Knowledge Is Power
Understanding how settlements are calculated and what factors matter puts you in a stronger position to recognize a reasonable offer.