

Car Accident Neck Injuries
Neck Pain After a Car Accident: What Insurance Adjusters Don't Want You to Know
Insurance companies use tactics to minimize settlement offers. Learn how they evaluate neck injury claims—and how to protect your recovery.
By CHG Lawyers · Published September 22, 2026
How Insurance Adjusters Value a Neck Pain Car Accident Settlement
When you’re injured in a car accident, an insurance adjuster doesn’t guess at a settlement number. They follow a step-by-step process to calculate what your neck pain claim is worth. They combine medical records, your documented losses, pain-and-suffering calculations, and fault assessment to reach an offer. Understanding how they work helps you recognize whether their initial offer is fair.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Insurance Adjusters Look At
Insurance adjusters weigh medical documentation, financial losses, and legal factors to assign a dollar value to your case. Their job is to minimize payouts while staying defensible. Understanding their process helps you spot when an offer may undervalue your injury.
The valuation process isn’t random. Adjusters combine hard facts—medical bills, wage statements, imaging reports—with more subjective assessments like pain severity and how the injury affects your life. The stronger your documentation, the harder it is for them to argue your neck pain car accident settlement is worth less.
Medical Evidence: The Foundation of Your Settlement
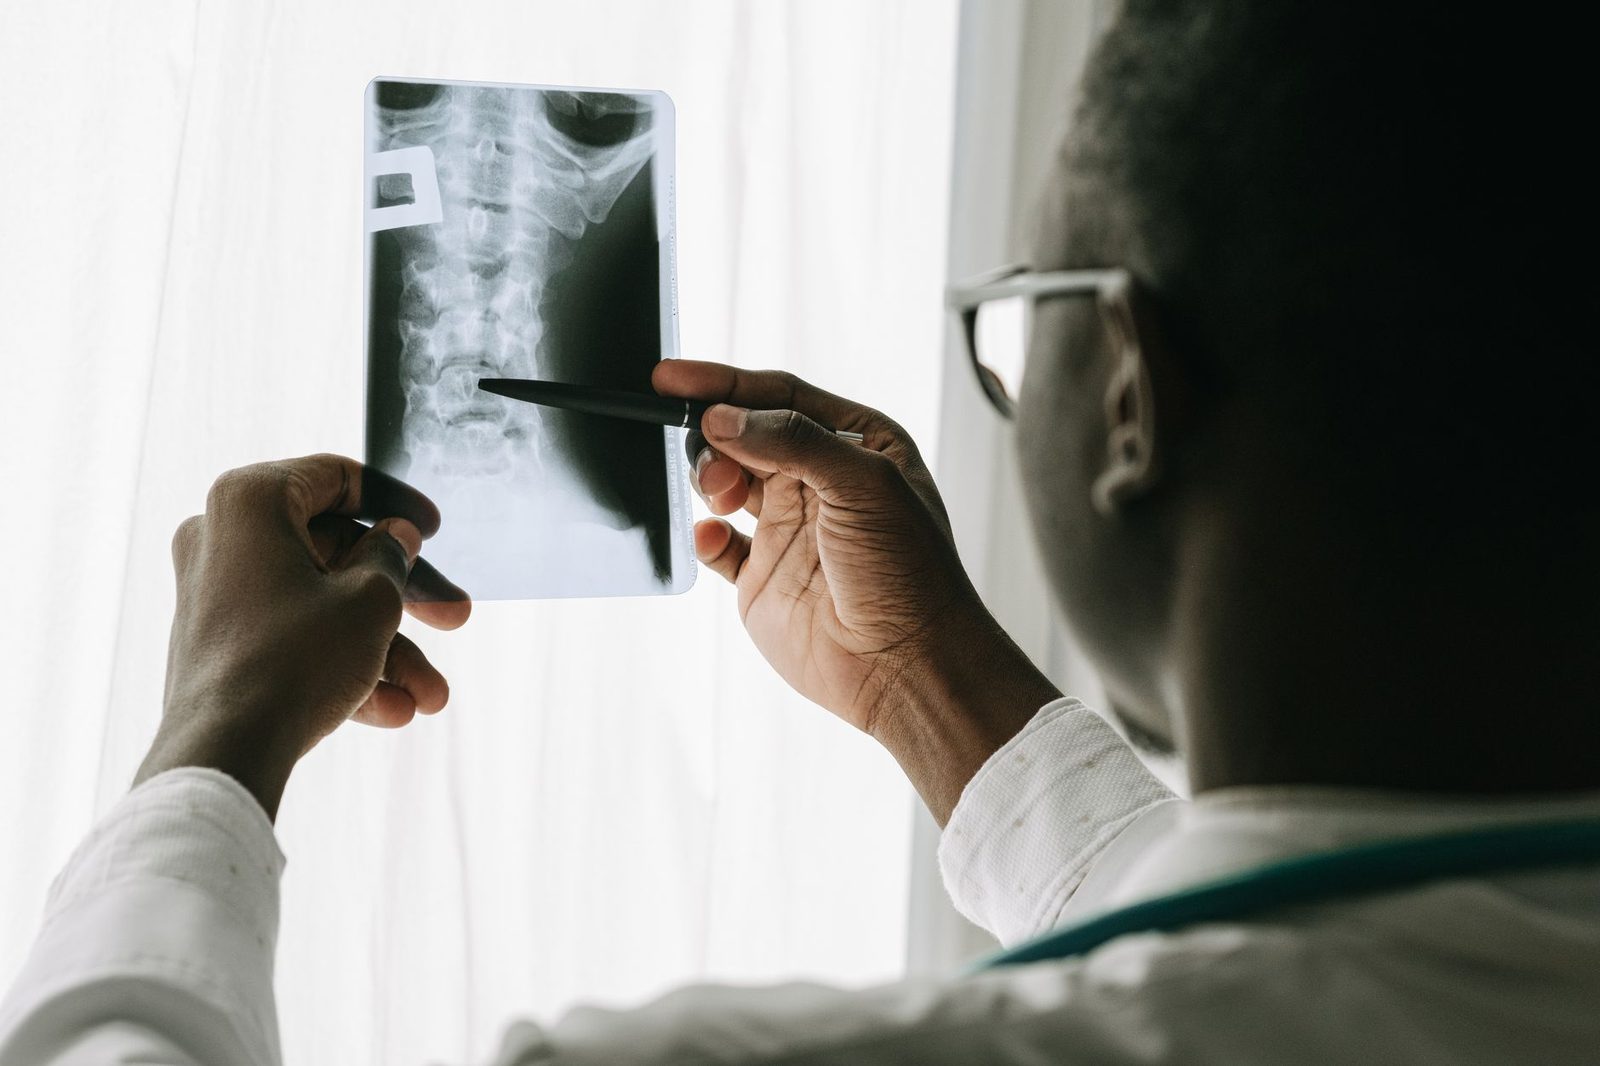
Your medical records are the foundation of your claim’s value. Adjusters examine your diagnosis, treatment records, and imaging studies (X-rays, MRI scans) to understand the injury severity.
Neck injuries from car accidents vary widely:
- Whiplash (soft-tissue injury from sudden acceleration and deceleration) is common but typically settles lower.
- Herniated or bulging discs in the cervical spine cause chronic pain and may require surgery, commanding higher settlements.
- Nerve damage or radiculopathy (pain radiating down your arm) increases settlement value significantly.
- Fractures or structural damage to the vertebrae result in the highest settlements.
Ongoing treatment matters. If you see an orthopedist, neurologist, or physical therapist after your initial visit, adjusters view your injury as more serious. Repeated visits signal that conservative care alone isn’t resolving your pain.
Gaps in treatment—weeks or months without seeing a doctor—give adjusters reason to argue your injury wasn’t severe or has already healed.
Pre-existing neck conditions complicate things. If you had a prior neck problem, the adjuster may argue the accident didn’t cause new injury. However, Florida law recognizes that a car accident worsening a pre-existing condition still creates liability. Your medical records should clearly document how the accident changed your condition or accelerated your symptoms.
Economic Damages: Lost Wages and Medical Costs
Adjusters calculate all out-of-pocket expenses: emergency room visits, imaging, surgery, physical therapy, medications, and medically necessary care. They also include lost wages if your injury prevented you from working during recovery.
Documentation is everything. Medical bills, receipts, pay stubs, and employer statements prove your losses. The more complete your financial record, the harder it is for an adjuster to dispute your claim. If you missed work but didn’t document it, the adjuster won’t count it.
Future medical costs may also be included if they’re medically necessary and reasonably foreseeable. For example, if your doctor recommends ongoing physical therapy or anticipates future surgery, those costs can be part of your settlement.
Pain and Suffering: The Harder-to-Quantify Factor
Pain and suffering compensation covers physical pain, emotional distress, loss of enjoyment of life, and reduced quality of life. Adjusters use a multiplier method to calculate this.
Here’s how it works: They multiply your total medical expenses by a number, typically between 1.5 and 5, depending on injury severity.
- A mild whiplash case might use a 1.5 multiplier.
- A serious injury with chronic pain and limited mobility might justify a 4 or 5.
- If your medical bills total $20,000, a 3× multiplier would yield $60,000 in pain-and-suffering compensation.
Your own testimony matters. Describe how the injury affects your daily life—difficulty sleeping, inability to work, lost hobbies, strained relationships. Medical records documenting your pain levels, functional limitations, and treatment frequency support a higher multiplier. The more evidence that your injury is chronic and life-altering, the higher the multiplier the adjuster should apply.
Liability and Fault: How Responsibility Affects Your Settlement
The clearer the other driver’s fault, the higher the settlement offer is likely to be. Adjusters review police reports, witness statements, traffic laws, and accident scene evidence to assess liability.
Under Florida Statute §768.81, Florida follows modified comparative fault. If you’re found partially at fault, your settlement is reduced by your percentage of fault.
Example: If your damages total $100,000 but you’re found 20% at fault, your recovery is reduced to $80,000. If you’re found more than 50% at fault, you recover nothing.
Strong liability evidence—traffic camera footage, clear traffic violations, or admissions from the other driver—increases your leverage. Disputed liability claims take longer to resolve and often result in lower initial offers.
Insurance Policy Limits: The Ceiling on Your Payout
No settlement can exceed the at-fault driver’s insurance policy limit. If your damages exceed their coverage, you may have other recovery options: your own underinsured motorist coverage or a lawsuit against the at-fault driver personally.
Adjusters know the policy limit and may anchor their offer to it. Understanding the available coverage helps you set realistic expectations.
Common Neck Injuries and Their Settlement Ranges
Settlement amounts vary widely based on your specific diagnosis, treatment response, and long-term prognosis. Here are general ranges:
- Whiplash (soft-tissue injury): $5,000–$15,000 for mild cases; $15,000–$30,000 for moderate cases with ongoing symptoms.
- Herniated or bulging discs: $25,000–$100,000, depending on whether surgery is needed and nerve involvement.
- Nerve damage or radiculopathy: $50,000–$150,000 or higher, reflecting chronic pain and functional limitations.
- Fractures or structural damage: $100,000 and up, depending on permanence and surgical intervention.
These are general ranges. Your actual settlement depends on your specific circumstances, the strength of your medical evidence, and the clarity of liability. An adjuster’s initial offer is often lower than what your claim is actually worth—negotiation is normal and expected.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Do Steroid Injections Increase Settlement Value?
Steroid injections, epidural injections, and other interventional treatments signal that conservative care did not fully resolve your pain. Adjusters recognize this as evidence that your injury is more serious and longer-lasting.
Documentation of these procedures—when they were performed, what they targeted, and their results—strengthens your claim. If injections provide only temporary relief, they support a higher settlement because they demonstrate ongoing pain. The key is medical evidence showing the treatment was medically necessary and its actual outcome.
How Long Does a Neck Injury Settlement Take?
Simple neck injury claims with clear liability may settle in weeks to a few months. More complex cases—disputed fault, serious ongoing symptoms, or high medical costs—can take 6 months to over a year.
A common tactic: Adjusters may delay settlement while you’re still in active treatment, hoping your condition improves and reduces the claim value. Completing medical treatment before settlement negotiations often results in a faster, more favorable resolution. Once your doctor says you’ve reached maximum medical improvement, your claim is more stable and easier to value.
Red Flags: When an Offer May Be Too Low
Watch for these warning signs:
- Early offers before treatment is complete. Offers made while you’re still seeing doctors often undervalue your claim.
- Downplaying your symptoms. If an adjuster suggests your pain will resolve without medical basis, they’re trying to minimize the claim.
- Ignoring documented losses. An offer that doesn’t account for all your medical expenses, lost wages, or future care is likely too low.
- Assuming premature return to work. If the adjuster assumes full capacity when your medical records show ongoing limitations, the offer is suspect.
- Vague valuation. If the adjuster can’t explain how they arrived at their number, it may warrant negotiation or legal review.
How Much Compensation Will I Get?
There’s no fixed formula—every claim is unique. Your settlement depends on injury severity, quality of medical documentation, total economic losses, clarity of fault, your age and earning capacity, pre-existing conditions, insurance policy limits, and evidence strength.
Mild whiplash claims may settle for $5,000 to $15,000. Moderate neck injuries with ongoing treatment may range from $15,000 to $50,000. Serious injuries with chronic pain, limited mobility, or surgical intervention can exceed $100,000. These are general ranges; your actual settlement depends on your specific circumstances.
How Long After a Car Accident Can Neck Pain Appear?
Neck pain can appear immediately after a crash or develop over hours or days as inflammation builds. Delayed-onset pain is common in whiplash and soft-tissue injuries. Some people don’t notice symptoms until they attempt normal activities or wake the next morning.
Seeking medical evaluation promptly—even if you feel fine initially—creates documentation that protects your claim. Florida law recognizes delayed injuries; prompt medical records strengthen your credibility and prevent adjusters from disputing pain that appears weeks after the accident.
Negotiating with the Insurance Adjuster
The adjuster’s first offer is rarely their final offer. Respond with a counter-offer supported by medical evidence and documented losses. Provide any new medical records, test results, or treatment updates. Explain how your injury affects your daily life and work capacity.
Stay professional and factual. Emotional appeals rarely move adjusters. If negotiations stall or the adjuster refuses to budge despite strong evidence, it may be time to seek legal guidance to protect your rights.
When you’re preparing your response, learn how to document car accident injuries thoroughly and understand insurance settlement negotiation tips to strengthen your position.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
FAQ
What factors affect car accident settlement amount?
Injury severity, medical documentation quality, total economic losses, clarity of fault, your age and earning capacity, pre-existing conditions, insurance policy limits, jurisdiction, and strength of evidence all influence settlement value.
Do I need to complete medical treatment before settling?
Completing treatment—or reaching maximum medical improvement—often results in a faster, higher settlement because your final condition is clear and the claim is more stable.
What if I’m found partially at fault in Florida?
Under Florida’s comparative fault law, your settlement is reduced by your percentage of fault. If you’re more than 50% at fault, you recover nothing.
Can I recover future medical costs?
Yes, if they’re medically necessary and reasonably foreseeable—for example, ongoing physical therapy or anticipated surgery recommended by your doctor.
What if the settlement offer doesn’t match my medical bills?
An offer that ignores documented expenses is a red flag. Respond with your complete medical records and a detailed accounting of all losses, then counter-offer with a higher figure supported by evidence.
If you’re navigating a neck pain car accident settlement and an insurance offer doesn’t seem to reflect your actual losses and pain, our team can review your situation. People in exactly your situation reach out regularly to understand whether their offer is fair and what their claim may actually be worth.
When you’re ready to understand your options, learn about when to hire a personal injury attorney and explore your car accident injury claims in detail.
How Adjusters Evaluate Neck Injury Claims
Medical Documentation
Adjusters scrutinize your medical records, imaging (X-rays, MRI), and treatment history. Gaps in care or delayed treatment can be used to argue your injury is minor. Consistent, timely medical attention strengthens your claim.
Fault and Liability
The clearer the other driver's fault, the higher the settlement. Adjusters review police reports, witness statements, and accident scene evidence. Comparative negligence rules in your state can reduce your recovery if you share any fault.
Economic Losses
Adjusters calculate medical bills, lost wages, and ongoing treatment costs. They may dispute the necessity of certain treatments or argue that your income loss is overstated. Detailed documentation of all expenses is critical.
Insurance Policy Limits
Your recovery cannot exceed the at-fault driver's policy limit. If your damages exceed that cap, you may need to pursue additional claims. Adjusters know these limits and often anchor their offers to them.
Common Adjuster Tactics That Reduce Settlements
Minimizing Your Injury
Adjusters may claim neck pain is temporary or not serious enough to warrant a large settlement, even if your medical records show ongoing treatment and functional limitations.
Delay and Pressure
Adjusters often delay investigations or push you to settle quickly before you've completed treatment. Early settlements lock in lower amounts and prevent recovery for future care.
Disputing Causation
They may argue your neck pain stems from a pre-existing condition, not the accident. Medical evidence linking your injury directly to the crash is essential to counter this.
Social Media Surveillance
Adjusters monitor your social media for posts or photos that contradict your injury claims. Even innocent activity can be twisted to suggest you're not as hurt as you claim.
Don't Settle Too Early
Accepting the first offer from an adjuster often means leaving money on the table. Neck injuries can develop complications months after an accident. Settling before you've completed treatment or reached maximum medical improvement can prevent you from recovering for ongoing pain, therapy, or long-term care.
Steps to Strengthen Your Neck Injury Claim
Seek Immediate Medical Care
Get evaluated by a doctor right after the accident, even if pain develops later. Document all symptoms, treatments, and diagnoses. Adjusters use gaps in medical records to argue your injury is exaggerated.
Keep Detailed Records
Maintain a journal of your pain levels, functional limitations, missed work, and treatment costs. Photograph any visible injuries. Collect receipts for medical care, medications, and related expenses.
Follow Medical Advice
Complete all prescribed treatments, physical therapy, and follow-up appointments. Skipping treatment gives adjusters ammunition to claim your injury isn't serious. Consistency matters.
Don't Communicate Directly with the Adjuster
Anything you say can be used against you. Let an attorney handle negotiations. Adjusters are trained to extract statements that minimize your claim's value.
Why You Need Legal Representation
We Know Adjuster Tactics
Our firm focuses exclusively on personal injury cases. We understand how adjusters work and how to counter their arguments with evidence and strategy.
We Handle Negotiations
We communicate with adjusters and insurance companies on your behalf, protecting you from saying anything that weakens your claim.
We Ensure Full Recovery
We don't rush settlements. We wait until your treatment is complete and your long-term prognosis is clear, so your settlement reflects your true damages.
We Fight for Fair Compensation
We pursue the full value of your claim—medical costs, lost wages, pain and suffering, and future care—not just what an adjuster offers.
Don't Let an Adjuster Minimize Your Neck Injury
Related practice areas
- Chronic Pain After a Car Accident: How It Affects Your Claim
- Car Accidents in Florida
- Car Accidents in Miami
- Jet Ski Drowning Injury Claims & Anoxic Brain Injury