

Car Accident Settlement Guide
Understanding Soft Tissue Injury Settlements After a Car Accident
Learn what affects your claim value, how to document your injury, and what to expect in the settlement process.
By CHG Lawyers · Published September 15, 2026
Soft Tissue Injury Car Accident Settlement: How Insurers Downplay Your Claim & How to Fight Back
You were hit by another driver. The pain started in your neck and shoulders the next day—or maybe it took a week to appear. You saw your doctor, got imaging done, and started physical therapy. But when you called the insurance company, the adjuster sounded skeptical. “It’s just whiplash,” they said. “These claims settle for very little.” They told you your injury doesn’t show up clearly on tests, so it’s harder to prove. That stings, especially when you’re still hurting months later.
This is what soft tissue injury claims are really like: they’re real, they cause lasting damage, and insurance companies routinely undervalue them. Soft tissue damage doesn’t show up on an X-ray the way a broken bone does. Understanding what counts as a soft tissue injury, how chronic pain develops, and what evidence insurers actually respect—rather than dismiss—can help you build a claim that stands up to their skepticism.
If you're living with ongoing pain months after a car accident and aren't sure whether your injury qualifies for fair compensation, reach out. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Qualifies as a Soft Tissue Injury After a Car Accident?
Soft tissue injuries damage muscles, tendons, ligaments, and connective tissue—not bone. Common soft tissue injuries from car accidents include whiplash (cervical strain), lower back strains, shoulder and rotator cuff tears, knee ligament sprains, and bruising with underlying tissue damage.
When your vehicle is struck, your body experiences rapid acceleration and deceleration. These forces stretch and tear soft tissue fibers beyond their normal range of motion. Your neck snaps forward and backward in quick succession. Your lower back is forced into an unnatural curve. Your shoulder is wrenched sideways. Ligaments in your knee are stretched or torn as your legs compress against the dashboard or seat.
Symptoms may appear right away or develop over days as swelling sets in. This delayed onset is one reason insurers doubt soft tissue claims: if you didn’t report pain at the scene, they assume you weren’t injured. Medical science tells a different story. Inflammation takes time to develop. Swelling and stiffness worsen as your body’s inflammatory response kicks in.
The difference between acute injury and chronic pain matters for your claim. An acute injury is the immediate tissue damage from the crash—the torn fibers, the stretched ligaments. Chronic pain is ongoing discomfort that lasts for weeks, months, or longer after the accident. Chronic pain drives settlement value upward because it shows the true, lasting impact of the injury on your daily life.
How Chronic Pain Develops—and Why Insurers Underestimate It
When soft tissue is torn or stretched, your body starts an inflammatory response: swelling, stiffness, and pain. Over weeks, scar tissue forms as your body tries to repair the damage. Scar tissue is less flexible than healthy tissue, so it restricts movement and can trigger ongoing pain.
Nerve irritation makes the problem worse. Swollen tissue and scar tissue press on nearby nerves, causing pain signals to continue even after the initial injury heals. Your nervous system becomes sensitized to pain—a condition called central sensitization—meaning even minor movements trigger significant discomfort. Post-traumatic stress from the accident itself can amplify pain perception and cause muscle tension that perpetuates the cycle.
Chronic pain is medically defined as pain lasting longer than three months. For soft tissue injuries, chronic pain often develops gradually as inflammation and scar tissue form. This ongoing pain affects your daily life: it interferes with work, disrupts sleep, limits your ability to exercise or care for your family, and can lead to depression or anxiety.
Insurers often treat chronic pain as psychological rather than physical—a mistake that undervalues your claim. The reality: chronic pain from soft tissue injury is neurobiological. It’s documented in medical literature, measurable through functional limitations, and supported by imaging in many cases. Your pain is not in your head; it’s in your tissue, your nerves, and your nervous system’s response to injury.
Common Soft Tissue Injuries from Car Accidents
Whiplash and cervical strain occur when your neck is forced beyond its normal range of motion. Pain develops in the neck, shoulders, and upper back. Symptoms include stiffness, headaches, and radiating pain down the arms. Cervical strain can damage the facet joints in your neck, leading to chronic pain that persists for months or years.
Lower back strains and lumbar injuries happen when the impact forces your spine into an unnatural position. These injuries cause localized back pain, muscle spasms, and sometimes radiating pain down the legs (radiculopathy). Lumbar strains often require extended physical therapy and can result in permanent limitations.
Shoulder and rotator cuff injuries result from the sudden force of the collision. Pain develops in the shoulder joint and upper arm, often limiting your ability to lift or reach. Rotator cuff tears can require surgery and months of rehabilitation.
Knee and leg soft tissue damage occurs when your legs are forced against the dashboard or seat. Ligament sprains in the knee are common, causing swelling, instability, and pain with walking or bending. ACL or MCL injuries can be career-ending for athletes and physically demanding workers.
Bruising and contusions appear as visible discoloration and swelling. While bruises seem minor, they indicate tissue damage beneath the skin and can cause ongoing pain and restricted movement. Deep bruising can damage muscle tissue and lead to complications like myositis ossificans (abnormal bone formation in muscle).
How Settlement Value Is Actually Calculated—Not What Insurers Tell You
Insurance companies use a formula-based approach to soft tissue claims that often undervalues your injury. Understanding this formula—and knowing how to counter it—is essential.
Medical expenses form the foundation of your claim. These include emergency room visits, imaging studies (X-rays, MRI, CT scans), physical therapy, pain management injections, specialist visits, and any ongoing treatment. Documentation of every expense is critical. If you received an MRI that revealed soft tissue damage, that imaging cost is evidence of injury severity.
Lost wages account for time you missed from work during recovery and ongoing income loss if the injury limits your ability to work. If your job requires physical activity and your injury prevents you from performing it, lost wages can be substantial. Document every missed shift, every day of unpaid leave, every reduction in hours.
Length and intensity of treatment matter significantly to insurers—but not always in your favor. Short-term treatment (a few weeks of physical therapy) suggests a minor injury. Long-term, ongoing treatment (months of physical therapy, multiple specialist visits, pain management) indicates a more serious injury. However, insurers sometimes argue that if you’re still in treatment months after the accident, you’re not following medical advice or you’re exaggerating your pain. The reality: soft tissue injuries often require extended treatment. Physical therapy for a rotator cuff injury typically lasts 8–12 weeks or longer. Chronic pain management may continue indefinitely.
Permanence is the settlement multiplier. If your pain and limitations are temporary, your settlement will be lower. If medical evidence shows that your injury is permanent—you’ll always have some level of pain or limitation—your settlement value increases substantially. A permanent injury justifies a higher multiplier applied to your medical expenses. This is where many injured people lose leverage: they settle before permanence is established, then discover months later that their pain is indeed permanent.
Impact on quality of life includes reduced ability to work, exercise, care for family members, and enjoy hobbies. Documentation of these impacts strengthens your claim significantly. If you can no longer run, play with your children, perform your job duties, or engage in activities you enjoyed before the accident, that matters to settlement value. Insurers often ignore this category entirely unless you document it explicitly.
Insurance coverage limits set a ceiling on your recovery. If the at-fault driver carries only $10,000 in liability coverage, your settlement cannot exceed that amount regardless of your damages. Florida drivers are required to carry a minimum of $10,000 in personal injury protection (PIP) coverage, but many carry substantially more. Determining the at-fault driver’s coverage limits is one of the first steps in evaluating your claim.
Strength of evidence determines how much weight your claim carries in negotiation. Medical records, imaging studies, treatment consistency, expert medical testimony, and documentation of functional limitations all strengthen your position. Weak evidence—sporadic treatment, no imaging, vague descriptions of pain—gives insurers room to downplay your injury.
Why Insurers Downplay Soft Tissue Claims—and How Medical Documentation Counters It
Insurance companies scrutinize soft tissue claims more closely than fracture claims because soft tissue injuries lack visible signs. A broken bone shows clearly on an X-ray; the insurer can’t argue with it. Soft tissue damage does not appear as definitively on standard imaging, which gives insurers room to claim your injury is exaggerated or psychological.
This skepticism is built into the system. Soft tissue claims are statistically more frequent than fracture claims, and some are fraudulent. Insurers have learned to treat all soft tissue claims with suspicion. Your job is to provide evidence so clear and consistent that skepticism becomes unreasonable.
Seek medical evaluation immediately after the accident, even if pain seems mild. Early medical records establish a clear, documented link between the accident and your injury. If you wait days or weeks to see a doctor, insurers will argue that your injury isn’t serious or that something else caused it.
Get imaging if your doctor recommends it. MRI and CT scans can reveal soft tissue damage that X-rays miss. While not all soft tissue injuries require imaging, advanced imaging provides objective evidence of damage. An MRI showing a rotator cuff tear or a ligament tear is powerful evidence that insurers cannot easily dismiss.
Maintain consistent, ongoing treatment records. Physical therapy notes, pain management visits, specialist evaluations—each document proves that your pain is genuine and persistent. Gaps in medical care—weeks without visiting a doctor or physical therapist—give insurers ammunition to argue that your injury isn’t serious. If you’re truly in pain, you should be seeking treatment regularly.
Obtain expert medical testimony from your treating physicians. Your doctor’s notes on your pain level, range of motion, and functional limitations become evidence of injury severity. If your doctor states in writing that your injury is likely permanent or will cause ongoing limitations, that statement carries significant weight in settlement negotiations.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Do Steroid Injections Increase Settlement Value?
Yes—significantly. Steroid injections demonstrate that your pain is real, significant, and not responding to conservative treatment alone. When your doctor recommends a steroid injection for pain management, you’re signaling to insurers that your injury requires intervention beyond rest and physical therapy.
Insurance companies view advanced treatments as evidence of genuine injury. If your pain could be managed with rest and over-the-counter medication, you wouldn’t need injections. The fact that your physician recommended this more intensive intervention shows that your injury is serious.
Other treatments that signal ongoing, serious injury include:
- Multiple rounds of physical therapy (especially if one round didn’t resolve your symptoms)
- Visits to pain management specialists
- Orthopedic consultations or surgical evaluations
- Advanced imaging studies (MRI, CT scans)
- Epidural steroid injections for spinal pain
- Trigger point injections for muscle pain
Each step up in treatment intensity strengthens your claim. Documentation of your response to treatment matters too: if the injection provided relief, that’s noted in your medical record. If pain persists despite the injection, that shows your injury is resistant to treatment and likely to cause lasting limitations.
Common Mistakes That Reduce Your Soft Tissue Injury Settlement
Delaying medical care after a car accident undermines your claim immediately. If you wait days or weeks to see a doctor, insurers will argue that your injury isn’t serious or that you’re fabricating it. Seek medical evaluation as soon as possible, even if pain develops gradually.
Gaps in treatment records give insurers reasons to doubt your pain. If you stop physical therapy for several weeks and then resume, insurers may claim you’ve recovered. Consistent, ongoing treatment is critical to maintaining credibility.
Social media posts showing you hiking, exercising, or engaging in activities that seem to contradict your pain claims can devastate your settlement value. Insurance adjusters monitor social media routinely. Don’t post anything that could be misinterpreted as evidence that you’re not injured. A photo of you at a family gathering, even if you were in pain that day, can be used against you.
Accepting an early settlement offer before the full extent of your injury is clear often results in severe undercompensation. Soft tissue injuries take time to fully manifest. Chronic pain may develop weeks or months after the accident. Permanence may not be clear for 6–12 months or longer. Wait until your medical condition has stabilized and your prognosis is clear before settling.
Failing to document how the injury affects your daily life limits your claim value significantly. Keep a detailed record of how pain interferes with work, sleep, exercise, and family responsibilities. Specific examples are powerful: “I missed two weeks of work,” “I can’t lift my children,” “I stopped running, which I did five times a week before the accident,” “I wake up at night because of neck pain.”
Not following medical advice weakens your claim substantially. If your doctor recommends physical therapy and you skip appointments, insurers will argue that you’re not taking your recovery seriously. Follow your treatment plan consistently.
How to Build a Strong Soft Tissue Injury Claim
Seek medical evaluation immediately, even if pain seems mild. Early medical records establish the link between the accident and your injury.
Keep detailed records of all medical visits, treatments, diagnoses, and provider notes on your pain and functional limitations. Request copies of all medical records and imaging reports.
Document how the injury affects your ability to work and perform daily activities. Write down specific examples and keep them dated. This becomes powerful evidence of impact.
Follow your doctor’s treatment plan consistently. Regular, ongoing treatment demonstrates that your pain is genuine and persistent.
Maintain a pain journal. Record when pain occurs, what triggers it, how severe it is on a scale of 1–10, and how it limits your activities. This detailed record becomes powerful evidence during settlement negotiations.
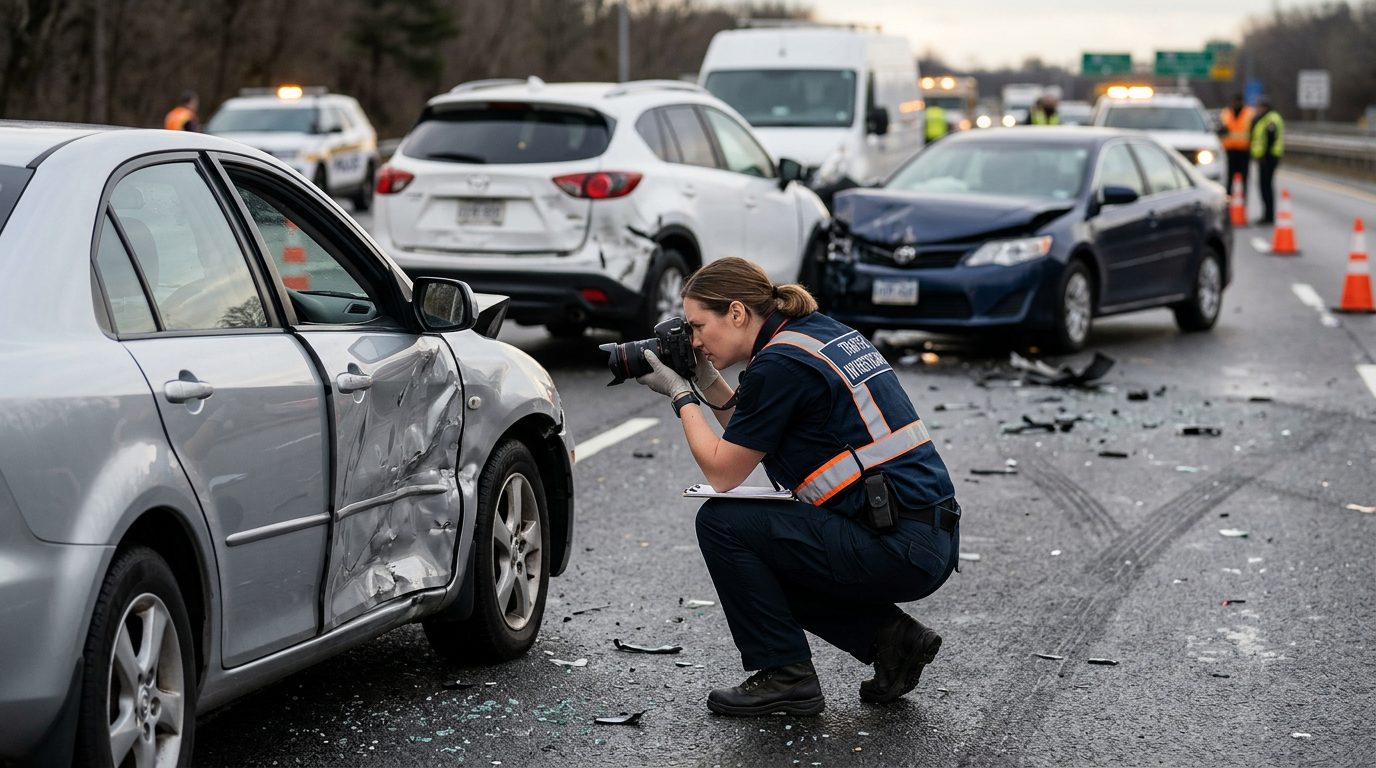
Preserve evidence from the accident: photos of vehicle damage, the police report, witness statements, and medical records from emergency care.
Avoid social media posts that could contradict your injury claim. Don’t post photos or videos of activities that seem inconsistent with your pain level.
Gather documentation of lost wages: pay stubs showing reduced hours, emails from your employer confirming missed time, or letters from your employer documenting your absence.
Understanding Your Claim Under Florida Law
Soft tissue injuries deserve serious consideration in settlement negotiations. Your chronic pain is real, and it has lasting consequences for your life. Insurance companies often downplay these injuries because they lack visible signs, but medical documentation, consistent treatment, and expert testimony can overcome that skepticism.
Under Florida law, you have two years from the date of the accident to file a lawsuit if your claim doesn’t settle. Additionally, Florida follows modified comparative fault: if you’re found more than 50% at fault for the accident, you generally can’t recover damages. If you’re 50% or less at fault, your recovery is reduced by your percentage of fault. Understanding these rules helps you assess your claim realistically and avoid settling too early.
An attorney who focuses exclusively on personal injury claims can help you value your claim accurately, negotiate with insurance companies on your behalf, and advocate for fair compensation. Having someone in your corner who understands how insurers evaluate soft tissue claims and who can counter their downplaying tactics significantly improves your settlement outcome.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Frequently Asked Questions
What is the average settlement for a soft tissue injury from a car accident?
Settlement amounts vary widely depending on medical expenses, lost wages, treatment duration, and impact on quality of life. There is no true “average” because every case is unique. A soft tissue injury with three weeks of physical therapy and no imaging may settle for $3,000–$8,000. A soft tissue injury with six months of treatment, imaging evidence, and permanent limitations may settle for $25,000–$50,000 or more. Your specific facts determine your value.
How long does soft tissue injury take to heal?
Some soft tissue injuries heal within weeks; others cause chronic pain lasting months or years. Recovery depends on injury severity, your age, overall health, and how consistently you follow treatment. Whiplash typically improves within 6–12 weeks, but some people experience chronic symptoms for years. Rotator cuff injuries often require 8–12 weeks of physical therapy or longer if surgery is needed.
Can I get compensation for a soft tissue injury if the accident was minor?
Yes. Accident severity and injury severity are not always connected. A low-speed collision can cause serious soft tissue damage, especially if you were struck from behind or at an angle. What matters is whether you have medical evidence of injury and whether the other driver was at fault.
What if I didn’t seek medical treatment right after the accident?
Delaying treatment weakens your claim because it breaks the link between the accident and your injury. Seek medical care as soon as possible, even if pain develops days later. Explain the delay to your doctor; many soft tissue injuries develop gradually as inflammation sets in.
Do I need imaging (MRI or CT scan) to prove my soft tissue injury?
Not always, but imaging strengthens your claim by providing objective evidence of damage. Your doctor will recommend imaging if it’s medically necessary. If imaging is recommended and you decline it, insurers may argue that you’re not serious about your injury.
If you’re living with ongoing pain months after a car accident and aren’t sure whether your injury qualifies for fair compensation, reach out. Many people in your situation contact us to understand their options and to get an honest assessment of what their claim is worth—not what an insurance adjuster tells them it’s worth.
Our team focuses exclusively on personal injury claims, including soft tissue injuries from car accidents. We can review your case, explain your rights under Florida law, discuss what your claim may be worth based on your specific facts, and talk about how to counter insurer downplaying tactics.
Get a free case evaluation and talk with an attorney who understands how insurance companies evaluate soft tissue claims and how to build a strong case on your behalf.
What Determines Your Settlement Amount
Medical Expenses
All treatment costs—emergency care, imaging, physical therapy, and ongoing medical visits—form the foundation of your claim value.
Lost Income
Wages lost while you recover, including time off work for appointments and treatment, are part of your damages.
Duration of Treatment
A soft tissue injury requiring three weeks of care settles differently than one requiring six months or longer.
Impact on Daily Life
Permanent limitations, chronic pain, or reduced quality of life can increase your claim's value significantly.
No Two Cases Are the Same
Settlement amounts vary widely because every injury, recovery timeline, and person's circumstances are unique. There is no true 'average' settlement. A soft tissue injury with three weeks of physical therapy and no imaging may settle for $3,000–$8,000. One with six months of treatment, imaging evidence, and permanent effects may settle for significantly more. The only way to know what your case may be worth is to have it reviewed by an attorney who understands your specific situation.
Steps to Strengthen Your Claim
Document Everything
Keep records of all medical visits, prescriptions, physical therapy sessions, and any imaging or test results. Save receipts for medical expenses and document any time missed from work.
Follow Medical Advice
Attend all appointments and follow your doctor's treatment plan. Insurance companies scrutinize gaps in treatment, so consistency matters for your claim.
Report the Accident Promptly
Notify the at-fault driver's insurance company and file a police report if one wasn't already made. Report your injury as soon as you recognize symptoms.
Avoid Social Media
Don't post about your injury, activities, or recovery on social media. Insurers monitor these accounts and may use posts to dispute the severity of your injury.
Why You Need an Attorney for Your Soft Tissue Claim
Insurance Companies Undervalue Soft Tissue Claims
Adjusters often treat soft tissue injuries as minor. An attorney knows how to present medical evidence and build a case that reflects the true impact on your life.
We Handle All the Paperwork
Settlements involve complex documentation, liability investigation, and negotiation. We manage every detail so you can focus on recovery.
We Negotiate on Your Behalf
Insurance companies are skilled at negotiating down claims. An experienced attorney knows the value of your case and fights for fair compensation.
We Know the Deadlines
There are strict time limits for filing claims and lawsuits. We ensure nothing falls through the cracks and your rights are protected.
Common Questions About Soft Tissue Settlements
How long does a soft tissue injury settlement take?
Simple claims may settle in weeks or months. Complex cases with ongoing treatment or disputed liability can take longer. Your attorney will give you a realistic timeline based on your specific situation.
What if the insurance company denies my claim?
Denial doesn't end your case. An attorney can challenge the denial, gather additional evidence, and pursue the claim through negotiation or litigation if necessary.
Do I have to go to court?
Most soft tissue injury cases settle without trial. However, if the insurance company refuses a fair offer, your attorney will be ready to take your case to court.
What if I had a pre-existing condition?
A pre-existing injury doesn't disqualify your claim. You can recover for the aggravation or worsening of that condition caused by the accident.
No Fees Unless There Is a Recovery
We work on contingency, meaning we only get paid if your case settles or wins. You pay nothing upfront, and there are no out-of-pocket costs for you to worry about.