

Car Accident Claims
What Your Car Accident Settlement Is Really Worth
Settlement value is built on evidence, not sympathy. Learn which documents prove your claim's value and how to organize them so nothing gets missed.
By CHG Lawyers · Published September 15, 2026
Car Accident Settlement Documentation: What Proves Your Claim’s Value
Settlement value in a car accident case is built on evidence, not sympathy. Insurance adjusters calculate offers using a formula: they add documented medical costs and lost wages, apply a multiplier for pain and suffering, then look for documentation gaps to justify paying less.
This guide explains which documents serve which legal purposes, why early collection matters, and how to organize your evidence so nothing gets missed.
If you're unsure whether your documentation is complete, whether an offer is fair, or what your claim might be worth, contact us. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why Each Document Type Serves a Specific Legal Purpose
Every document in your claim does specific work. Understanding what each proves helps you gather the right evidence and recognize what’s missing.
Medical records prove causation and severity. They establish that the accident caused your injury, not a pre-existing condition or unrelated event. They show how serious the injury is—imaging results, diagnoses, treatment intensity, and duration all matter.
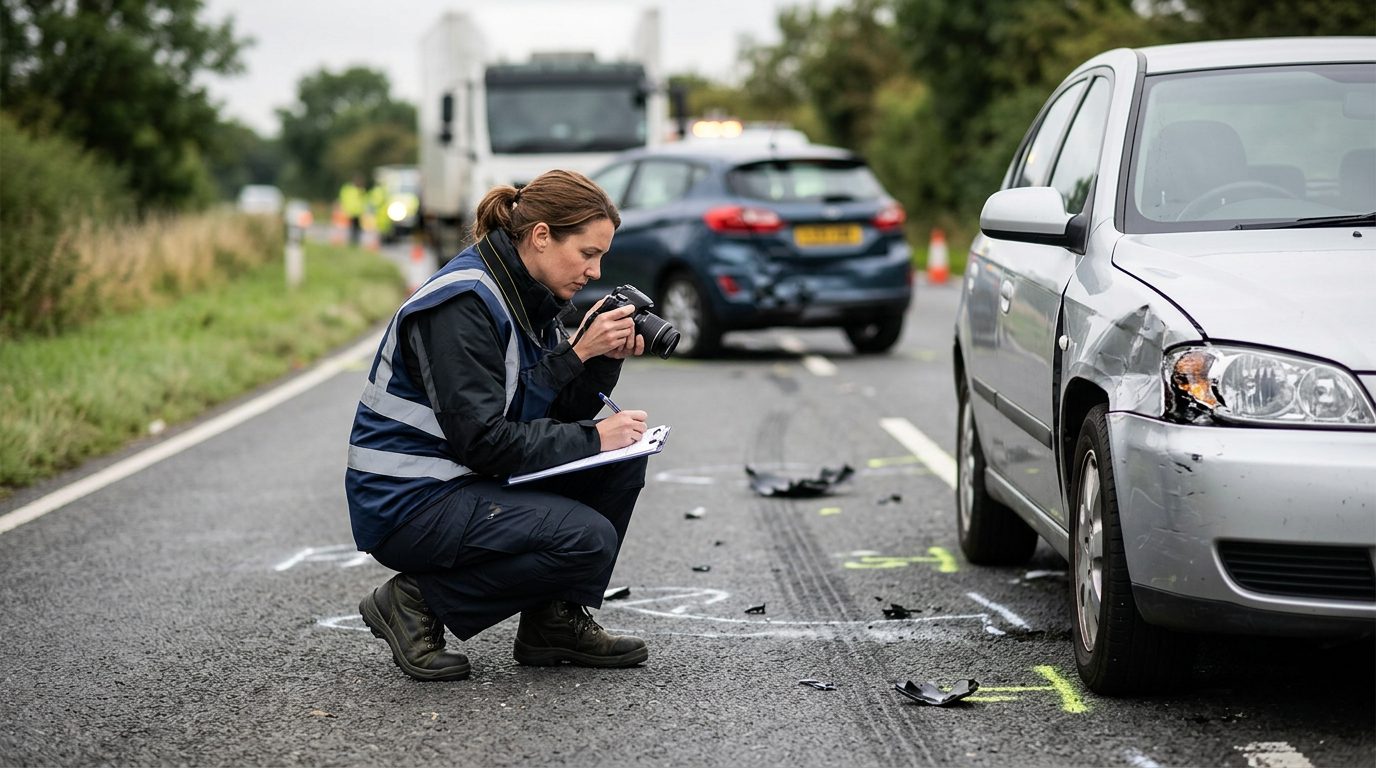
The police report and accident scene evidence prove liability. They show who was at fault and how the accident happened. In Florida, comparative fault law means your recovery is reduced by your percentage of fault. A police report establishing the other driver’s fault protects you.
Economic damages documentation—medical bills, pay stubs, receipts—proves financial loss. Insurance adjusters add these up to establish your claim’s baseline value. The baseline becomes the foundation for calculating non-economic damages (pain and suffering). A higher baseline produces a higher multiplier.
Non-economic damages evidence—personal journals, photographs, family testimony—proves the injury’s real impact on your life. It shows ongoing pain, activity limitations, emotional effects, and lost opportunities. This evidence determines the multiplier applied to your economic damages.
Missing any category weakens the entire claim. An adjuster without medical records assumes the injury wasn’t serious. Without wage documentation, they assume you didn’t lose income. Without evidence of ongoing impact, they assume quick recovery.
The Urgency of Early Documentation Collection
Evidence degrades. Memories fade. The statute of limitations is finite.
Evidence degrades. Accident scene conditions change. Photographs taken weeks later show different lighting, weather, and road conditions than the accident scene. Witness memories become unreliable. People forget details. Some witnesses move away or become unreachable.
Memories fade. You may not remember exactly how the accident happened, what you felt immediately after, or which symptoms appeared first. Writing these details down within days of the accident creates credible, contemporaneous evidence. A journal entry written three weeks after the accident is more reliable than your recollection six months later.
The statute of limitations is finite. In Florida, you have two years from the date of the accident to file a personal injury lawsuit for most claims arising on or after March 24, 2023. Earlier claims generally had a two-year deadline. Insurance negotiations take months. You need all documentation organized and ready before settlement discussions begin.
Act within 30 days of the accident. Request medical records, the police report, and witness information immediately. Photograph the accident scene, your injuries, and vehicle damage while they’re still visible. Write down what happened while it’s fresh. Early action preserves evidence and strengthens your claim.
Medical Records and Treatment Documentation
Medical records are the foundation of your claim. They establish causation (the accident caused the injury) and severity (how serious it is).
Gather records from every provider who treated you:
- Emergency room or urgent care records: visit date, vital signs, clinical observations, imaging results, diagnosis, treatment provided, and discharge instructions.
- Physician notes: all office visits, clinical findings, examination results, treatment recommendations, and progress notes. These show whether your condition improved, worsened, or plateaued.
- Diagnostic imaging reports: X-ray, CT scan, and MRI results with radiologist interpretation. These provide objective evidence of structural injury.
- Physical therapy records: session dates, therapist observations, exercises prescribed, progress, and any setbacks or complications.
- Prescription records: medications prescribed, dosages, and duration. Ongoing prescriptions indicate ongoing treatment and pain.
- Mental health records: if the accident caused anxiety, depression, PTSD, or other psychological injury.
Request copies immediately. Most providers provide records within 30 days for a small fee (typically $1–2 per page). Don’t wait. Gaps in medical records suggest to adjusters that the injury wasn’t serious enough to warrant treatment.
The Police Report and Accident Scene Evidence
The police accident report documents how the accident happened and establishes fault.
The report typically includes:
- Officer observations: vehicle damage, road and weather conditions, traffic signals, visibility, and lighting at the time of the accident.
- Driver statements: what each driver told the officer about how the accident occurred.
- Citations issued: traffic violations cited (speeding, running a red light, failure to yield, improper lane change). A citation against the other driver strengthens your liability case.
- Witness statements: names, contact information, and accounts from people who saw the accident.
- Accident diagram: a sketch showing vehicle positions, direction of travel, and point of impact.
Gather your own evidence too:
- Photographs of vehicle damage: yours and the other driver’s vehicles from multiple angles, showing impact points and severity.
- Photographs of the accident scene: road markings, traffic signals, sight lines, hazards, and conditions that affected visibility or safety.
- Witness contact information: names, phone numbers, and email addresses collected at the scene. Witness statements made immediately after the accident are more reliable than recollections months later.
Under Florida’s modified comparative fault rule, if you’re more than 50% at fault, you recover nothing. If you’re 50% or less at fault, your recovery is reduced by your percentage of fault. A police report and scene evidence establishing the other driver’s fault protects you.
Economic Damages Documentation
Economic damages are documented out-of-pocket costs. They have receipts and invoices. Insurance adjusters add them up to establish your claim’s baseline value.
Gather and organize:
- Medical bills: from hospitals, emergency rooms, physicians, specialists, physical therapists, imaging centers, and any other provider who treated you.
- Pay stubs or employer letter: showing your regular wages and the dates you missed work due to injury or medical appointments. An employer letter stating your hourly rate and dates absent is acceptable if pay stubs aren’t available.
- Tax returns or business records: if self-employed, your past two years’ tax returns establish your average income and support lost-income claims.
- Medical equipment and supplies: receipts for wheelchairs, mobility aids, braces, crutches, grab bars, home modifications, compression garments, or other equipment necessitated by your injury.
- Transportation costs: mileage to medical appointments (valued at the IRS standard mileage rate, currently 67 cents per mile for 2024), rideshare receipts, or medical transport invoices.
- Childcare or household help: receipts for paid help if your injury prevented you from caring for children or maintaining your home.
- Prescription costs: receipts for medications prescribed as a result of the accident.
Insurance adjusters add all documented economic damages to establish your claim’s baseline. This baseline becomes the foundation for calculating non-economic damages. A $50,000 baseline supports a higher pain-and-suffering multiplier than a $10,000 baseline.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Non-Economic Damages: Pain, Suffering, and Life Impact
Non-economic damages compensate you for pain, suffering, emotional distress, and the injury’s impact on your quality of life. They’re harder to prove than economic damages because there’s no receipt. But credible, specific evidence makes them substantial.
Gather evidence of real impact:
- Personal journal entries: document daily pain levels, activity limitations, emotional struggles, sleep disruption, relationship effects, and mood changes. Write specifically—”couldn’t lift my child without pain,” “couldn’t work because of dizziness,” “pain prevented sleep”—not vague generalizations like “felt bad.”
- Photographs showing physical effects: scars, swelling, bruising, visible disability, or assistive devices (crutches, braces, wheelchairs, canes). Visual evidence is powerful.
- Communications with family or friends: text messages, emails, or letters describing your condition and struggles. These show real impact on people who know you and are harder to dispute than your own statements.
- Testimony from family, friends, or coworkers: written or recorded statements describing changes in your abilities, personality, energy level, or activity engagement since the accident.
- Records of activities you can no longer do: canceled vacation bookings, dropped hobbies, lost job opportunities, or activities your injury prevents. These show concrete life changes.
Insurance adjusters apply a multiplier to economic damages to estimate non-economic damages. The multiplier typically ranges from 1.5 to 5 times economic damages, depending on injury severity and evidence credibility. A severe, permanent injury with strong evidence of ongoing pain earns a higher multiplier. A minor injury with weak evidence earns a lower multiplier.
How Insurance Adjusters Calculate Your Claim’s Value
Insurance adjusters follow a predictable formula:
- Calculate economic damages by adding all documented medical bills, lost wages, and out-of-pocket costs.
- Apply a multiplier (typically 1.5 to 5 times economic damages) to estimate non-economic damages based on injury severity and evidence quality.
- Compare your case to similar settled cases in your jurisdiction to verify the calculated value is reasonable.
- Identify documentation gaps and use them to argue lower value. Missing medical records, unexplained treatment gaps, or contradictory statements reduce the offer.
- Consider comparative fault and reduce settlement proportionally. If you’re 30% at fault, recovery is reduced by 30%.
- Consider insurance coverage limits and adjust downward if the at-fault driver’s policy limits are lower than your calculated damages.
Strong, organized documentation increases the multiplier applied to your economic damages. It reduces gaps the defense can exploit. It increases the overall settlement offer.
Organizing Your Documentation
Organization matters. Insurance adjusters review dozens or hundreds of documents. Scattered, incomplete, or hard-to-follow records suggest carelessness or weakness.
Create a system:
- Chronological folder or digital file: organize all medical records, bills, correspondence, photographs, and evidence by date. This reveals gaps or inconsistencies.
- Keep originals and copies: do not send originals to insurance companies. Make copies and keep originals in a safe place.
- Maintain a timeline: list all treatment dates, providers, costs, and significant events. This helps you spot missing records and inconsistencies.
- Save all communications: text messages, emails, and letters related to the accident and recovery. These may support your claim.
- Be careful on social media: do not post about your injury, recovery, or settlement in ways that contradict your claim. Posts showing you having fun will be used to argue your injuries weren’t serious.
- Provide complete documentation to your attorney: do not withhold or hide records. Your attorney needs everything to evaluate your case fairly and advise you.
What Happens If Documentation Is Missing
Missing records directly reduce settlement offers. Insurance adjusters will assume the worst.
No medical records? They assume the injury wasn’t serious. No wage documentation? They assume you didn’t lose income. Treatment gap? They assume you recovered. Missing photographs? They assume the damage wasn’t severe.
Defense attorneys will argue that missing records prove your injury was minor. You may lose the opportunity to recover for losses you cannot prove.
Act quickly. Request medical records, the police report, and other documents within 30 days of the accident. Most providers provide records within 30 days. The police report is typically available within a week or two. Early action preserves your claim.
Florida’s Statute of Limitations
In Florida, you have a limited time to file a personal injury lawsuit. For most claims arising on or after March 24, 2023, the deadline is two years from the date of the accident. Earlier claims generally had a two-year deadline.
Don’t wait until the deadline approaches. Insurance negotiations take months. You need all documentation organized and ready to support your claim before settlement discussions begin.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Understanding Your Claim’s Value
Gather all documentation related to your accident and treatment. Organize it chronologically and by category. Review it to identify gaps and fill them quickly.
Do not settle with an insurance company until you understand what your claim is actually worth. Don’t accept the first offer. Insurance adjusters often start low, expecting negotiation.
If you’re unsure whether your documentation is complete, whether an offer is fair, or what your claim might be worth, contact us. We focus exclusively on personal injury claims and can review your documentation to help you understand your claim’s true value and your options.
Why Documentation Matters in Your Settlement
Insurance Adjusters Use a Formula
They add documented medical costs and lost wages, apply a multiplier for pain and suffering, then look for gaps in your evidence to justify paying less. Complete documentation means a stronger offer.
Each Document Serves a Legal Purpose
Medical records prove injury severity. Pay stubs and tax returns prove lost income. Repair estimates prove property damage. Photos prove fault. Missing any category weakens your entire claim.
Early Collection Protects Your Claim
Medical providers may discard records after a few years. Witnesses move away. Surveillance footage gets overwritten. Collecting evidence immediately after your accident preserves what you need.
Organization Prevents Costly Mistakes
A disorganized file means your attorney may miss a document that increases your value, or an adjuster may claim you never provided proof you actually did submit.
Key Documents That Prove Your Claim's Value
Medical Records & Bills
Emergency room reports, imaging (X-rays, CT scans, MRI), surgical records, physical therapy notes, and all provider invoices. These establish injury severity and calculate your economic damages.
Proof of Lost Income
Recent pay stubs, tax returns, and a letter from your employer confirming dates missed and hourly rate or salary. Self-employed? Include business records and tax filings.
Accident Scene Evidence
Photos of vehicle damage, road conditions, traffic signals, and debris. Police report number. Witness contact information. Dash-cam or surveillance video if available.
Property Damage Documentation
Repair estimates from body shops, actual repair invoices, or a total-loss valuation if the vehicle was declared a total loss. These establish the force and severity of impact.
Don't Delay—Collect Evidence Now
The longer you wait to gather medical records, repair estimates, and witness statements, the harder they become to find. Medical providers purge old files. Witnesses relocate. Video footage is overwritten. Start organizing your evidence immediately after your accident.
How Settlement Amounts Are Calculated
Economic Damages (Hard Numbers)
Medical bills, hospital stays, surgery, rehabilitation, prescription medications, medical equipment, lost wages, and transportation costs. These are documented, verifiable, and the foundation of every settlement.
Non-Economic Damages (Pain & Suffering)
Insurance companies apply a multiplier—typically 1.5 to 5 times your economic damages—to account for pain, emotional distress, lost enjoyment of life, and permanent scarring or disfigurement.
Multiplier Factors
Severity of injury, clarity of fault, your age and earning capacity, and strength of your evidence all affect the multiplier. A catastrophic injury with clear liability and solid documentation commands a higher multiplier.
Gaps Lower Your Offer
Missing medical records, no proof of lost wages, or weak documentation of fault all give the insurance company reasons to reduce their offer. Completeness is leverage.
How CHG Personal Injury Lawyers Protects Your Claim
We Organize Your Evidence
Our team collects, catalogs, and cross-references every document so nothing is overlooked and nothing gets lost in translation to the insurance company.
We Identify Missing Pieces
We know which documents adjusters scrutinize most heavily. If a critical piece of evidence is missing, we work to recover it before settlement negotiations begin.
We Handle Communication with Insurers
We present your evidence in the format and sequence that builds the strongest case, protecting you from saying something that weakens your claim.
We Explain Your Options in Plain Language
Settlement offers can be confusing. We break down what the numbers mean, what you're entitled to pursue, and whether an offer is fair given your evidence and injuries.