

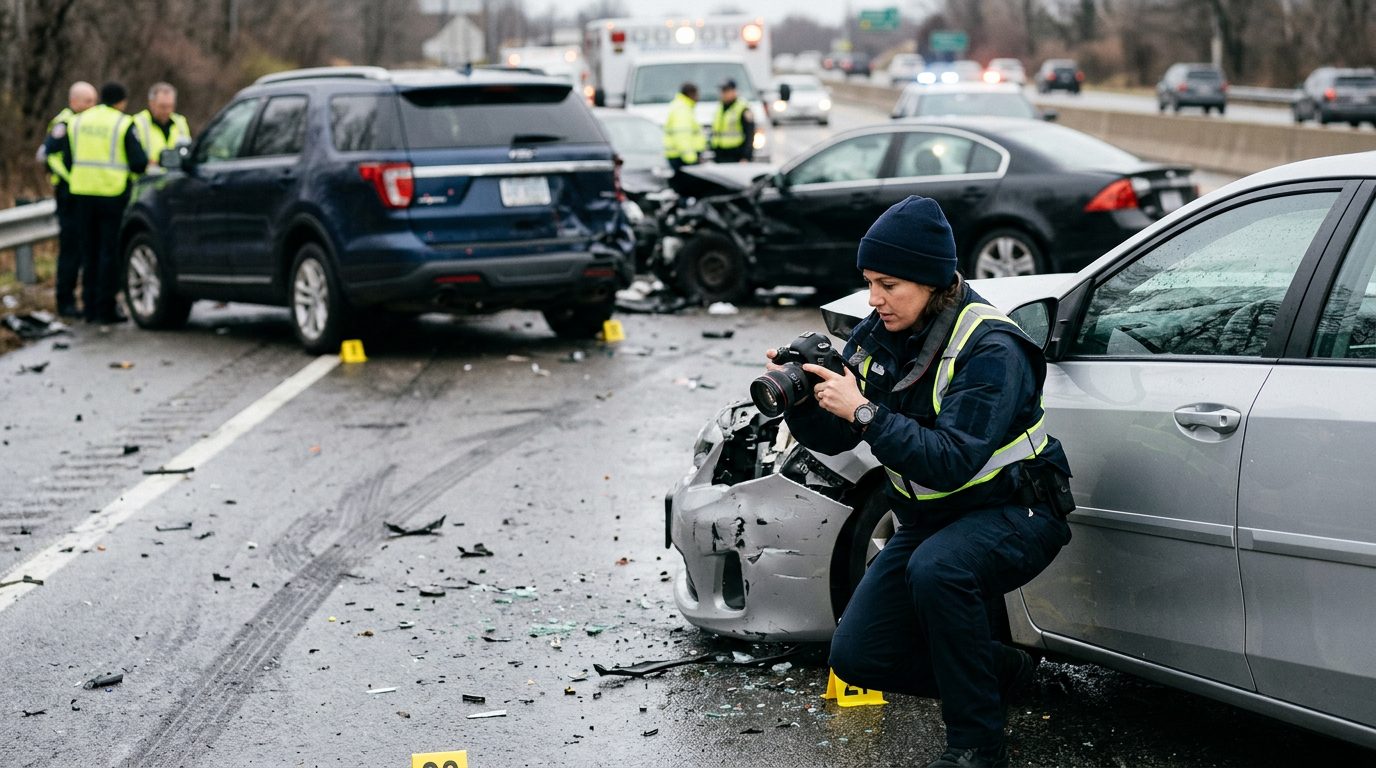
Car Accident Injury Claims
How Much Is My Car Accident Injury Worth?
Understanding the real value of your claim—from medical costs and lost wages to pain, suffering, and long-term impact.
By CHG Lawyers · Published September 28, 2026
How Much Are Lost Wages Worth in a Car Accident Claim?
When a car accident injures you, the financial harm extends far beyond medical bills. Lost wages—the income you stopped earning while recovering—are a real, documented part of your claim’s value. Understanding how lost wages are calculated helps you know what your car accident injury claim is truly worth.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Lost Wages Mean in Your Car Accident Claim
Lost wages are the income you stopped earning because of your injury and recovery time. This includes time off work for medical treatment, hospitalization, physical therapy, and healing at home. It’s separate from pain and suffering and represents a measurable financial loss.
Your injury didn’t just create medical bills—it stopped your paycheck. If you were out of work for six weeks, you lost six weeks of income. If you cut your hours because of ongoing pain or treatment appointments, you lost income from those reduced hours. That’s lost wages, and it’s recoverable in your car accident injury claim.
How Lost Wages Are Calculated
Lost wages start with your regular income before the accident. The calculation depends on how you were paid.
For salaried employees: Divide your annual salary by 250 working days per year. Multiply that by the days you couldn’t work. If you earn $50,000 yearly and missed 30 days, your lost wages equal roughly $6,000.
For hourly workers: Multiply your hourly rate by the hours you didn’t work. If you earn $25 per hour and missed 240 hours (six weeks × 40 hours), your lost wages equal $6,000.
For self-employed or commission-based workers: Use your tax returns from the past two to three years. Find your average daily or monthly earnings. Multiply that average by the days or weeks you couldn’t work. Business records, invoices, and bank statements support this calculation.
The time you count includes full days missed from work, plus time spent in medical appointments, physical therapy, and recovery at home. If you left work early three days a week for six weeks to attend therapy, that time counts toward your lost wages.
Documentation You’ll Need to Prove Lost Wages
Insurance companies won’t accept your word for lost wages. You need solid evidence.
Gather pay stubs from before and after the accident showing the income gap. Ask your employer for a letter confirming your absence dates and your regular hourly rate or salary. Provide tax returns from the past two to three years to establish your baseline income—especially important if you’re self-employed or commission-based.
Medical records matter too. Your treatment dates and recovery timeline show when and why you couldn’t work. If you used sick leave or paid time off (PTO) for recovery, provide those records. For self-employed individuals, submit profit-and-loss statements, invoices, or business bank statements showing your average income before the accident.
The more documentation you have, the harder it is for an insurance adjuster to dispute your lost wages.
Lost Earning Capacity: When Your Injury Affects Future Income
Lost earning capacity differs from lost wages, though they’re often confused. Lost earning capacity applies when your injury permanently or long-term reduces your ability to work or earn at your pre-accident level.
Imagine you were a carpenter earning $60,000 yearly. A back injury leaves you unable to do physical labor. You can work, but only in a desk job paying $35,000 yearly. The difference—$25,000 per year—is lost earning capacity. At age 30, that loss could span decades.
Lost earning capacity requires medical evidence that your injury limits your future work ability. An orthopedic surgeon might testify that your back injury is permanent and prevents heavy lifting. A vocational expert (a professional who evaluates work capacity) can then calculate how much less you’ll earn over your working lifetime.
This differs from lost wages—it’s the future income you’ll never earn because of your injury.
Is $50,000 a Good Settlement for a Car Accident?
There is no universal “good” settlement amount. A $50,000 settlement might be excellent for a minor injury with low medical costs and short recovery. The same amount might be inadequate for a serious injury with ongoing treatment and permanent disability.
Your settlement should cover all documented losses: medical bills, lost wages, lost earning capacity, and compensation for pain and suffering. Liability strength (who was at fault), injury severity, and insurance policy limits all affect your claim’s value.
A $50,000 settlement might be appropriate if your total economic damages are $30,000 and your injury caused moderate pain for a few months. It might be far too low if your economic damages are $80,000 and your injury is permanent.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
How Much of a Settlement Will You Actually Receive?
The gross settlement number isn’t what you take home. Several deductions reduce your net payment.
If you hired an attorney on contingency (you don’t pay unless you win or settle), they typically take 25 to 40 percent of the settlement. Medical providers or your health insurance may have a lien on your settlement—a legal claim to recover what they paid for your care. Case costs (expert witnesses, court filing fees, medical records requests) are deducted before you receive your share.
Here’s an example: a $100,000 settlement minus $30,000 in attorney fees, $15,000 in medical liens, and $5,000 in case costs leaves you $50,000. Your attorney should explain all deductions clearly before you accept any settlement offer.
What Injury Pays the Most in a Car Accident Claim?
Severity and permanence drive claim value. Catastrophic injuries—spinal cord injuries, paralysis, traumatic brain injuries, and amputations—typically result in higher settlements. Lost earning capacity is often substantial and lifelong.
Permanent disability or disfigurement increases value. A younger person with a permanent injury has more years of lost earning potential ahead. A 35-year-old with a spinal cord injury faces decades of reduced earning capacity; a 65-year-old faces fewer working years.
Medical costs and ongoing care needs matter too. Injuries requiring lifelong treatment, assistive devices, home modifications, or personal care increase claim value. Even injuries labeled “minor” can have significant value if they cause lasting pain, limited mobility, or prevent you from working in your field.
Multiple injuries compound the value: a broken leg plus a head injury is worth more than either alone.
Economic Damages vs. Non-Economic Damages
Economic damages are measurable financial losses: medical bills, lost wages, lost earning capacity, property damage, and transportation costs. They have a clear dollar amount.
Non-economic damages cover pain and suffering, emotional distress, loss of enjoyment of life, and permanent scarring or disfigurement. They don’t have an obvious price tag.
Lost wages are economic damages—they have a clear dollar amount based on your actual income. Many settlements use a “multiplier” method to estimate non-economic damages: economic damages × 1.5 to 5 (or more for severe injuries). If you have $50,000 in medical bills and lost wages, that might support $75,000 to $250,000 in pain and suffering, depending on injury severity. See our guide to understanding pain and suffering damages for more detail.
Comparative Negligence: How Fault Affects Your Lost Wages Claim
In Florida, if you are partially at fault for the accident, your settlement is reduced by your percentage of fault under modified comparative negligence (Fla. Stat. §768.81(6)). If you are found more than 50 percent at fault, you generally cannot recover anything.
Example: if you are 20 percent at fault and your total claim is $100,000, you recover $80,000. Lost wages are part of your total claim value and are reduced by your fault percentage.
The other driver’s insurance will investigate to assign fault. Your attorney will defend your position and push back on inflated fault assignments. Even if you are partially at fault, you can still recover lost wages and other damages—you just recover a reduced amount.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
Why You Should Talk to a Lawyer About Your Lost Wages
Insurance adjusters often undervalue lost wages by using incomplete income records or disputing the time you needed to recover. They might argue you could have worked from home or that you didn’t really need all the physical therapy you received.
An attorney can gather proper documentation and push back on lowball offers. If your injury affects your long-term earning ability, a lawyer can work with vocational experts to calculate future lost income. Many people settle too quickly without accounting for all their losses. A lawyer ensures nothing is missed. Learn more about when to hire a car accident attorney and what to expect.
In the catastrophic-injury cases we handle, lost earning capacity often dwarfs the immediate lost wages. A spinal cord injury victim might lose a few months of wages during recovery, but then face decades of reduced earning potential. That future loss needs proper valuation and expert support.
You don’t pay unless you recover. Most car accident attorneys work on contingency, so there’s no upfront cost to get professional help.
Next Steps: Understanding Your Claim’s Value
Start by gathering documentation: pay stubs, employer letters, medical records, and proof of time off work. Calculate your lost wages by multiplying your hourly rate or daily salary by the days or hours you couldn’t work. Learn how to document medical expenses to support your claim.
Consider whether your injury will affect your earning ability long-term. Do not accept an early settlement offer without understanding what your claim includes—lost wages, medical bills, and pain and suffering are all separate components that add up to your total value. For a broader overview, see our car accident settlement guide.
If you’ve lost income due to a car accident injury and aren’t sure what that loss means for your claim, contact us to discuss your specific situation. People in your position can reach out, and we can help you understand what your lost wages and other damages might be worth.
What Goes Into Your Claim's Value
Economic Damages
Medical bills, emergency care, surgery, hospitalization, physical therapy, medications, medical equipment, and ongoing treatment. Also: lost wages during recovery, lost earning capacity if your injury is permanent, and costs to modify your home or vehicle.
Non-Economic Damages
Pain and suffering, emotional distress, loss of enjoyment of life, scarring or disfigurement, and the impact on your relationships and daily activities. These are harder to quantify but are real parts of your injury's cost.
Lost Wages & Income
Income you stopped earning while recovering—time off for medical treatment, hospitalization, and rehabilitation. If your injury is permanent and affects your ability to work, lost earning capacity over your lifetime is also part of your claim.
Permanent Injury & Disability
If your injury causes lasting impairment—chronic pain, reduced mobility, cognitive changes, or permanent disability—the long-term cost of care, adaptive equipment, home modifications, and reduced quality of life significantly increases your claim's value.
Don't Accept the First Offer
Insurance companies often offer quick settlements that are far below what your claim is actually worth. They count on injured people accepting fast payouts without understanding the full scope of their damages—especially long-term medical costs and lost income. A thorough evaluation of your injury and its impact is essential.
How We Help You Understand Your Claim's Value
Detailed Damage Calculation
We gather all medical records, bills, wage statements, and evidence of your injury's impact. We work with medical professionals and economists to calculate both current and future costs—not just what you've already spent, but what your recovery and long-term care will cost.
Accountability for the Full Picture
We don't let insurance companies narrow your claim to just medical bills. We document pain, suffering, lost time, permanent changes to your life, and the real financial impact of your injury—and we fight to ensure all of it is valued fairly.
Plain-Language Explanation
We explain how your claim is valued, what each part means, and why the number we're seeking is justified. You'll understand exactly what you're asking for and why—no legal jargon, no surprises.
Experience With Serious Injuries
Our practice focuses exclusively on catastrophic and serious personal injuries. We understand how spinal cord injuries, traumatic brain injuries, amputations, severe burns, and permanent disabilities affect lifetime earnings, medical needs, and quality of life—and we know how to value them.
Key Factors That Affect Your Claim's Value
Severity of Your Injury
Minor injuries (sprains, cuts, short recovery) have lower value. Serious injuries (fractures, head trauma, spinal cord damage, permanent disability) have significantly higher value because of ongoing medical needs and lasting impact.
Your Age & Earning History
Younger people with long work lives ahead may have higher lost earning capacity. Your pre-injury income and career trajectory matter. Someone earning $60,000 annually who cannot return to work has a different claim value than someone earning $150,000.
Permanence of the Injury
Temporary injuries heal. Permanent injuries—chronic pain, reduced mobility, cognitive changes, paralysis, or amputation—multiply your claim's value because they affect your entire life, not just your recovery period.
Clear Liability & Fault
If the other driver is clearly at fault, your claim is stronger and easier to settle. If liability is disputed or shared, your claim's value may be reduced or harder to recover. Evidence of negligence matters.