

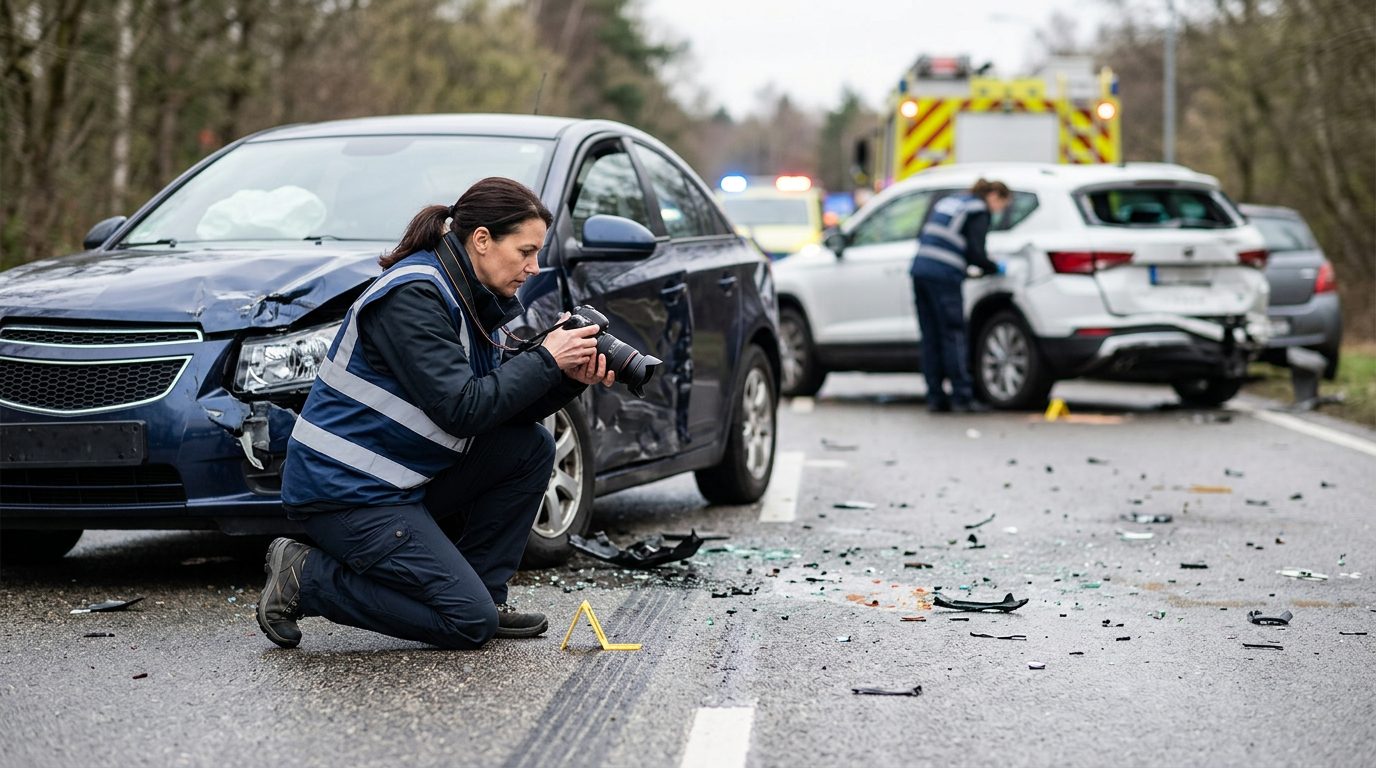
Car Accident Claims
Car Accident Settlement: Recovering Medical Bills & Lost Wages
After a crash, medical expenses and lost income pile up fast. Learn what damages you can recover and how to document your claim.
By CHG Lawyers · Published September 25, 2026
Medical Expenses and Lost Wages in Car Accident Settlements
There’s no single “minimum settlement” for a car accident. What you recover depends on three things: how serious your injuries are, how clear the fault is, and what insurance coverage exists.
Your settlement typically includes two broad categories: – Economic damages: documented costs like medical bills and lost income. – Non-economic damages: pain, suffering, and lost quality of life.
Understanding how these fit together helps you see why some car accident claims are worth far more than others, and what you’ll need to prove.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Are Economic Damages in a Car Accident?
Economic damages are the measurable, out-of-pocket costs caused by the accident. They include:
- Medical expenses: emergency care, surgery, hospitalization, rehabilitation, ongoing treatment, medications, assistive devices (wheelchairs, braces, home modifications), and future medical care.
- Lost wages: income you didn’t earn because you couldn’t work during recovery.
- Lost earning capacity: if your injuries are permanent, the difference between what you would have earned and what you can earn now.
These are called “economic” because they have receipts, invoices, pay stubs, and tax returns to back them up. They’re straightforward to calculate—though proving them thoroughly is critical.
How Medical Expenses Are Calculated in Settlements
Your medical expenses include every documented cost related to the accident injury. This covers everything from the ambulance ride to years of ongoing care.
In catastrophic injury cases—spinal cord injuries, traumatic brain injuries, amputations—lifetime medical costs can be enormous. For example, according to the National Spinal Cord Injury Statistical Center, a spinal cord injury averages $1.1 million in first-year medical costs alone. Ongoing annual costs run approximately $184,000 per year. These figures reflect the reality of permanent disability: ongoing therapy, equipment replacement, home care, and complications that arise over a lifetime.
In the catastrophic-injury cases we handle, we work with medical experts and life-care planners. We document every expense—past and future—so nothing is overlooked. Your settlement should account for:
- Past medical bills (already paid or owed).
- Future medical care (surgery, therapy, medications, equipment).
- Home modifications and assistive technology.
- Nursing or personal-care services if your injury requires ongoing help.
Insurance adjusters will scrutinize these claims carefully. Every bill, receipt, and expert recommendation needs to be documented and justified.
How Lost Wages and Earning Capacity Are Proven
Lost-wage claims require clear proof of your income before the accident and the income you’ve lost since.
To prove past lost wages, you’ll need:
- Pay stubs or tax returns showing your pre-accident income.
- Employer statements confirming the dates you were unable to work.
- Medical records showing when you were medically unable to work.
If your injury causes permanent disability—you can’t return to your old job or earn at your pre-accident level—you may also recover lost earning capacity. An economist or vocational expert testifies about what you would have earned over your remaining working years had the accident not occurred, minus what you can realistically earn now.
For example, if you were a construction worker earning $60,000 a year and a spinal cord injury leaves you unable to work in that field, an expert might calculate that you’ve lost $1.2 million in earning capacity over 30 years. That’s a separate damage from your past lost wages, and it can be substantial in catastrophic cases.
Non-Economic Damages: Pain, Suffering, and Loss of Life Quality
Beyond medical bills and lost income, Florida law allows you to recover for intangible harms: pain and suffering, emotional distress, loss of enjoyment of life, and permanent scarring or disfigurement.
Unlike economic damages, non-economic damages don’t have receipts. Instead, they’re argued based on how severe and permanent your injury is. A broken arm that heals in six weeks generates far less pain-and-suffering damages than a spinal cord injury that leaves you paralyzed for life.
Florida law places no statutory cap on non-economic damages in personal-injury cases (unlike some states). The amount awarded depends on the facts of your case and how well your attorney presents the impact of the injury on your daily life.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
How Comparative Fault Affects Your Settlement
Florida uses a modified comparative-fault rule. Under Fla. Stat. §768.81(6), if you’re found to be more than 50% at fault for the accident, you recover nothing. If you’re 50% or less at fault, your damages are reduced by your percentage of fault.
For example, if your total damages are $100,000 but you’re found 20% at fault, you recover $80,000.
Fault determination is critical. Even when liability seems clear, the other party’s insurance company will argue you share some blame. We investigate thoroughly to establish clear liability and minimize any comparative-fault findings.
Insurance Policy Limits: The Cap on Your Settlement
Here’s a hard reality: your settlement can’t exceed the defendant’s insurance policy limits, no matter how severe your injuries are. The policy limit caps what the insurer pays, not what the at-fault party owes; your own UM/UIM coverage may add to the recovery.
If the at-fault driver has $25,000 in liability coverage and your damages total $500,000, you’ll recover the $25,000 policy limit (unless the defendant has personal assets you can pursue, which is rare and difficult). This is why cases involving commercial vehicles—trucks, rideshare cars, delivery vans—often yield larger settlements: they typically carry higher insurance limits.
In catastrophic cases, policy limits are often insufficient. This is where underinsured motorist (UIM) coverage on your own policy becomes critical—it can fill the gap between the at-fault driver’s policy limit and your actual damages.
The Two-Year Deadline in Florida
Florida law is strict about timing. Under Fla. Stat. §95.11(5)(a), you must file a negligence claim within two years from the date of the accident, or your claim is barred forever. There are no exceptions for catastrophic injuries or for claimants who didn’t realize the full extent of their harm until later.
This deadline applies to all car accident claims in Florida, regardless of injury severity. Missing it means you lose your right to recover entirely.
Why Documentation Matters
The difference between a strong settlement and a weak one often comes down to documentation. Insurance companies will challenge every expense and every lost-wage claim. The more thorough your records, the harder it is for them to deny or minimize your damages.
Keep:
- All medical records and bills.
- Receipts for out-of-pocket expenses (medications, equipment, travel to appointments).
- Pay stubs and tax returns.
- Employer statements about time off work.
- Photos of injuries and any permanent scarring or disability.
- Journal entries documenting pain, limitations, and emotional impact.
In catastrophic cases, we also retain life-care planners and vocational experts. They provide detailed, expert-backed projections of future costs and lost earning capacity.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
Frequently Asked Questions
What’s the average car accident settlement in Florida?
There’s no average—settlements range from a few thousand dollars for minor injuries to millions for catastrophic, permanent injuries. Your settlement depends on injury severity, clarity of fault, available insurance, and how well damages are documented.
Can I recover future medical expenses?
Yes. If your injury requires ongoing or lifetime care, your settlement should include a calculation of future medical costs. Life-care planners help establish these figures.
What if I was partially at fault?
Under Florida’s comparative-fault rule, you can still recover if you’re 50% or less at fault—but your damages are reduced by your percentage of fault (Fla. Stat. § 768.81(6)).
How long do I have to file a claim?
You have two years from the date of the accident to file a negligence claim in Florida (Fla. Stat. § 95.11(5)(a)). After that, your claim is permanently barred.
What if the insurance policy limit is too low?
Your own underinsured motorist coverage may cover the gap. An attorney can help you pursue all available sources of recovery.
If you’re dealing with medical bills, lost income, or long-term care costs from a car accident—whether the injury is straightforward or catastrophic—understanding what damages you can recover is the first step. People in your situation reach out regularly to understand whether they have a claim and what it might be worth. Contact us for a free case evaluation to discuss your specific accident and injuries.
What We Handle in Car Accident Claims
Medical Bills & Future Care
Past and ongoing treatment costs, surgery, rehabilitation, prescription medications, and medical equipment—all recoverable if the other driver was at fault.
Lost Wages & Earning Capacity
Income you missed while recovering, and if your injury is permanent, reduced future earning power can be part of your settlement.
Pain, Suffering & Permanent Injury
Compensation for physical pain, emotional distress, scarring, disability, and loss of enjoyment of life—especially in catastrophic cases.
Property Damage & Other Losses
Vehicle repair or replacement, rental car costs, and other out-of-pocket expenses directly caused by the crash.
Steps to Strengthen Your Settlement Claim
Document Everything
Keep all medical records, bills, receipts, pay stubs, and proof of lost time from work. Photos of vehicle damage and the crash scene also matter. The more evidence you have, the stronger your claim.
Report the Crash Promptly
File a police report and notify the at-fault driver's insurance company. Get the other driver's contact and insurance information at the scene, and write down witness names and phone numbers.
Seek Medical Attention Right Away
Some injuries appear days or weeks after a crash. Medical records create a clear link between the accident and your injuries—critical for your claim.
Avoid Settling Too Quickly
Insurance adjusters often offer fast, low settlements before you know the full extent of your injuries or costs. An attorney can help you understand what your claim is truly worth.
Don't Overlook Future Damages
If your injury is permanent or long-term, you can recover not just today's medical bills but also projected future treatment, ongoing therapy, home modifications, and lost earning potential over your lifetime. These calculations are complex—getting them right makes a huge difference.
Common Questions About Car Accident Settlements
What if I was partially at fault?
Florida law allows you to recover damages even if you share some responsibility—as long as you were not more than 50% at fault (Fla. Stat. § 768.81(6)). Your recovery is reduced by your percentage of fault.
How long does a settlement take?
Simple claims may settle in weeks or months. Complex or catastrophic injury cases often take longer as medical treatment continues and damages are fully documented. An attorney can guide you through the timeline.
What if the other driver has no insurance?
You may be able to claim through your own uninsured motorist coverage. An attorney can help you navigate this option and pursue other avenues for recovery.
Do I need an attorney?
For minor injuries, you may handle a claim alone.