

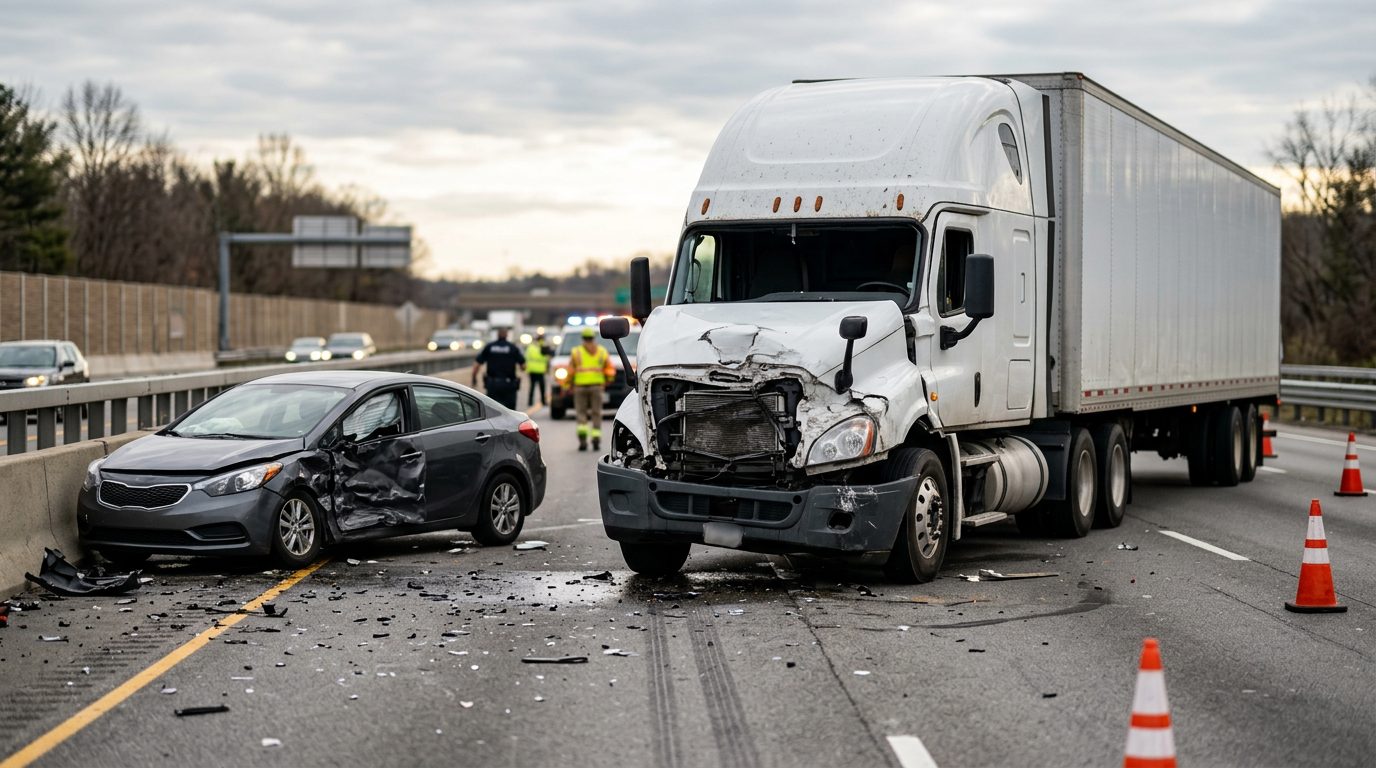
Car Accident Claims
What Is a Fair Settlement for a Non-Injury Car Accident?
Understanding property damage claims and how compensation is calculated when no one is hurt.
By CHG Lawyers · Published September 23, 2026
Uninsured & Underinsured Motorist Coverage in Florida: UM/UIM Protection Explained
Another driver hits you. They have no insurance—or their coverage isn’t enough. Your medical bills, repairs, and lost wages don’t disappear. That’s where your own uninsured motorist (UM) and underinsured motorist (UIM) coverage steps in to protect you.
This page explains how UM and UIM coverage works in Florida. We’ll cover what each does, how settlements work, and how to protect yourself.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Happens When an Uninsured or Underinsured Driver Hits You
When the at-fault driver has no insurance or not enough coverage, a gap opens. Your losses don’t match what you can recover from them. Your own insurance may include UM or UIM coverage—a safety net most drivers don’t understand until they need it.
Without UM/UIM coverage, you’d have to sue the uninsured driver personally. That often fails because they have no money or assets. With UM/UIM coverage, your own insurer pays your damages up to your policy limits.
Review your coverage before an accident. Most drivers don’t.
Understanding Uninsured Motorist (UM) Coverage
Uninsured motorist coverage may apply when the at-fault driver has no insurance or is underinsured. UM covers damages for bodily injury, such as medical bills, lost wages, and pain and suffering.
In Florida, UM coverage is available and common. Your UM limit—the most your insurer will pay—directly affects what you recover. If your UM limit is $25,000 and your damages total $50,000, you get up to $25,000 from your own policy.
Many drivers carry low UM limits without realizing they’re underprotected. A higher UM limit costs little more but helps a lot in serious accidents.
Understanding Underinsured Motorist (UIM) Coverage
Underinsured motorist coverage fills the gap when the at-fault driver has insurance but not enough to cover your full losses.
Example: The at-fault driver has a $25,000 liability limit. Your damages total $75,000. Your UIM coverage pays the difference—up to your UIM limit—so you recover closer to your actual losses.
UIM coverage is separate from UM and equally important. In Florida, you can often “stack” UIM coverage across multiple vehicles on your policy. This increases the total available to you. Stacking rules vary by policy and insurer, so check your declarations page.
Many drivers don’t realize they have UIM coverage or how it works. This gap costs people thousands in unrecovered damages.
How Car Accident Settlements Are Calculated
Settlements combine two types of damages: economic and non-economic.
Economic damages are costs you can prove with receipts: repair estimates, medical bills, rental car costs, and lost wages. These form the foundation of most settlements.
Non-economic damages include pain and suffering and emotional distress. They’re harder to measure but often included, especially with injuries. In property-damage-only accidents, non-economic damages are usually small.
Liability is the third piece. Insurance adjusters decide who was at fault and how clear the evidence is. Clear liability leads to faster, higher settlements. Disputed liability can lower offers because the insurer is less certain they’ll be held responsible.
Important: Insurance adjusters work for the insurance company, not for you. Their first offer is rarely their best.
Average Settlement for Non-Injury Car Accidents in Florida
For car accidents without injuries in Florida, settlements typically range from $3,000 to $15,000, depending on repair costs and how clear liability is. These cover vehicle damage—the cost to repair or replace your car—plus rental car fees and other expenses.
Several factors push settlements higher or lower:
- Repair costs: A $12,000 repair bill settles higher than a $2,000 one.
- Vehicle age and value: Older vehicles may settle for less due to depreciation.
- Liability clarity: If the other driver is clearly at fault (rear-end collision, red light run), settlements tend to be higher.
- Insurance limits: If the at-fault driver’s policy limit is $10,000 and your damages are $15,000, their insurer pays no more than $10,000.
The word “average” is misleading. Every accident is different. Your actual settlement depends on your specific damages, the evidence of fault, and your coverage limits.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
What Is a Reasonable Amount to Ask for Pain and Suffering?
In non-injury accidents, pain and suffering claims are often small or zero if there are no medical injuries.
Insurance companies often calculate non-economic damages using a multiplier: 1 to 3 times the economic damages for minor accidents.
Documentation strengthens your claim. Photos of damage, repair estimates, rental car receipts, a timeline of events, and records of time spent on the claim all support your position. If the accident caused genuine stress, document it: notes about sleep loss, missed work, or stress symptoms help justify a pain-and-suffering award.
How Much Compensation for Anxiety After a Car Accident?
Insurance companies scrutinize these claims carefully because they’re subjective.
To strengthen an anxiety claim, document your experience: therapy or counseling records, medical notes from your doctor, testimony about how the accident affected your sleep, work, or daily life. The more concrete the evidence, the more credible your claim.
Compensation for anxiety alone in a non-injury accident typically ranges from $1,000 to $5,000. If anxiety combines with physical injuries, the total can be higher. The key is showing a clear link between the accident and your emotional symptoms.
Florida’s Two-Year Filing Deadline: Don’t Miss It
Under current Florida law, if your car accident injury claim arose on or after March 24, 2023, you have two years from the date of the accident to file a lawsuit. Claims that arose before that date generally had four years.
This deadline is absolute. Missing it bars your claim forever, no matter how strong it is. As it approaches, settlement negotiations become more urgent—the insurer knows you can sue, but they also know your window is closing.
Modified Comparative Fault in Florida
Florida follows a modified comparative fault rule. Under Florida Statute § 768.81, if you’re found more than 50% at fault, you recover nothing. If you’re 50% or less at fault, your damages are reduced by your percentage of fault.
Example: If you’re 30% at fault and your damages are $10,000, you recover $7,000.
This rule affects settlement negotiations. If liability is disputed, the insurer may offer less because they believe a jury might find you partially at fault.
Steps to Protect Yourself and Maximize Your Settlement
Before an accident happens:
- Review your insurance policy and know your UM and UIM limits.
- If limits are low, consider raising them—the cost is modest.
- Understand the difference between UM and UIM coverage.
At the accident scene:
- Take photos of all vehicle damage, the scene, and the other driver’s vehicle.
- Get the other driver’s name, phone number, address, driver’s license number, license plate, and insurance information.
- Get contact information from any witnesses.
- Call police and get a report number.
After the accident:
- Report the claim to your insurer promptly with complete, accurate information.
- Get written repair estimates from at least one reputable shop.
- Keep receipts for all expenses: rental car, transportation, medical care.
- If you have injuries, seek medical attention and keep all treatment records.
- Do not accept the first settlement offer without understanding your entitlements.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
When to Reach Out for Help With Your Claim
Several situations warrant a conversation with someone who can review your claim:
- The at-fault driver is uninsured or underinsured, and you’re unsure how your UM/UIM coverage works.
- The insurance company is delaying, denying, or offering an amount you believe is too low.
- You’re not sure whether you’re being treated fairly or whether you’ve documented all damages.
- You have questions about coverage limits or whether you can recover more than the at-fault driver’s policy limit.
- Your accident occurred more than a year ago, and you haven’t resolved your claim.
Many people want to understand their options before deciding how to proceed. A legal review can clarify your coverage, identify missed damages, and help you understand whether an offer is reasonable. That clarity alone often helps people negotiate better settlements.
Frequently Asked Questions
What’s the difference between UM and UIM coverage?
UM covers you when the at-fault driver has zero insurance. UIM covers you when they have insurance but it’s not enough to pay your full damages.
How long do I have to file a car accident claim in Florida?
For injury claims that arose on or after March 24, 2023, you have two years from the date of the accident to file a lawsuit.
Can I recover more than my UM/UIM limits?
Your UM/UIM limits cap what your own insurer will pay. You can pursue the at-fault driver or their insurer for any damages beyond your limits, but recovery is often difficult if they’re uninsured or have low limits.
What if I’m partially at fault for the accident?
Florida follows modified comparative fault: if you’re found more than 50% at fault, you generally recover nothing. If you’re 50% or less at fault, your damages are reduced by your share of fault (Fla. Stat. § 768.81(6)).
Should I accept the first settlement offer?
Rarely. The first offer is usually lower than what you’re entitled to. Understand your damages and your coverage limits before responding to any offer.
If you’ve been hit by an uninsured or underinsured driver and you’re unsure whether your claim is being handled fairly—or if the two-year deadline is approaching—reach out to CHG Personal Injury Lawyers. People in your situation can contact us to understand their coverage, review settlement offers, and explore their options.
Get a free case evaluation and talk through what comes next. You can also learn more about the Florida car accident claim process and how to document vehicle damage to strengthen your claim.
What Affects Your Settlement Amount
Vehicle Damage
The cost to repair or replace your car is the primary factor. Insurers use repair estimates and market value assessments to determine this amount.
At-Fault Driver's Insurance Limits
Your recovery is capped by the other driver's liability coverage. If their policy limit is low, your settlement may be reduced even if damage exceeds that limit.
Your Own Coverage
Collision coverage on your policy can help bridge gaps. Uninsured or underinsured motorist coverage may apply if the at-fault driver lacks sufficient insurance.
Local Repair Costs
Labor rates and parts availability vary by region. Florida repair shops may charge differently than shops in other states, affecting your estimate.
How CHG Personal Injury Lawyers Can Help
Damage Assessment
We review repair estimates and ensure all damage is documented and accounted for in your claim.
Insurance Negotiation
Timely Filing
We know Florida's deadlines and ensure your claim is filed correctly and within required timeframes.
Clear Guidance
We explain your coverage options, settlement offers, and next steps in plain language so you understand your position.
Don't Accept the First Offer
Insurance companies sometimes offer less than fair value for property damage. Having an attorney review the offer can help ensure you're compensated appropriately for the full cost of repairs or replacement.