

Car Accident Damages in Florida
How Much Can You Recover After a Car Accident in Florida?
Understanding the damages you may be entitled to claim—and how to pursue fair compensation.
By CHG Lawyers · Published September 25, 2026
How Much Can You Sue for a Car Accident in Florida? UM/UIM Coverage Explained
When another driver injures you in a car accident, your recovery depends on two things: their insurance limits and your own uninsured/underinsured motorist coverage.
In Florida, many drivers carry minimal or no liability insurance. Your UM/UIM coverage often determines whether you recover fairly or face a gap between your damages and what you can actually collect.
This guide explains how UM/UIM coverage works, what damages you can recover, typical settlement ranges, and why this protection matters.
If you believe they've unreasonably denied or undervalued your claim, you may have grounds for a bad-faith claim. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Is Uninsured and Underinsured Motorist Coverage?
Uninsured motorist (UM) coverage protects you when the at-fault driver has no liability insurance.
Underinsured motorist (UIM) coverage applies when their insurance limit is too low to cover your full damages.
Many drivers carry only minimum limits. When you’re hit by an uninsured or underinsured driver, your own UM/UIM coverage fills the gap.
Your insurance company pays your damages (up to your policy limit) instead of leaving you to chase an uninsured driver with no assets.
Both UM and UIM are optional coverages you choose when buying or renewing your auto policy. Both are typically inexpensive relative to the protection they provide.
What Damages Can You Recover in a Car Accident Claim?
Your recovery includes two main categories: economic and non-economic damages.
Economic damages are your actual out-of-pocket losses: – Medical expenses (emergency care, surgery, physical therapy, medications) – Lost wages – Vehicle repair or replacement – Rental car costs – Future medical care or rehabilitation
Non-economic damages compensate for: – Pain and suffering – Emotional distress – Loss of enjoyment of life – Scarring or permanent disfigurement – Loss of consortium (loss of companionship from a family member)
These have no fixed formula. Insurance companies and juries consider injury severity, recovery duration, and how the injury affects your daily life.
Punitive damages are rare in car accidents. They apply only when the at-fault driver’s conduct was reckless or intentional—not ordinary negligence.
The Critical Limit: The At-Fault Driver’s Insurance
If the at-fault driver carries only $25,000 in bodily injury liability but your damages total $75,000, their insurance pays only $25,000.
Without UM/UIM coverage, you’d pursue a lawsuit against them personally. This is difficult and often unsuccessful.
With UIM coverage on your own policy, your insurer bridges the gap, up to your chosen limit.
How Much Are Most Car Accident Settlements?
Settlement amounts vary widely based on injury severity, medical expenses, lost income, and liability clarity.
Here’s a realistic range:
- Minor injuries (soft tissue, sprains, minor cuts): $5,000–$25,000
- Moderate injuries (fractures, significant medical treatment, weeks of recovery): $25,000–$100,000
- Severe injuries (permanent impairment, long-term care, catastrophic disability): often exceed policy limits
In catastrophic-injury cases—spinal cord injuries, traumatic brain injuries, amputations, and severe burns—damages routinely exceed the at-fault driver’s policy limits. Without adequate UM/UIM coverage, families face a shortfall that devastates their ability to pay for lifelong care.
How Comparative Negligence Affects Your Settlement
Florida’s modified comparative negligence rule also affects your settlement. If you are found partially at fault, your recovery is reduced by your percentage of fault.
Example: If you are 20% at fault and your damages are $100,000, your recovery drops to $80,000. The same reduction applies to UM/UIM settlements.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Understanding Your UM/UIM Policy Limits
When you purchase or renew your auto policy, you choose your UM/UIM limits. Common options include $10,000, $25,000, $50,000, $100,000, or higher.
Your limits should reflect your actual risk. If you carry $100,000 in liability coverage but only $10,000 in UIM coverage, you’re underprotected.
Many people choose UM/UIM limits equal to or higher than their liability limits. The cost difference is usually minimal—often just a few dollars per month.
Stacking UM/UIM Limits
Some policies allow stacking. This means combining UM/UIM limits across multiple vehicles or policies. If you have two vehicles each with $50,000 UIM coverage, you might stack them for $100,000 total coverage.
Check your policy and consult an attorney to understand what’s available to you.
When Does UM/UIM Coverage Apply?
UM/UIM coverage applies in several scenarios:
Uninsured driver: The at-fault driver has no liability insurance.
Underinsured driver: Their liability limit is lower than your damages.
Hit-and-run: If the other driver flees and is not identified, your UM coverage may apply. You’ll need to file a police report and meet your insurer’s requirements.
Uninsured motorist property damage (UMPD): This coverage is not part of Florida’s uninsured motorist coverage, which applies to bodily injury, sickness, or disease, including death.
Important: UM/UIM does not cover your own negligence. It applies only when another driver is at fault.
How Hard Is It to Win a Car Accident Lawsuit Against an Uninsured Driver?
Proving the other driver was at fault is the same whether they are insured or uninsured.
But here’s the catch: even if you win a judgment, collecting from an uninsured driver is nearly impossible. They may have no income, bank account, or assets to seize.
This is why UM/UIM coverage is so valuable. Instead of pursuing a lawsuit and fighting to collect, you file a claim with your own insurance company. They have the resources and obligation to pay.
Most UM/UIM claims are resolved through negotiation with your insurer, not a lawsuit.
Good Faith Requirements
Florida law requires your insurance company to act in good faith when handling your UM/UIM claim. If they unreasonably deny or undervalue your claim, you may have grounds for a bad-faith claim against them.
Economic and Non-Economic Damages in UM/UIM Claims
Your UM/UIM coverage applies to both economic and non-economic damages combined, up to your policy limit.
Economic damages are straightforward: – Medical bills, emergency care, surgery, physical therapy, prescriptions – Lost wages – Vehicle repair – Rental car costs – Future medical care
These are supported by receipts, invoices, and wage statements.
Non-economic damages require more explanation. Pain and suffering, emotional distress, loss of enjoyment of life, and scarring or disfigurement are real losses. But they don’t come with a price tag.
Insurance companies and juries calculate them based on: – Severity of injury – Duration of recovery – Impact on your life
In severe cases, expert testimony from a life care planner—who projects future medical and care costs—can support higher valuations.
Documentation Matters
Medical records, wage statements, repair estimates, and expert testimony all strengthen your claim and justify a higher settlement.
How Much of a Settlement Will You Actually Receive?
Your gross settlement is the total amount. Your net is what you actually receive after deductions.
Deductions typically include:
- Medical liens: Healthcare providers’ claims for payment from your settlement
- Attorney fees: Usually 33–40% of recovery in contingency cases
- Court costs: Filing fees and other case expenses
- Subrogation claims: Your insurance company’s right to recover what it paid for your medical treatment
Example: A $50,000 UM/UIM settlement might result in $15,000–$20,000 in deductions, leaving you $30,000–$35,000.
An experienced attorney can often negotiate medical liens and other claims to maximize your net recovery. Always ask for a detailed breakdown of deductions before you sign any settlement agreement.
What to Do If You Are Hit by an Uninsured or Underinsured Driver
Immediate Steps
- Call police and seek medical attention, even if you feel fine. Some injuries appear hours or days later.
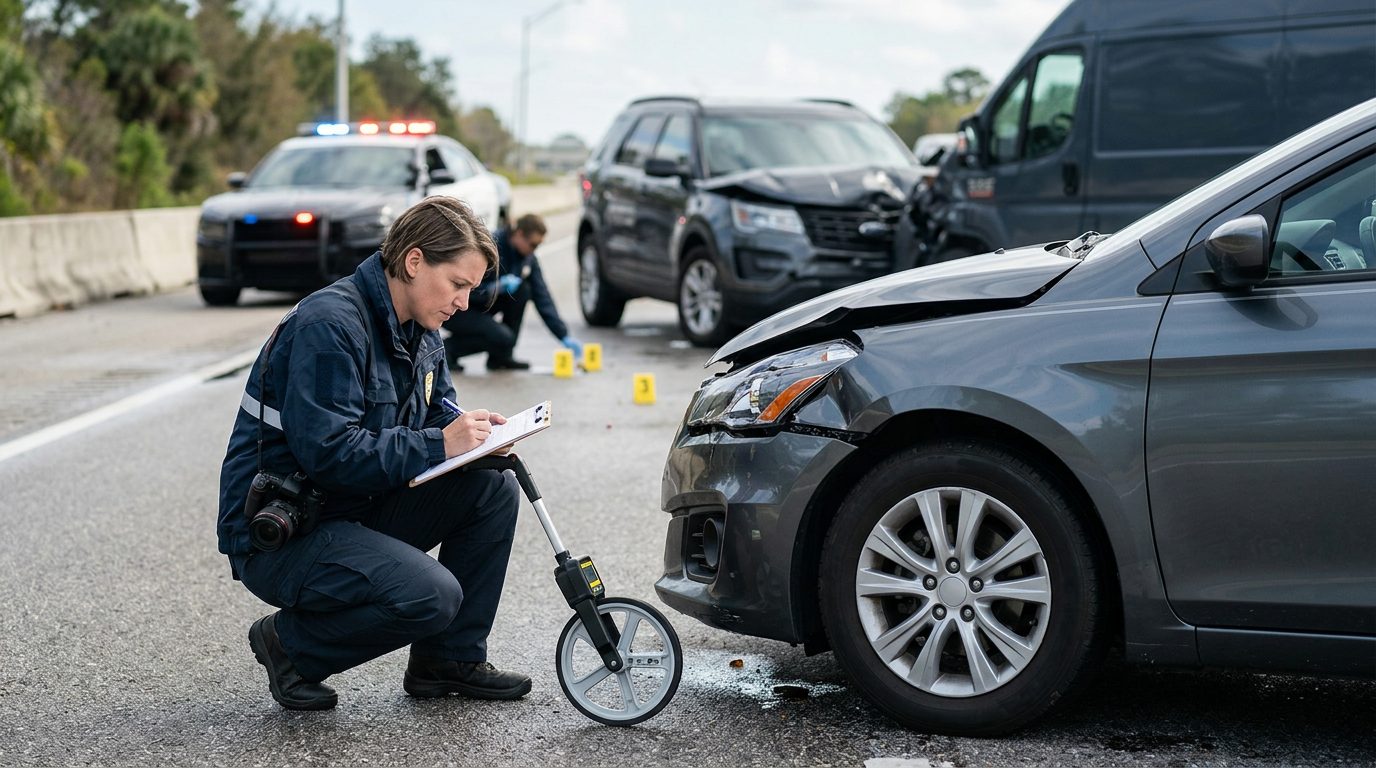
- Document the scene: take photos of vehicle damage, road conditions, and traffic signs. Get contact information from witnesses.
- Report the accident to your insurance company promptly. Most policies require notice within a specific timeframe; delays can jeopardize your UM/UIM claim.
After the Immediate Crisis
- Gather and preserve evidence: medical records, repair estimates, pay stubs, receipts for expenses, and any communication with the other driver or witnesses.
- Do not settle with the other driver directly. Your UM/UIM claim is with your own insurance company.
- Keep detailed records of all medical treatment, lost wages, and other damages.
- Consider legal counsel. An attorney can help you navigate the claim process, negotiate with your insurer, and ensure you receive fair compensation.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Your Next Steps
If you’ve been hit by an uninsured or underinsured driver, start by reviewing your own policy. Check your current UM/UIM limits and consider whether they’re adequate for your situation.
If you’re injured, document everything. Medical records, wage statements, and expense receipts are the foundation of a strong claim.
If your insurer is resisting your claim or offering less than you believe your damages are worth, you have options. Florida law gives you the right to pursue a bad-faith claim if your insurance company unreasonably denies or undervalues your UM/UIM claim.
If your damages exceed your UM/UIM limit—especially in cases of severe or permanent injury—an attorney can advise whether pursuing a claim against the uninsured driver’s personal assets makes sense, or whether other remedies are available.
You have two years from the date of the accident to file a lawsuit in Florida. Don’t wait; evidence fades and memories blur.
Frequently Asked Questions
What’s the difference between UM and UIM coverage?
Uninsured motorist (UM) coverage applies when the at-fault driver has zero insurance. Underinsured motorist (UIM) coverage applies when their insurance limit is too low to cover your full damages.
How much does UM/UIM coverage cost in Florida?
UM/UIM coverage is typically inexpensive—often just a few dollars per month—relative to the protection it provides.
Can I stack UM/UIM limits across multiple vehicles?
Some policies allow stacking. Check your policy documents or ask your insurance agent. An attorney can also advise you.
What happens if I’m hit by a hit-and-run driver?
Your UM coverage may apply if you file a police report and meet your insurer’s requirements, even if the other driver is never identified.
How long do I have to file a UM/UIM claim in Florida?
You have two years from the date of the accident to file a lawsuit. Report the accident to your insurer immediately.
What if my insurer denies my UM/UIM claim?
Florida law requires your insurance company to act in good faith. If you believe they’ve unreasonably denied or undervalued your claim, you may have grounds for a bad-faith claim.
If you’ve been hit by an uninsured or underinsured driver and aren’t sure whether your damages are covered or how much your claim is worth, we can help clarify your options. People in your situation can contact us to understand their UM/UIM coverage and what they can recover.
Types of Damages in Florida Car Accident Cases
Economic Damages
Medical bills, lost wages, rehabilitation costs, vehicle repair or replacement, and other out-of-pocket expenses directly tied to the accident.
Non-Economic Damages
Pain and suffering, emotional distress, loss of enjoyment of life, scarring or disfigurement, and permanent disability or impairment.
Punitive Damages
Florida law allows punitive damages only if the trier of fact, based on clear and convincing evidence, finds that the defendant was personally guilty of intentional misconduct or gross negligence.
What Affects the Value of Your Claim
Severity of Injury
Catastrophic injuries—spinal cord damage, paralysis, traumatic brain injury, amputation—typically result in higher compensation than minor injuries.
Liability and Fault
Clear evidence that the other driver caused the accident strengthens your claim. Florida's comparative negligence rules may reduce recovery if you share fault (Fla. Stat. § 768.81(6)).
Insurance Coverage
The at-fault driver's policy limits, your own uninsured/underinsured motorist coverage, and available assets all influence what you can recover.
Long-Term Impact
Permanent disabilities, ongoing medical care, lost earning capacity, and lifetime care needs significantly increase claim value.
Time Matters
Florida law sets strict deadlines for filing a personal injury lawsuit after a car accident. Waiting too long can cost you your right to recover. Contact an attorney as soon as possible after your accident.
Common Questions About Car Accident Damages
What's the difference between UM and UIM coverage?
Uninsured motorist (UM) coverage applies when the at-fault driver has zero insurance. Underinsured motorist (UIM) coverage applies when their insurance limit is too low to cover your full damages.
Can I recover if I was partially at fault?
Florida's comparative negligence rule allows recovery even if you share some fault—but your compensation is reduced by your percentage of fault (Fla. Stat. § 768.81(6)).
What if the other driver is uninsured?
Your own uninsured motorist coverage may cover your damages. If you don't have UM coverage, you may still pursue a claim against the driver's personal assets, though collection can be difficult.
How long does a car accident case take?
Settlement timelines vary. Simple cases may resolve in months; complex or catastrophic injury cases often take longer as medical treatment continues and damages are fully assessed.