

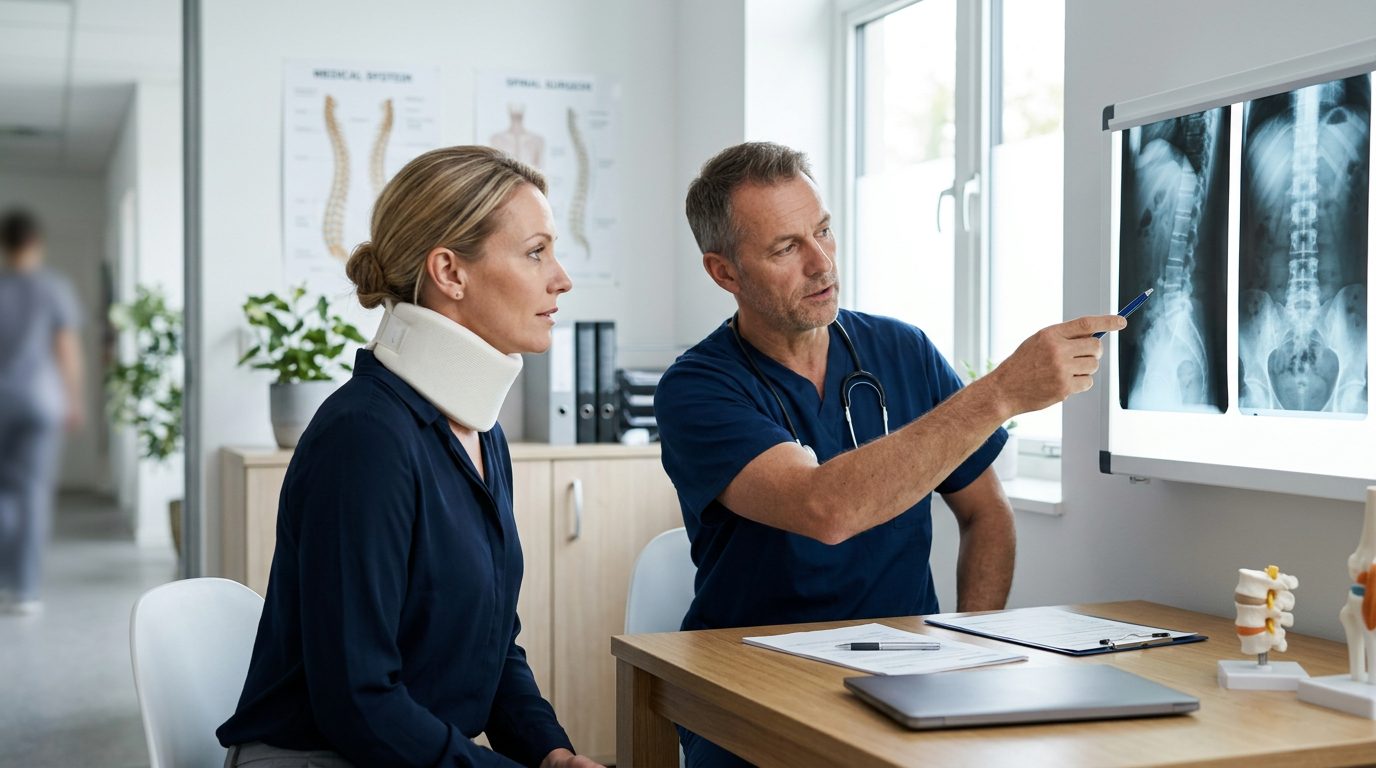
Back Injury Claims in Florida
How Back Injury Settlements Are Calculated in Florida
Understanding the damages formula: medical costs, lost income, future care, and pain and suffering.
By CHG Lawyers · Published September 16, 2026
Back Injury Car Accident Settlement in Florida: How Damages Are Calculated
A back injury car accident settlement isn’t arbitrary. It follows a framework built on your documented losses, injury severity, and Florida’s comparative fault law. Understanding this framework helps you evaluate whether an offer is fair—and recognize when it falls short.
The critical distinction most people miss: a minor muscle strain and a spinal cord injury are not the same claim. They settle for radically different amounts because their long-term impact, treatment costs, and permanent effects differ fundamentally. This article explains how that difference translates into dollars.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
The Two Categories That Drive Settlement Value
Florida courts and insurance companies value back injury claims using two distinct categories:
Economic damages are measurable, documented losses: medical bills, lost wages, and out-of-pocket costs.
Non-economic damages compensate for suffering without a receipt: pain, chronic discomfort, lost quality of life, and permanent impairment.
Both matter. Both require evidence. Understanding how each is calculated prevents you from accepting an offer that undervalues your actual harm.
Economic Damages: Documented Losses You Can Prove
Economic damages are straightforward in theory—they’re what you spent and what you lost—but require meticulous documentation.
Medical expenses include emergency room visits, diagnostic imaging (MRI, CT scans, X-rays), physical therapy, epidural steroid injections, spinal surgery, medications, and ongoing treatment your physician recommends. For catastrophic injuries, medical experts and life-care planners project long-term care costs: future surgeries, assistive devices, home modifications, and chronic pain management over your remaining lifespan. These projections are critical evidence in high-value claims.
Lost wages are income you missed while recovering or unable to work. This includes time off for medical appointments, surgery recovery, and periods when your injury prevented you from performing your job duties. Documentation matters: pay stubs, tax returns, and employer verification letters establish your pre-injury earnings.
For injuries causing permanent limitations, a vocational rehabilitation expert calculates your reduced earning capacity. If you earned $60,000 annually as a warehouse manager before a herniated disc ended your ability to lift or stand for extended periods, and you can now only earn $35,000 in a desk role, that $25,000 annual loss compounds across your remaining working years—potentially $500,000 or more over 20 years. This expert testimony substantiates damages that raw medical bills alone cannot capture.
Out-of-pocket costs accumulate: transportation to medical appointments, home modifications (grab bars, accessible shower equipment, ergonomic furniture), prescription medications, and equipment like lumbar braces or compression sleeves. Keep receipts for everything. These costs are often overlooked but add up quickly in serious cases.
Documentation gaps are settlement killers. Insurance adjusters scrutinize medical records for consistency. If you stop attending physical therapy for three months, then resume, adjusters argue your injury improved and you’re exaggerating current pain. Missing wage documentation means lost-income claims are discounted or rejected outright. Complete records—medical bills, pay stubs, appointment confirmations, and receipts—create an airtight economic picture.
Non-Economic Damages: Pain, Suffering, and Permanent Impairment
Non-economic damages compensate for suffering and life disruption. Unlike medical bills, there’s no invoice for chronic pain or the inability to play sports you loved. This is where injury severity creates dramatic settlement differences.
Minor back injuries (muscle strains, minor ligament sprains) typically heal in 4–8 weeks with conservative treatment. Non-economic damages are modest because the injury is temporary. A strain settling for $5,000–$15,000 in total damages reflects the brief recovery period and minimal lasting impact.
Catastrophic back and spinal cord injuries (herniated discs with nerve compression, spinal cord damage, cauda equina syndrome, or fractures requiring fusion surgery) cause permanent impairment. These injuries result in chronic pain, permanent mobility limitations, sexual dysfunction, bowel/bladder dysfunction (in spinal cord injuries), and the need for lifelong medical management. Non-economic damages in these cases are substantial—often $100,000 to $1,000,000 or more—because the injury fundamentally alters your life forever.
The distinction is not semantic. It’s the difference between a temporary setback and permanent disability.
Calculating Non-Economic Damages: Two Methods
The multiplier method applies a multiple to your medical expenses based on injury severity:
- Mild injuries (full recovery expected): 1–2× medical costs
- Moderate injuries (some lasting effects): 2–4× medical costs
- Severe injuries (permanent impairment): 4–5× or higher
Example: If your medical bills total $80,000 for a herniated disc requiring surgery and ongoing pain management, a multiplier of 4–5× would yield $320,000–$400,000 in non-economic damages, for a total claim value of $400,000–$480,000.
The per-diem method assigns a daily dollar amount for pain and disability from the accident date until maximum medical improvement (MMI)—the point your doctor determines your condition will not improve further.
Example: If you experience significant pain and limitation for 18 months (548 days) at $300 per day, that’s $164,400 in non-economic damages. This method works well for injuries with a defined recovery timeline, though it undervalues permanent injuries where pain and limitation never truly end.
Medical evidence drives these calculations. Your physician’s documentation of pain severity, functional limitations, and prognosis directly supports non-economic damages. Imaging findings (MRI showing a herniated disc compressing a nerve, for instance) strengthen claims more than injuries with no structural findings. Testimony from your treating physician about your pain level, mobility restrictions, and permanent limitations carries substantial weight in settlement negotiations.
The Two-Year Statute of Limitations: A Critical Deadline
Under Florida law, you have two years from the date of injury to file a personal injury lawsuit (Fla. Stat. §95.11). This deadline applies to car accident claims, including back injuries.
This deadline is not theoretical—it directly affects settlement negotiations. As the two-year mark approaches, insurance companies know you’re running out of time to file suit. This creates leverage: if you haven’t settled, your attorney can credibly threaten trial, which pressures insurers to move settlement discussions higher. Conversely, if you’re close to the deadline with no settlement, you’re in a weaker negotiating position because the insurer knows you may accept less to avoid missing the deadline.
Settlement timing matters strategically. Settling too early—before your injury’s full extent is clear—locks you into a number that may not reflect your actual damages. Back injuries sometimes worsen weeks or months post-accident as inflammation subsides and structural damage becomes apparent. Settling immediately after the crash, before imaging or specialist evaluation, typically undervalues your claim. Conversely, waiting until near the deadline without settlement creates time pressure that can force you into a worse deal.
Liability and Insurance Limits: The Ceiling on Recovery
Your settlement depends on two factors: whether the other driver was at fault and what insurance coverage is available.
Liability is legal responsibility for the accident. Clear liability (the other driver ran a red light, was texting while driving, or violated a traffic law) strengthens your claim. Disputed fault or shared responsibility complicates negotiations and reduces settlement value.
Florida follows modified comparative fault under Fla. Stat. §768.81. If you’re found more than 50% at fault for the accident, you cannot recover anything. If you’re 50% or less at fault, your damages are reduced by your percentage of fault. Example: If your damages total $100,000 but you’re 20% at fault, you recover $80,000. This rule directly impacts what you actually receive.
Insurance policy limits set a hard ceiling. If the at-fault driver’s policy limit is $25,000 but your damages are $150,000, you cannot recover more than $25,000 from their insurance—regardless of your actual losses. This gap is where your own coverage becomes critical.
Underinsured motorist (UIM) coverage on your own auto policy bridges this gap. If you have $100,000 in UIM coverage and the at-fault driver’s limit is $25,000, your UIM coverage may pay up to $75,000 additional (depending on your specific policy terms and whether your damages exceed the at-fault driver’s limit). UIM coverage is essential protection; many people don’t realize they have it or how it works.
Defendant assets matter in cases where insurance is insufficient. If the at-fault driver has substantial personal assets (real estate, business interests, bank accounts), you may pursue a judgment against those assets. However, Florida law provides homestead exemptions and other protections that limit what can be seized. Realistically, collecting against personal assets is difficult and time-consuming.
Understanding these limits early prevents disappointment. If the at-fault driver’s insurance limit is $50,000 and your damages are $200,000, your realistic recovery ceiling is $50,000 from their insurance plus whatever your UIM coverage provides—not the full $200,000.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Why Two Similar Back Injuries Settle for Vastly Different Amounts
Two people hit by cars at the same speed can receive dramatically different settlements because back injuries vary enormously in severity and long-term impact.
Diagnostic findings matter significantly. An MRI showing a herniated disc with nerve compression settles for far more than a strain with no imaging confirmation. Structural damage visible on imaging is objective evidence of injury severity; subjective pain complaints without imaging findings are easier for insurers to discount.
Treatment response determines permanence. An injury improving with 6–8 weeks of physical therapy and anti-inflammatory medication is worth substantially less than one requiring epidural steroid injections, multiple surgeries, or long-term opioid or nerve-pain medication management. If your physician documents that you’ve reached maximum medical improvement (MMI) with permanent limitations—meaning you’ll never fully recover—your settlement value increases significantly.
Age and work history dramatically affect lost-wage calculations. A 35-year-old construction worker with a permanent back injury preventing heavy labor has much higher lost-earning potential than a 65-year-old nearing retirement. A permanent injury to a young person’s earning capacity is worth hundreds of thousands more than the same injury to someone with only a few working years remaining.
Permanent impairment vs. temporary injury is the fundamental dividing line. A herniated disc causing ongoing pain and preventing return to previous work is worth substantially more than a strain healing completely in three months. Permanence transforms a settlement from modest to substantial.
How Settlements Are Actually Negotiated
Insurance companies use proprietary settlement databases and formulas to estimate what similar cases are worth. Your attorney presents your medical records, economic losses, expert testimony, and evidence of pain and suffering to build a demand reflecting your case’s actual value.
Negotiation is iterative. The insurance company makes an offer; your attorney responds with a counteroffer supported by evidence. This continues until both sides reach an acceptable number or the case doesn’t settle and proceeds to trial.
Insurance adjusters distinguish between well-documented claims and weak ones. Strong medical evidence, clear liability, thorough documentation of economic losses, and expert testimony (vocational experts, life-care planners, medical specialists) support higher settlements. Weak evidence—gaps in treatment, no imaging confirmation, missing wage documentation, or social media contradicting pain claims—results in significantly lower offers.
The credible threat of trial influences negotiations. If your attorney can credibly argue that a jury would award more than the insurance company’s offer, that pressure often moves settlement discussions higher. Conversely, if your case has weaknesses (disputed liability, gaps in treatment, limited medical findings), the insurance company knows you’re less likely to win at trial and will offer less.
Most cases settle before trial, but the settlement number reflects what both sides believe a jury might award, adjusted for litigation risk and cost.
Common Mistakes That Reduce Back Injury Settlements
People often inadvertently undermine their own claims:
Accepting an early offer before your injury’s full extent is clear. Back injuries sometimes worsen weeks or months after the accident as inflammation subsides and nerve damage becomes apparent. Settling too soon locks you into a number that doesn’t reflect your actual damages. Wait until your physician confirms you’ve reached maximum medical improvement (MMI) before settling.
Missing medical appointments or gaps in treatment signal to insurers that your injury isn’t serious. If you stop attending physical therapy for months, then resume, adjusters argue your injury improved and you’re exaggerating current pain. Consistent treatment demonstrates injury severity and commitment to recovery.
Posting on social media about your recovery or activities undermines pain-and-suffering claims. A photo of you hiking, playing sports, or engaging in activities you claimed the injury prevented—even if you were in pain afterward—gives insurers ammunition to argue your injury isn’t disabling. Adjust privacy settings and avoid posting about activities inconsistent with your injury claim.
Not documenting lost wages, out-of-pocket costs, or daily-life impact makes it harder to prove economic and non-economic damages. Keep records of everything: medical bills, pay stubs showing missed work, receipts for equipment or home modifications, and detailed notes about how the injury affected your work, hobbies, relationships, and daily activities.
Settling without legal representation means you likely don’t know what your claim is actually worth. Insurance companies count on injured people accepting less than fair value because they don’t understand the calculation framework, don’t have medical experts to substantiate damages, and don’t know how Florida’s comparative fault law applies to their specific facts.
What You Should Do Now
Gather your medical records, bills, and documentation of lost income. Keep a detailed record of how your back injury has affected your work, hobbies, relationships, and daily activities. Do not accept any settlement offer or sign any documents without understanding what you’re giving up and whether the offer reflects your actual damages.
Settlement calculations aren’t guesswork. They’re built on real losses, injury severity, expert testimony, and Florida’s comparative fault law. You deserve a fair valuation based on documented medical costs, lost wages, injury severity, and impact on your quality of life.
If you’re wondering whether a settlement offer is fair, or if you’re unsure whether you have a claim, contact us for a free case evaluation. We can review your back injury car accident settlement, explain what your claim is worth, and advise you on next steps.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
Frequently Asked Questions
How is a settlement for a back injury from a car accident calculated?
A back injury car accident settlement is based on your total losses: medical bills, lost wages, future care costs (substantiated by life-care planners and vocational experts), and non-economic harm like pain and reduced quality of life. The amount depends on injury severity, permanence, how it affects your daily life, and the strength of medical and economic evidence in your case.
What is the difference between economic and non-economic damages?
Economic damages are measurable financial losses: hospital bills, physical therapy, surgery, medications, and missed paychecks. Non-economic damages cover harder-to-measure effects: ongoing pain, limited mobility, permanent impairment, and the loss of activities you used to enjoy. Both require evidence to substantiate.
Does a more serious back injury mean a larger settlement?
Generally, yes. More severe injuries—herniated discs with nerve compression, spinal cord injuries, or fractures requiring surgery—involve higher medical costs and greater lasting effects, which increase claim value. Permanent impairment significantly increases settlement value compared to temporary injuries. Every case depends on specific facts and evidence.
Can I still recover money if I was partly at fault for the crash?
In Florida, you may still recover damages if you were partly at fault, but your recovery is reduced by your share of blame under Fla. Stat. §768.81. If you’re found more than 50% at fault, you cannot recover. An attorney can review your crash facts and explain how these rules apply to your situation.
What is the two-year statute of limitations and why does it matter?
Under Fla. Stat. §95.11, you have two years from the date of injury to file a personal injury lawsuit. This deadline affects settlement negotiations: as it approaches, you have more leverage to demand a fair settlement or threaten trial. Missing this deadline bars your claim entirely, so timing matters strategically.
The Four Categories of Damages
Medical Expenses
All reasonable and necessary treatment: emergency care, surgery, imaging, physical therapy, medications, assistive devices, and ongoing medical management. Settlements include both past bills and documented future medical needs.
Lost Wages and Earning Capacity
Income lost during recovery and, for permanent injuries, reduced earning potential for life. Vocational experts calculate what you would have earned had the injury not occurred.
Future Care Costs
Long-term or lifetime care needs—home modifications, in-home care, specialized equipment, transportation, and medical monitoring—supported by life-care planners and medical testimony.
Pain, Suffering, and Quality of Life
Non-economic damages for physical pain, emotional distress, reduced mobility, loss of enjoyment, and permanent lifestyle changes. These are harder to quantify but often the largest component.
What Affects Your Settlement Amount
Severity and Permanence
Minor strains settle differently than herniated discs or spinal cord damage. Permanent injuries command higher settlements than temporary ones.
Medical Evidence
Clear imaging, specialist reports, and detailed treatment records strengthen your claim. Gaps in care or conflicting medical opinions can reduce value.
Liability and Fault
Strong evidence that the other party was clearly at fault increases settlement leverage. Shared fault in Florida reduces your recovery proportionally.
Impact on Daily Life
How the injury affects your work, family, mobility, and independence matters. Catastrophic injuries that permanently alter your life are valued higher.
Insurance Limits
The at-fault party's policy limits cap what you can recover from that source. Multiple defendants or additional coverage may increase available funds.
Expert Testimony
Life-care planners, vocational experts, and medical specialists provide evidence of future needs and lost earning potential, often significantly increasing settlements.
Don't Settle Too Quickly
Insurance companies often make early offers that undervalue permanent injuries. A quick settlement may not account for long-term care, future complications, or lost earning potential. Getting a full picture of your damages—with medical and vocational expert input—takes time and can mean the difference between inadequate compensation and fair recovery.
Steps in the Settlement Calculation Process
Gather Medical Records
Collect all treatment records, imaging, test results, and specialist reports. This documentation forms the foundation of your damages claim.
Calculate Economic Losses
Add up medical bills, lost wages, and documented out-of-pocket costs. For permanent injuries, vocational and life-care experts project future expenses.
Assess Non-Economic Damages
Evaluate pain, suffering, reduced quality of life, and permanent disability. Multipliers and comparable cases help establish a reasonable range.
Demand and Negotiate
Present a detailed demand package to the insurance company or defendant. Settlement negotiations often involve back-and-forth before reaching agreement or proceeding to litigation.
Florida's Comparative Fault Rule
If you are found partially at fault for the accident, Florida law reduces your recovery by your percentage of fault. For example, if you are 20% at fault, you recover 80% of your total damages. This makes liability investigation and evidence crucial to maximizing your settlement.
Ready to Understand Your Back Injury Claim?
Related practice areas
- Car Accident Settlements in Florida: What Your Case May Be Worth
- What Affects the Average Claim Amount for a Car Accident?
- How Long Does It Take to Settle a Car Accident Claim in Florida?
- How Do Pre-Existing Conditions Affect a Car Accident Back Injury Claim?
- Spinal Cord Injuries: A Guide for Victims and Families Facing Paralysis