
Not at Fault? Here's How Insurance Can Work for You
Plain-language answers from CHG Personal Injury Lawyers on how the at-fault driver's insurer, your own policy, and a lawsuit fit together after a crash in Florida.
Florida-Based Representation
Florida
Serving clients throughout the state
Free
Confidential first consultation, no obligation
Igor Hernandez
Responsible attorney, admitted to The Florida Bar
By CHG Lawyers · Published October 24, 2026
How does insurance work when it’s not your fault? Florida Car Accident Claims
Who pays for your losses after a crash you did not cause? Knowing how the system works can help you avoid mistakes. Mistakes can hurt a valid claim. Knowing the system also helps you protect your rights.
If you were hurt in a car accident, a free consultation with our firm can help you understand your options. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Florida’s No-Fault Insurance System
Florida uses a no-fault system for auto injuries. Florida requires vehicle insurance to include Personal Injury Protection (PIP). PIP, or personal injury protection, is the coverage for injuries to the named insured, relatives residing in the same household unless excluded under s. 627.747, persons operating the insured motor vehicle, passengers in the motor vehicle, and other persons struck by the motor vehicle while not an occupant of a self-propelled vehicle, under Florida’s Motor Vehicle No-Fault Law.
It can also pay 60% of lost income if you cannot work. The limit is $10,000 for medical and disability benefits (Fla. Stat. § 627.736(1)).
Under Florida law, a driver whose negligence causes a crash may be legally responsible. Negligence means carelessness that causes harm. That driver may owe the other person for injuries and property damage.
Florida’s no-fault law limits lawsuits for pain and suffering. The injury must meet the permanent-injury threshold.
But one critical rule is easy to miss. Many injured people do not know about it.
The nonjoinder rule: You cannot sue the insurance company directly. Many injured people believe they can sue the at-fault driver’s insurer to recover damages. This is a common mistake.
In Florida, you must first obtain a settlement or verdict against the driver. A verdict is a court’s final decision. Only then can you pursue the insurer (Fla. Stat. § 627.4136(1)). You cannot name the insurance company as a defendant until you first obtain a settlement or verdict against the insured driver (Fla. Stat. § 627.4136(1)).
This step often surprises people. It can delay your recovery if it is not handled correctly. An attorney can guide you through this requirement. An attorney can also make sure your claim follows the proper order.
What the At-Fault Driver’s Liability Insurance Covers
Several sources may cover your losses. These include your own PIP coverage. They also include the at-fault driver’s liability coverage.
It includes emergency care, hospital stays, surgery, physical therapy, ongoing medical care, and rehabilitation.
Vehicle damage. This covers harm to your vehicle. It may include repair costs. It may also include the vehicle’s value if it cannot be repaired.
Lost wages. This covers income you lose while you cannot work during recovery. It includes salary, self-employment income, and benefits lost because you missed work.
Injuries can affect a person’s body and daily life in many ways, including physical pain, emotional distress, and reduced quality of life. In serious cases, these damages can be substantial. This is true for injuries such as spinal cord damage, traumatic brain injury, amputation, severe burns, or permanent disability.
Property damage beyond the vehicle. This covers personal items damaged in the crash. Examples include electronics, clothing, and medical equipment.
The at-fault driver’s insurer will ask for documents. These include medical records, repair estimates, pay stubs, and receipts. Complete, organized records speed up the process. They also strengthen your claim.
Filing a Claim Against the At-Fault Driver’s Insurance
Filing a claim follows a simple process.
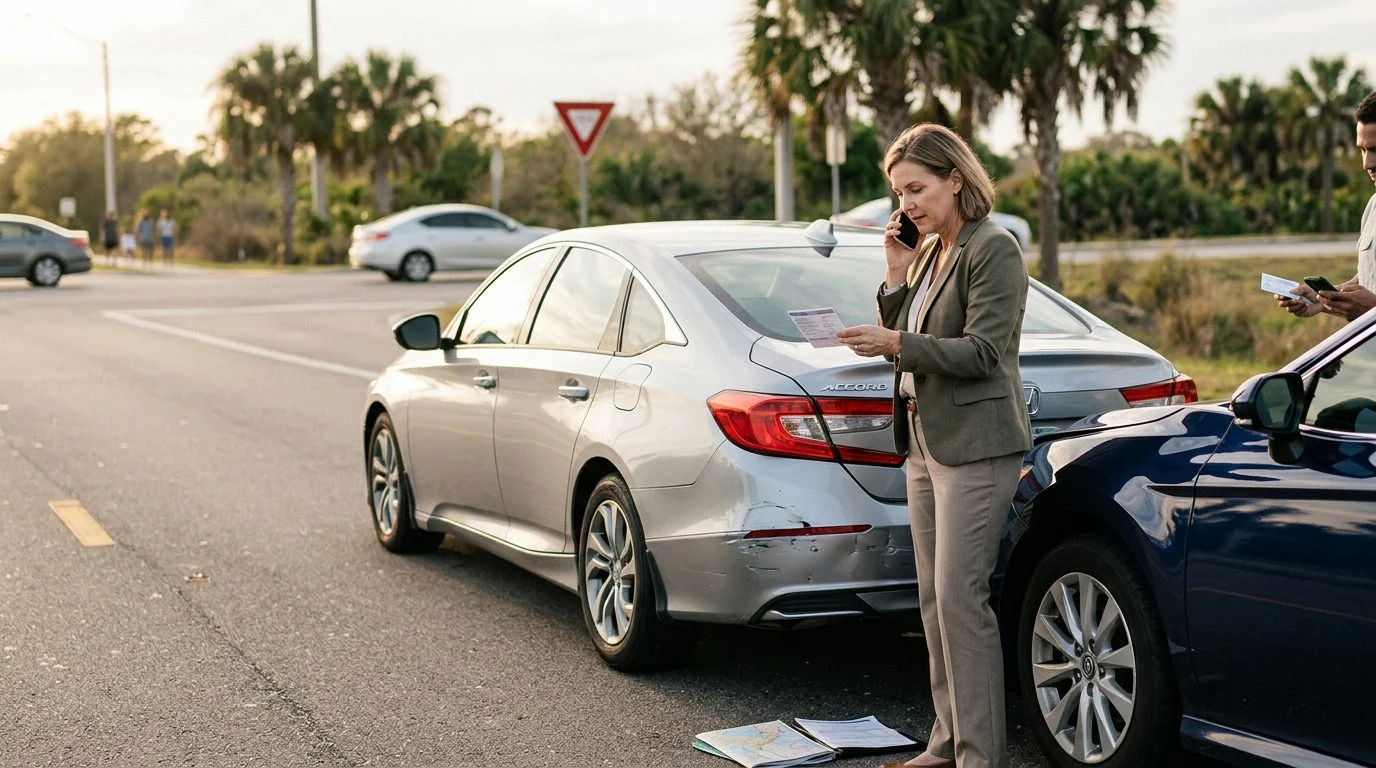
Report the accident. Call the police and get a report number. A police report creates an official record. It often helps show who is responsible.
Gather evidence. Take photos of the vehicle damage, the scene, and any visible injuries. Write down the other driver’s name, phone number, address, driver’s license number, and insurance information. Get contact details from any witnesses.
Notify the at-fault driver’s insurance company. You can file a claim directly with their insurer. You do not need to wait for the other driver to file first. Give the insurer the accident date, the location, the police report number, and a short description of what happened.
Submit documentation. Send medical records, repair estimates, proof of lost income, and receipts for accident-related expenses. Keep copies of everything.
The insurer investigates. The insurer will review your claim and the police report. It may contact witnesses or inspect the vehicle. If responsibility is clear, the process moves faster.
Receive a settlement offer or claim approval. If the insurer agrees you are owed money, it will make a settlement offer. It may also approve payment of documented expenses. You can accept the offer. You can ask for more. You can also reject it and take legal action.
Negotiate if needed. If the offer does not fully cover your losses, you can make a counter-offer. You can also ask how the insurer calculated the amount. Many claims are settled through negotiation without going to court.
The Filing Deadline: A Critical Date You Cannot Miss
If you must file a lawsuit to recover your damages, time is limited. Florida sets a deadline for filing these lawsuits. If that deadline passes, your claim may be barred. This can happen even if your injuries are real. It can also happen even if the at-fault driver is clearly responsible.
Many injured people do not know a deadline exists. They assume they can file years later. That assumption can cost them the right to recover. This is true no matter how strong their case is.
Insurance claims can be filed right away. Florida PIP medical benefits generally require initial services and care within 14 days after the accident (Fla. Stat. § 627.736(1)(a)). Policies also have notice requirements. Waiting too long can weaken your position.
Evidence disappears over time. Witnesses move away or forget details. The longer you wait, the harder it is to prove your damages.
If the insurer denies your claim or offers too little, you may need to file a lawsuit before the deadline. Filing protects your rights.
Will My Insurance Rates Go Up If I’m Not at Fault?
Generally, a claim against the at-fault driver’s liability coverage should not raise your own premiums.
Important exception: You may see a rate increase in some cases. This can happen if you file under your own collision or comprehensive coverage. You might do this if the other driver is uninsured or underinsured. You might also do this if you want your own insurer to handle the claim.
Collision coverage pays for damage to your vehicle, no matter who is at fault. Filing a collision claim is treated differently than filing against another driver’s liability. Comprehensive claims cover things like theft, weather, vandalism, or animal strikes. These usually affect your rates less than collision claims. Each insurer has its own policies.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What If the Other Driver Is Uninsured or Underinsured?
Not all drivers carry insurance. Some carry only the state minimum. That may not be enough to cover serious injuries.
Underinsured motorist (UIM) coverage applies when the at-fault driver’s liability limits are too low. For example, the other driver may carry only the state minimum for bodily injury. Your medical bills and lost wages may be far higher. Your UIM coverage helps fill that gap.
A UM or UIM claim may affect your rates differently than a liability claim against another driver. Review your policy. Talk with your insurer about it.
Collateral Sources: Which Benefits Reduce Your Award and Which Do Not
When you recover damages from the at-fault driver, Florida law requires the court to reduce your award. The reduction covers certain “collateral sources.” These are benefits you have already received from other sources.
Not all benefits count. Knowing which ones do and which do not can greatly affect your final recovery.
Other benefits and how they may be treated:
Under this statute, Medicare, Medicaid, and workers’ compensation benefits are not considered collateral sources.
If you received Medicare or Medicaid, those programs may have reimbursement rights. In other words, they may be repaid from your recovery. This is an important distinction. It protects injured people who rely on government programs.
The difference matters a great deal. Under Florida law, some private insurance benefits may reduce an award. But they are not deducted when the payer has a right to be repaid (Fla. Stat. § 768.76(1)). Medicare and Medicaid may hold reimbursement rights. Those rights can be paid from the recovery. Understanding this helps you judge settlement offers and plan for your recovery.
Your Right to Compensation for Injuries
If you were hurt in a car accident, a free consultation with our firm can help you understand your options.
For minor injuries, such as cuts, bruises, or soft-tissue damage, Florida’s no-fault law generally limits recovery for pain and suffering. This applies unless the injury meets one of the statutory thresholds: significant and permanent loss of an important bodily function, permanent injury within a reasonable degree of medical probability (other than scarring or disfigurement), significant and permanent scarring or disfigurement, or death (§ 627.737(2)). For serious or permanent injuries, the picture changes a great deal.
If you suffered a spinal cord injury, traumatic brain injury, amputation, severe burns, or other catastrophic harm, compensation may include:
- All past and future medical treatment and rehabilitation
- Care and equipment that may be needed after a serious injury
- Lost earning capacity, meaning the ability to earn money in the future, if you cannot return to work
- Pain and suffering
- How the injury affects daily life and the activities you once enjoyed
If that coverage is not enough, your own underinsured motorist coverage may apply. This can happen when policy limits are low or damages are very high.
For catastrophic injuries, you may have claims against more than one party. Examples include a commercial truck driver’s employer, a rideshare company, or a property owner. This can greatly increase the total recovery available.
When to Seek Legal Guidance
Many minor accidents are resolved quickly. This happens when responsibility is clear and damages are modest.
Legal help becomes important when:
- Your injuries are serious or permanent. You may need ongoing medical care or long-term disability accommodations.
- The insurance company denies your claim. It may also offer an amount that does not cover your documented losses.
- Responsibility is disputed. The other driver may say you were partly at fault. The accident facts may also be unclear.
- Multiple parties are involved. The accident may have happened in a commercial setting, such as a truck crash or a rideshare accident.
- The filing deadline is approaching. You have not yet settled or filed a lawsuit.
An attorney can gather evidence and obtain expert testimony. Expert testimony is opinion evidence from qualified professionals. An attorney can also negotiate with insurers. If needed, an attorney can pursue a lawsuit. For catastrophic injuries, legal guidance is often essential. A lawyer can explain which losses, including the cost of lifetime care, may be part of a claim and what steps to consider next.
Frequently Asked Questions
Does filing a claim against another driver’s insurance affect my own rates?
It can. If you file a claim under your own collision coverage, your rates may increase.
How long do I have to file a claim in Florida?
Florida sets a deadline for filing a lawsuit, and deadlines apply to these claims. Insurance claims can often be filed right away. Waiting too long may hurt your case. Act promptly to preserve evidence and witness statements.
What if the other driver admits fault but their insurance company denies my claim?
An attorney can help you challenge the denial. An attorney can also help you recover the compensation you are owed.
Can I recover pain and suffering damages in Florida?
Not always. Whether you can recover pain and suffering from the at-fault driver depends on several things. The main one is whether your injury meets Florida’s permanent-injury threshold under § 627.737(2). How strong your evidence is also matters. Serious, permanent injuries typically lead to higher pain and suffering awards.
What happens if I’m found partly at fault for the accident?
Florida follows modified comparative fault. This means your share of blame matters. If you are found 50% or less at fault, you can still recover damages. Your award is reduced by your percentage of fault. If you are found more than 50% at fault, you recover nothing.
If you were injured in a car accident you did not cause, you may have questions. You may wonder if your claim will be handled fairly. You may wonder if you have missed a deadline. You may wonder if your injuries call for legal help. Contact our team for a free case evaluation. Our free first consultation is confidential and has no obligation to continue. We focus on personal-injury claims. We can help you understand your rights, work through the procedural requirements, and pursue the full compensation you deserve.
What Injured Floridians Should Know About Insurance
Fault and coverage are different questions
Who caused a crash and which insurance policies respond to it are separate issues. Both need careful review.
Your own policy may still matter
Your personal coverage can apply even when another driver caused the collision. Reviewing your policy is part of the picture.
Timing can affect your options
Insurance steps and court deadlines can run on different schedules. Contacting a lawyer early helps protect your choices.
Records make a difference
Police reports, medical bills, photos, and insurer letters all help show what happened and what it cost you.
Families can be affected too
Passengers, spouses, and family members often face bills and lost income. Their claims and questions matter as well.
You don't have to sort this out alone
Our team can explain each step in plain language and handle communication with insurers while you focus on recovery.
Before You Talk to an Insurer
Adjusters may call quickly and ask for a recorded statement or a signed release. Speak with a lawyer before you agree to anything in writing or on tape.
Common Questions About Not-at-Fault Claims
Will my insurance rates go up?
Ask about this before you file so you can weigh your options.
Who pays my medical bills?
Florida's no-fault coverage, your own policy, and the at-fault driver's insurer can each play a role. Our team reviews which sources apply to your situation.
Can I still make a claim after a long delay?
Florida sets deadlines for both insurance claims and lawsuits. Waiting can make your situation harder, so contact our firm promptly.
What if the insurer offers a quick settlement?
Have a lawyer review any offer before you accept it.
Your First Consultation Is Free, Confidential, and Comes With No Obligation. Let's Review Your Situation Together.
Related practice areas
- Car Accident Settlements in Florida: What Your Case May Be Worth
- How much is a neck and back injury worth?
- Pain and Suffering Compensation After a Car Accident in Florida
- Car Accident Injury Claims: What Your Case Could Be Worth and How Settlements Work
- Spinal Cord Injuries: A Guide for Victims and Families Facing Paralysis