
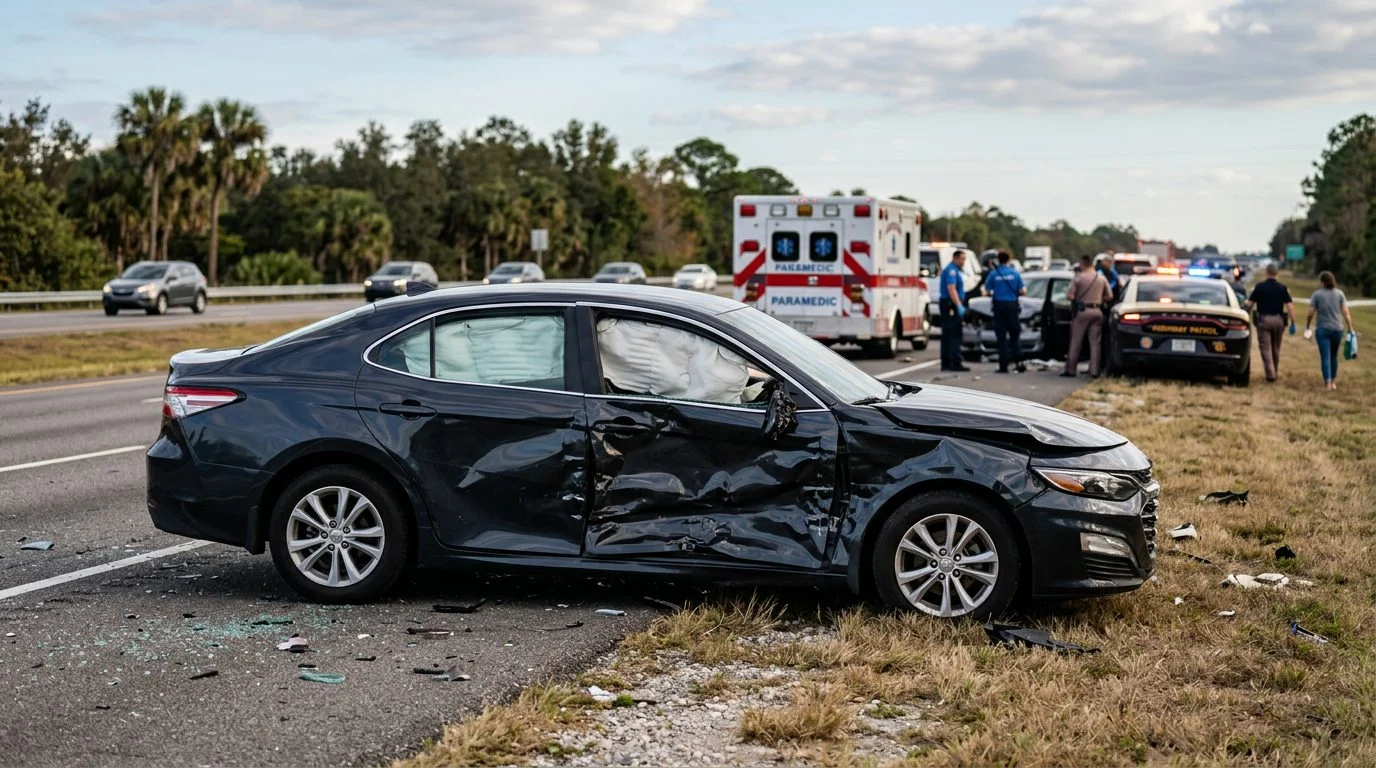
Car Accident Claims | Serving Florida
How Much Do Car Accident Settlements Pay in Florida?
No two settlements are alike. Here is what shapes the value of a car accident claim and how to start a conversation about your options with CHG Personal Injury Lawyers.
Florida-Based Representation
Florida
Serving clients throughout the state
Licensed
Attorneys admitted to The Florida Bar
By CHG Lawyers · Published October 24, 2026
How Much Do Personal Injury Settlements Usually Pay for Car Accidents in Florida?
If you were hurt in a crash, you may wonder what your claim is worth. You may still be in pain. You may still be seeing doctors. You may be worried about bills. That is a reasonable question.
This guide explains what affects the value of a car accident claim in Florida. It also explains the insurance steps and what to do next.
If you were hurt in a car accident, reach out for a free, confidential first consultation. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
The Two Things to Act On Now
Two points matter more than any settlement number.
Deadlines apply. Florida law sets time limits for filing a car accident lawsuit. Missing one can end your right to sue. Contact CHG Personal Injury Lawyers promptly so your options can be reviewed in time.
Contacting the firm early does not mean you have lost time. It also does not promise any particular result. It gives your claim a better chance to be protected.
Fault can affect what you recover. Florida’s shared-fault rules can reduce what you recover. In some situations, they can bar recovery entirely.
Do not assume the other driver’s insurer will explain how these rules apply to you.
There Is No Single Answer, but There Is a Framework
No one can responsibly give you a settlement amount based on a number on a website. Your claim’s value depends on several things:
- How serious your injury is
- Your medical bills
- Wages you have lost
- How the injury has changed your daily life
- Who was at fault
The framework below shows how lawyers and insurers commonly think about these pieces.
What Determines the Value of a Car Accident Claim?
Your claim rests on four main factors:
- Injury type and severity
- Money you have spent and lost, called economic damages
- Pain and life changes you have experienced, called non-economic damages
- Who was at fault
Economic damages are the easiest to calculate. They include medical bills, lost wages, future medical care, and vehicle repair costs. Receipts and paperwork support these amounts.
Non-economic damages are harder to pin down. These are payments for pain and for changes to your life. Florida’s rules on which non-economic losses can be recovered in motor vehicle cases depend on the type and extent of the injury. These losses often make up a large part of the claim’s value. This is especially true in serious or catastrophic cases.
Liability and fault matter a great deal. Liability means who legally caused the crash. Our lawyers can review how Florida’s shared-fault rules apply to your crash. This includes the police report, witness statements, and any dashcam footage.
Insurance policy limits cap what you can recover from a particular policy. Suppose the at-fault driver’s policy covers only $100,000. Your claim is worth $250,000. You may receive that policy limit from the driver’s insurer. Other sources may be available. One example is an underinsured motorist claim under your own policy. Ask a lawyer whether that applies to you.
Who Else Besides the Driver Might Be Responsible?
Many injured people assume only the driver can be sued. That is not always true. Depending on the facts, other parties may share responsibility. These can include:
- The vehicle’s owner
- An employer whose employee was driving for work
- A company that rented the vehicle
Each situation is different. The limits and exceptions for an individual owner, a short-term lessor, or a rental company are not the same. Ask about every possible source when you speak with the firm. It is easy to miss one.
Insurance Claims Are Not the Same as Lawsuits
These two steps are often confused:
- Filing an insurance claim is a request to an insurer. Usually this is the at-fault driver’s company or your own. You ask it to pay for losses under a policy. Most claims work this way. An adjuster, the insurance company’s claims reviewer, checks your medical records and bills.
- Suing the at-fault driver is a separate step. It is a formal court case against the person responsible for the crash.
Speaking with an adjuster is not the same as filing a lawsuit. Adjusters often ask for recorded statements early on. Before you give one, talk with the firm. An early statement can be used later. You do not have to answer every question on the spot.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Much Do Car Accident Settlements Usually Pay by Injury Type?
Claim value varies widely by injury type. Here is a general breakdown.
Minor injuries include soft-tissue damage, whiplash, and minor cuts or bruises. They tend to settle for relatively modest amounts. Recovery often takes weeks to a few months. Medical costs are modest, and little or no work is missed.
Moderate injuries include broken bones, significant sprains, and cuts that need stitches. They generally settle for more than minor injuries. Recovery can take months. You may need physical therapy, time off work, or both. Some stiffness or weakness may linger.
Serious injuries include severe fractures, head injuries, and significant organ damage. They often settle for much higher amounts. Recovery is long. Permanent scarring, chronic pain, or lasting loss of function is possible.
Catastrophic injuries include spinal cord injury with paralysis, amputation, severe traumatic brain injury, and severe burns. These claims frequently reach the highest values. These injuries can cause permanent, life-altering impairment. You may need lifetime care, assistive equipment, home changes, and ongoing treatment. The claim value reflects decades of future costs and lost earning ability.
Wrongful death claims vary widely. The value depends on the person’s age, earning ability, and family situation. These claims are brought for the family and estate of the person who died. The firm can explain who may bring them and what they may recover.
Economic Damages: The Calculable Costs
Medical expenses include:
- Emergency room visits and hospital stays
- Surgery and imaging, such as X-rays, MRI, and CT scans
- Physical therapy and ongoing treatment
- Prescription medications
- Medical equipment, such as wheelchairs, braces, or monitors
Lost wages cover income you missed while recovering. This includes time away from work for medical visits and rehabilitation.
Future medical care covers ongoing treatment, rehabilitation, or long-term care for permanent injuries. This matters most in catastrophic cases.
Property damage covers repair or replacement of your vehicle. It also covers personal belongings damaged in the crash.
Keep every receipt, bill, pay stub, and appointment record. Insurance adjusters and defense lawyers will review these figures closely.
Non-Economic Damages: Pain, Suffering, and Life Changes
Non-economic damages are harder to measure. Still, they often make up most of a claim’s value.
Pain and suffering includes physical pain during recovery and ongoing chronic pain. A broken leg that heals cleanly may involve limited pain and suffering. A spinal cord injury may involve a lifetime of pain.
Emotional distress covers anxiety, depression, post-traumatic stress disorder (PTSD, a condition that can follow a frightening event), or fear of driving after the crash. Medical and mental health records document these effects. Share them with your doctors.
Loss of enjoyment of life means you can no longer do activities you loved. Examples include playing sports, hiking, spending time with family, or working in your career. The more your life has changed, the more this matters.
Disfigurement or scarring affects your appearance and self-image. This is especially true when scars show on the face, neck, or hands.
Loss of consortium is a claim a spouse may bring for the harm to the marriage, such as lost companionship. The firm can review that question for your family.
How Do Lawyers and Insurers Estimate Value?
A common starting method works like this:
- Start with economic damages. Add up medical bills, lost wages, and out-of-pocket costs.
- Apply a multiplier to non-economic damages. Multiply economic damages by 1.5 to 5, depending on how severe the injury is. Minor injuries usually use the lower end (1.5–2). Serious injuries use the middle (2.5–3.5). Catastrophic injuries use the higher end (4–5).
- Adjust for liability. If you are found partly at fault, reduce the total by your percentage of fault.
- Consider insurance limits. The at-fault driver’s policy may not cover the full amount.
Example: Suppose your medical bills and lost wages total a set amount. Your injury is serious, such as a broken leg with permanent weakness. For illustration only, this example multiplies the economic-damages figure by 3. That gives a base claim value.
If you were 10% at fault, the example reduces that base value by 10%. How fault affects recovery under Florida law depends on the facts of each case. This example does not show how that law applies to any particular claim.
Is $50,000 a Good Settlement for a Car Accident?
It depends on your injury and your circumstances. For a minor injury with $10,000 in medical costs, $50,000 may be generous. For a serious injury with $100,000 in medical bills and permanent damage, it may be far too low.
A fair settlement should cover your economic damages. It should also include a reasonable amount for pain, suffering, and other non-economic losses. If an offer seems low for your injury and costs, review it with a lawyer before you accept.
Insurance companies often make low first offers. They may hope you will accept quickly. You do not have to accept a first offer.
If you were hurt in a car accident, reach out for a free, confidential first consultation. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Much of a Settlement Will I Actually Receive?
Your gross settlement is the total before any deductions. It is not what you take home. Some deductions may come out first.
Attorney’s fees and case costs: CHG Personal Injury Lawyers charges no attorney’s fees and no case costs unless there is a recovery.
Medical liens let healthcare providers or insurance companies be repaid from your settlement. A lien is a legal claim to be paid back. The repayment is for treatment they provided. If your health insurance paid $30,000 toward your care, it may have a lien for that amount.
Your lawyer can explain which deductions apply to your case.
Factors That Increase or Decrease Claim Value
Factors that increase value:
- Clear liability (the other driver was obviously at fault)
- Severe injury with lasting effects
- High medical costs
- Permanent impairment or disability
- Lost wages and lost earning ability
- Younger age (a longer life ahead to account for)
- Strong evidence, such as a police report, witness statements, dashcam footage, and medical records
Factors that decrease value:
- Shared fault (you were partly responsible)
- Minor injury with quick recovery
- Low medical costs
- No permanent damage
- Older age
- Weak evidence or conflicting accounts of how the crash happened
Insurance companies tend to stress factors that lower value. Knowing these dynamics helps you spot when an offer is unreasonably low.
Commercial Trucks and Shared Responsibility
When a commercial truck is involved, more than one company may share responsibility for the crash.
In Montgomery v. Caribe Transport II, LLC (2026), the U.S. Supreme Court held that a state-law claim is not preempted. In plain terms, federal law does not block the claim. So Montgomery’s negligent-hiring claim falls within the FAAAA’s safety exception, which saves it from preemption. The Court found it falls within the safety exception (Montgomery v. Caribe Transport II, LLC).
Seat Belts and Your Claim
Whether seat-belt use or other conduct before a crash affects your claim depends on two things. One is the facts. The other is the law that applies to your case.
Do not assume a question about your seat belt ends your claim. Do not guess at the answer on your own. Tell the firm exactly what happened. Let a lawyer review how it may be raised.
Why a Free Evaluation Helps You Understand Your Claim
Online calculators and settlement ranges are only starting points. They cannot account for your medical history. They cannot account for the details of the crash or how the injury affects your daily life. They also cannot account for other parties who may be responsible.
A lawyer can review your medical records, the police report, and insurance information. A lawyer can also look at the full picture of how the injury has changed your life. Then the lawyer can give you a realistic estimate for your situation.
Many car accident claims are worth more than the injured person first realizes. This is especially true when the injury is serious or has lasting effects.
Following Your Doctors’ Care
This article is general information. It is not medical advice. Follow your doctors’ treatment plans and attend your appointments. Keep records of your symptoms and care. Those records also matter for your claim.
Frequently Asked Questions
How long do I have to file a car accident claim in Florida?
Deadlines apply. Missing one can end your right to sue. Contact the firm promptly so your options are reviewed in time.
Can I recover if I was partly at fault for the accident?
Florida’s shared-fault rules can reduce what you recover. In some situations, they can bar recovery entirely. Contact the firm to review how those rules apply to your accident.
What if the at-fault driver doesn’t have enough insurance?
You may be able to pursue an underinsured motorist (UIM) claim under your own policy. You may also be able to pursue other sources of recovery. A lawyer can advise you on these options.
Do I have to accept the insurance company’s first offer?
No. First offers are often low. You have the right to review and negotiate. Many claims settle for more than the first offer.
What if my injury is catastrophic or permanent?
Catastrophic injury claims can account for lifetime care, assistive equipment, and home changes. They can also account for lost earning ability and decades of pain and suffering. A free evaluation can help you understand what your claim involves.
About the Responsible Lawyer
Igor Hernandez is the responsible lawyer for this page. He is admitted to practice law in Florida and is admitted to The Florida Bar.
CHG Personal Injury Lawyers is a Florida-based personal injury firm. The firm serves people throughout Florida, including Miami, Orlando, Tampa, Jacksonville, Fort Lauderdale, and West Palm Beach.
If you were hurt in a car accident, reach out for a free, confidential first consultation. There is no obligation to continue.
CHG Personal Injury Lawyers can review your situation, explain your options, and give you a realistic sense of your claim. Contact us promptly, because deadlines apply.
What Shapes the Value of a Car Accident Claim
Your Injuries and Treatment
The type of injury, the care you need, and how your recovery is progressing all help show the full impact of the crash.
Medical Bills and Records
Clear, complete records of your treatment, prescriptions, and follow-up visits give a claim its factual foundation.
Lost Income and Work Limits
Time away from work, reduced hours, or a lasting change in your ability to earn a living are part of the picture.
Insurance and Fault
The available insurance coverage and the evidence about how the crash happened can affect how a claim is evaluated.
Be Careful With Early Offers
Insurance adjusters may contact you soon after a crash, sometimes with a quick offer. Before you sign a release or give a recorded statement, talk with a lawyer about what your claim may involve.
Questions to Bring to Your Free Consultation
What were the crash details?
Photos, police reports, witness names, and the location of the crash all help us understand what happened.
What treatment have you had?
Keep every doctor's note, bill, and receipt. Follow your doctors' care, and share your records with us.
Has anyone offered you money yet?
Bring any settlement letters or insurance communications so we can review them with you.