

Car Accident Claims
What Determines Your Car Accident Settlement?
Understanding the factors that affect your claim's value—and how to protect your recovery.
By CHG Lawyers · Published September 25, 2026
Average Settlement for Personal Injury Car Accidents: What Determines Your Claim’s Value
There is no single “average” car accident settlement that applies to everyone. Settlement amounts depend entirely on the severity of your injuries, your medical costs, lost wages, insurance coverage limits, and who was at fault. A minor fender-bender with soft-tissue damage may settle for $10,000, while a catastrophic spinal cord injury can result in a settlement worth millions. Understanding what drives your specific claim’s value is far more useful than chasing a headline number.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why There’s No Single “Average” Car Accident Settlement
The word “average” can be deeply misleading when it comes to car accident settlements. Settlements vary wildly based on injury type, severity, medical costs, lost income, and the at-fault driver’s insurance limits. A minor fender-bender with whiplash settles differently than a multi-vehicle crash with permanent disability.
When you see a statistic like “the average car accident settlement is $25,000,” that number obscures the real range. Some claims settle for $3,000; others for $3 million. Your settlement depends on your specific facts, not on what someone else received. The only meaningful comparison is between your case and cases with similar injury severity, medical documentation, lost wages, and liability clarity in your state.
Settlement Ranges by Injury Severity
Understanding where your injury falls on the spectrum helps you evaluate whether an offer is in the ballpark.
Minor injuries (whiplash, minor lacerations, short-term treatment): typically $5,000–$25,000. These cases involve minimal medical bills, no lost work time, and full recovery within weeks or a few months.
Moderate injuries (broken bones, significant soft-tissue damage, ongoing physical therapy): typically $25,000–$100,000. Recovery takes months; medical bills are substantial; some lost wages may apply.
Serious injuries (permanent scarring, chronic pain, significant lost wages, ongoing medical care) often involve effects that continue long after the accident. These injuries cause lasting effects on your ability to work and enjoy daily life.
Catastrophic injuries (spinal cord injury, paralysis, traumatic brain injury, amputation, severe burns) may involve claims that account for lifetime medical care, lost earning capacity, home modifications, assistive devices, and profound loss of quality of life. A person with paraplegia or quadriplegia faces decades of specialized care, and settlements account for that reality.
Wrongful death: varies widely based on the deceased’s age, earning capacity, and dependents. A young parent with decades of earning potential may generate a much larger claim than an elderly person without dependents.
How Settlement Amounts Are Calculated
Settlements break down into two main categories: economic and non-economic damages.
Economic damages are concrete, documented losses: medical bills (past and future), lost wages, rehabilitation costs, assistive devices (wheelchairs, braces, prosthetics), and home modifications (ramps, accessible bathrooms, specialized equipment). These are the easiest to calculate because receipts and pay stubs provide proof.
Non-economic damages are harder to quantify but no less real: pain and suffering, loss of enjoyment of life, emotional distress, disfigurement, and permanent disability. These reflect the human cost of your injury—the activities you can no longer do, the relationships affected, the dignity lost.
Insurers often use one of two methods to estimate non-economic damages:
- Multiplier method: a multiplier (typically 1.5–5×) applied to medical expenses. If your medical bills total $50,000 and the multiplier is 3, pain and suffering might be valued at $150,000.
- Per diem method: a daily rate assigned to pain and suffering for the duration of recovery. If your recovery takes 18 months and the per diem is $300 per day, pain and suffering totals $162,000.
Insurance policy limits often determine the ceiling of recovery. If the at-fault driver’s policy limit is $100,000 and your actual damages total $250,000, you can recover no more than $100,000 from their insurer (unless you have uninsured/underinsured motorist coverage on your own policy).
Is $50,000 a Good Settlement for a Car Accident?
It depends entirely on your injuries and losses. For a minor injury with low medical bills and no lost work time, $50,000 may be generous. For a serious injury with ongoing treatment and permanent effects, it may be far too low.
Ask yourself these questions before accepting any offer:
- Does it cover all my medical bills (past and future)?
- Does it compensate for lost income?
- Does it account for pain, suffering, and permanent changes to my life?
- If my injury worsens or complications arise, will I have recourse?
If you cannot honestly answer “yes” to each, the offer may not be fair. Once you sign a settlement release, you cannot pursue further claims for that injury, even if complications emerge months or years later. Do not let pressure or urgency rush you into an unfair deal.
What Injury Pays the Most in a Car Accident Settlement?
Catastrophic injuries—those causing permanent impairment or disability—command the highest settlements. Spinal cord injuries and paralysis (paraplegia or quadriplegia) often result in settlements in the millions, reflecting lifetime medical care, lost earning capacity, and profound loss of quality of life.
Traumatic brain injuries with cognitive or physical impairment, severe burns requiring ongoing treatment, and amputations similarly result in substantial awards. Wrongful death claims can also reach into the millions depending on the deceased’s age and earning potential.
The key: the greater the permanent impact on your life, the higher the claim’s value. An injury that ends your career or confines you to a wheelchair will command far more than an injury from which you fully recover.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Do Injections Increase Your Settlement?
Medical treatment—including injections—can support a higher settlement if it demonstrates the severity of your injury and the extent of your recovery efforts. Epidural steroid injections, joint injections, or other therapeutic procedures show that your injury required ongoing, specialized care beyond basic treatment.
However, the injection itself does not automatically increase your settlement. What matters is whether the treatment was medically necessary and whether it documents the nature and duration of your injury. Insurers may scrutinize the medical necessity of any treatment, so ensure your healthcare provider has documented why the injection was needed and what it accomplished.
Factors That Push Settlements Higher or Lower
Several factors influence what an insurer will offer:
Liability: Clear fault on the other driver increases your settlement; shared or disputed fault reduces it.
Insurance coverage: The at-fault driver’s policy limits often determine the ceiling; if they are underinsured, your recovery may be capped.
Medical documentation: Thorough, contemporaneous medical records strengthen your claim; gaps in treatment or delayed care can weaken it.
Lost income: Documented wage loss (pay stubs, tax returns, employer letters) directly increases economic damages.
Pre-existing conditions: An injury that worsens a prior condition may still be compensable, but insurers often argue for a lower value.
Time to resolution: Cases that settle quickly may receive lower offers; those that proceed toward trial often command higher settlements because the insurer faces greater risk and expense.
How Insurance Strategy and Coverage Limits Influence Settlements
The at-fault driver’s insurance company has a financial incentive to settle low and quickly. Your own uninsured/underinsured motorist (UM/UIM) coverage may provide additional recovery if the at-fault driver’s policy is insufficient. Medical payments (Med Pay) coverage on your own policy can cover treatment costs upfront, reducing pressure to settle quickly.
Demand letters, documentation of damages, and willingness to pursue litigation all influence what an insurer will offer. An insurer’s initial offer is rarely their best offer; negotiation is standard. Understanding your leverage—your medical records, lost wages, permanent effects, and the strength of liability—helps you negotiate fairly.
What You Should Know Before Accepting a Settlement
Once you sign a release, you cannot pursue further claims for that injury, even if complications arise later. This is permanent and irreversible.
Do not accept an offer without understanding your full damages: medical bills, lost wages, future treatment needs, and non-economic losses. If you have a serious or permanent injury, consult an attorney before accepting any offer; the cost of legal counsel is often far less than the difference between a low offer and a fair one.
Insurers count on injured people settling quickly and without guidance. Do not let urgency or pressure rush you into an unfair deal.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
Next Steps: Understanding Your Claim’s Value
Start by gathering all medical records, bills, and documentation of lost income. Write down how the injury has affected your daily life, work, and relationships. Research the typical range for injuries similar to yours in Florida, accounting for the specifics of your case.
If an insurer has made an offer, do not accept it without understanding whether it covers all your losses and accounts for permanent effects. For many car accident claims, the statute of limitations in Florida gives you two years from the date of injury to file a lawsuit, but claims against government entities or for medical negligence can have other deadlines or notice requirements, so do not wait to evaluate your claim.
Frequently Asked Questions
How much should I settle for in a car accident?
Settle only for an amount that covers all your documented economic damages (medical bills, lost wages, future care) plus fair compensation for pain, suffering, and permanent effects. If you’re unsure, consult an attorney before accepting.
How long does a car accident settlement take?
Simple cases may settle within weeks; complex cases with serious injuries can take months or years, especially if litigation is necessary.
What is the difference between economic and non-economic damages?
Economic damages are concrete losses (medical bills, lost wages); non-economic damages reflect human suffering (pain, emotional distress, loss of enjoyment of life).
Can I negotiate a car accident settlement offer?
Yes. An insurer’s first offer is rarely their final offer. Negotiation is standard and expected.
What happens if the at-fault driver is uninsured or underinsured?
Your own uninsured/underinsured motorist (UM/UIM) coverage may cover the gap, if you have it. If not, you may pursue the at-fault driver directly, though collecting from an individual is often difficult.
How does comparative fault affect my settlement?
In Florida, if you are found partially at fault, your recovery is reduced by your percentage of fault. Under Florida law, if you are found to be greater than 50% at fault for your own harm, you may not recover any damages.
If you’ve been injured in a car accident and received a settlement offer—or you’re unsure what your injuries are worth—reach out to discuss your specific situation. We’re here to help you understand your options.
Key Factors in Settlement Valuation
Economic Damages
Medical bills, emergency care, ongoing treatment, lost wages, and future medical needs form the foundation of your claim. Keep all receipts and records.
Pain and Suffering
Compensation for physical pain, emotional distress, and reduced quality of life. The severity and permanence of your injury matter here.
Liability and Fault
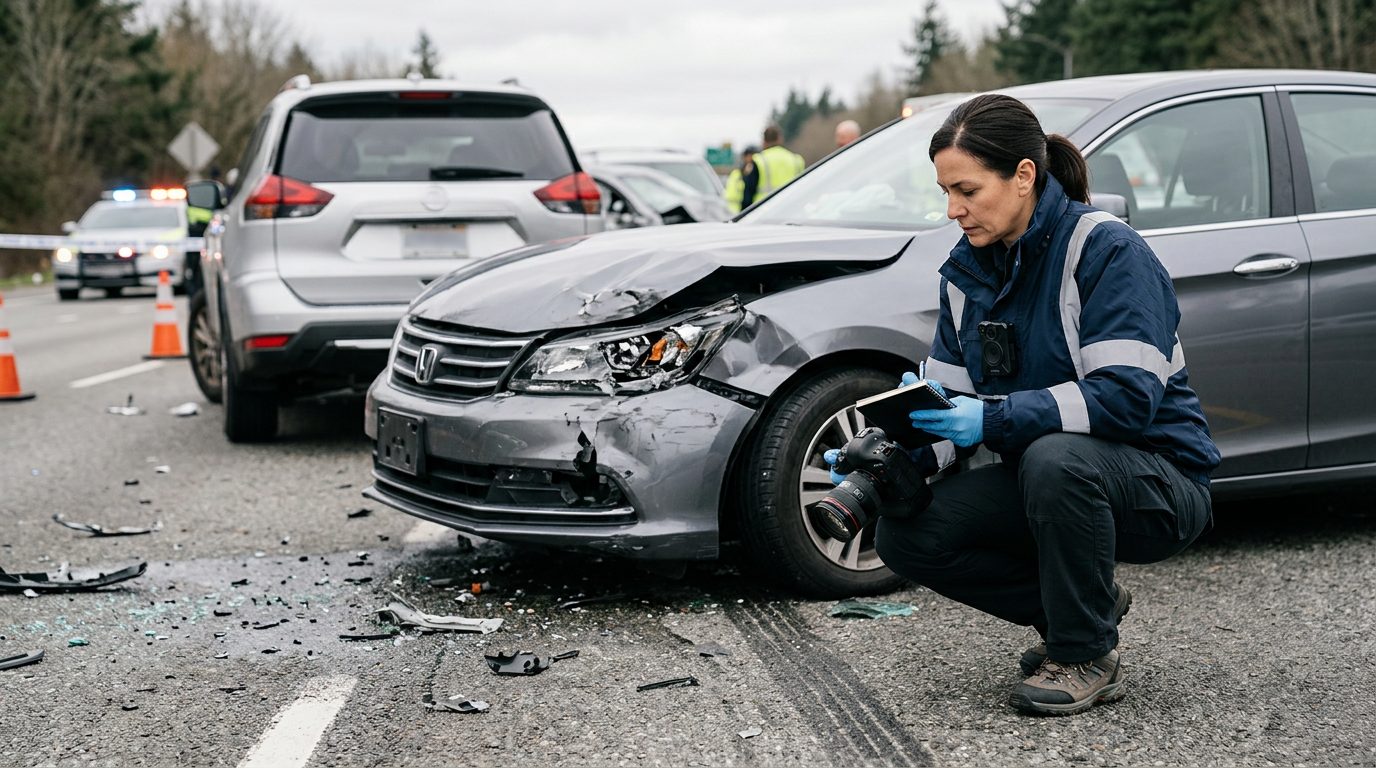
How clearly the other driver caused the crash affects settlement value. Evidence like police reports, witness statements, and photos strengthens your position.
Insurance Coverage
The at-fault driver's policy limits and your own coverage (uninsured/underinsured motorist protection) set the ceiling for recovery.
Permanent Injury or Disability
Long-term or permanent effects—chronic pain, scarring, reduced mobility, or cognitive changes—significantly increase claim value.
Negotiation and Timing
Early settlement offers are often low. An attorney can identify what your case is truly worth and push back against inadequate proposals.
Common Settlement Scenarios
Minor Injuries, Clear Liability
If you have minor injuries and the other driver is clearly at fault, settlement may come quickly—often within weeks. Your documented medical costs plus a reasonable pain-and-suffering multiplier typically drive the number.
Serious or Ongoing Injury
Significant injuries (fractures, back/neck damage, head trauma) take longer to settle because full recovery and long-term costs are still unknown. Waiting until you reach maximum medical improvement often yields a higher settlement.
Disputed Fault
When both drivers share blame, settlement is harder. Your state's comparative negligence rules and the strength of evidence determine how much you can recover (Fla. Stat. § 768.81(6)).
Catastrophic or Permanent Injury
Spinal cord injury, paralysis, amputation, traumatic brain injury, or severe burns warrant much larger settlements. These cases demand thorough documentation of lifetime care, lost earning capacity, and non-economic damages.
Don't Accept the First Offer
Insurance companies often open with a settlement far below what your claim is worth. Before you sign anything, understand your full damages—especially if your injury is serious or ongoing. An attorney can review the offer and advise whether it's fair.
Steps to Strengthen Your Settlement Claim
Document Everything
Keep medical records, bills, receipts, photos of the crash scene and vehicle damage, and a journal of your symptoms and recovery. This evidence directly supports your claim's value.
Follow Medical Advice
Complete all prescribed treatment and follow-up care. Gaps in treatment can be used to argue your injuries were minor. Consistency strengthens your credibility.
Avoid Social Media
Don't post about the accident, your injuries, or your recovery online. Insurance adjusters review social media and may use posts to minimize your claim.
Get a Professional Valuation
An attorney familiar with car accident claims can calculate what your case is worth based on comparable settlements, your injuries, and the facts of your crash.