

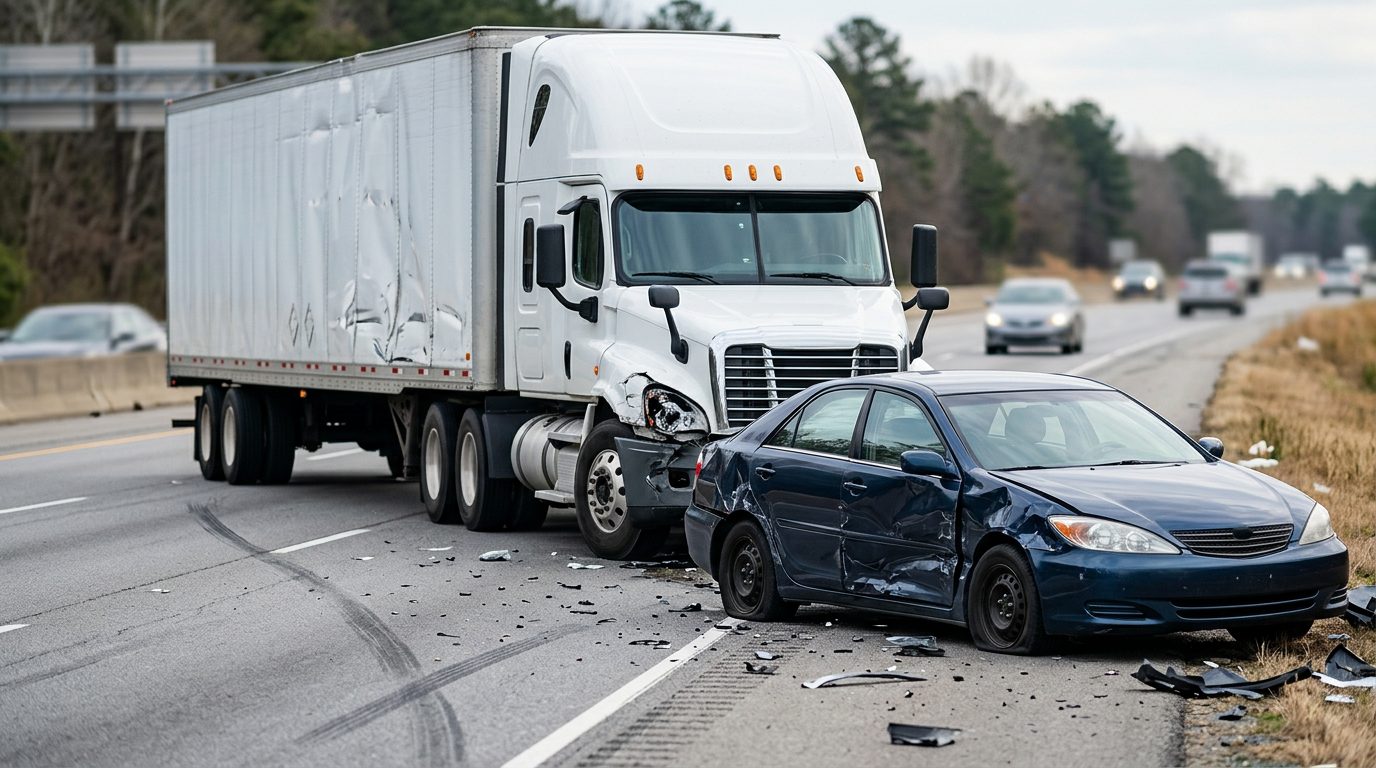
Car Accident Injuries
What Car Accident Settlements Really Look Like
Settlement amounts depend on injury severity, medical costs, lost income, and other factors. Learn what affects your claim's value.
By CHG Lawyers · Published September 08, 2026
Car Accident Settlement Amounts With Injury: What Your Claim May Be Worth
There is no single “average” car accident settlement. Settlement amounts vary widely. They depend on injury type, severity, medical costs, lost income, and who was at fault. Published averages mix minor injuries with catastrophic ones. This makes them misleading.
What matters is understanding what goes into a settlement and how it applies to your specific situation.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why “Average” Settlement Amounts Can Be Misleading
Published settlement ranges hide more than they show. Every car accident injury case is different.
A $25,000 settlement may be fair for a minor soft-tissue injury with low medical bills. It could be far too low for someone with a moderate fracture, ongoing treatment, and weeks of lost income.
The real question isn’t what the “average” is. It’s what your claim is worth based on your injury, medical costs, lost earnings, and liability evidence. When you understand those pieces, you can decide if an insurance offer is fair.
How Car Accident Settlements Are Calculated
Settlement value comes from several distinct parts:
Economic damages are measurable financial losses. These include medical bills (past and future), lost wages, rehabilitation costs, assistive devices, home modifications, and ongoing care. These are easiest to calculate because they’re documented.
Non-economic damages cover pain and suffering, emotional distress, loss of enjoyment of life, permanent scarring, or disfigurement. These have no receipt. They’re calculated differently—often as a multiple of economic damages.
Liability determines who pays. Under Florida’s comparative fault rule, if you are found partially at fault, your settlement is reduced by your percentage of fault. If you are more than 50% at fault, you typically recover nothing.
Insurance coverage and policy limits set a hard ceiling. Florida requires minimum liability coverage of $10,000 per person and $20,000 per accident for bodily injury. Many drivers carry only that minimum. Your settlement cannot exceed their policy limit, no matter how severe your injury.
Negotiation and leverage matter too. The strength of your medical documentation, police reports, witness statements, and expert testimony all influence what an insurance company will pay.
Settlement Ranges Based on Injury Severity
These ranges are illustrative only. Your case may fall outside them based on specific facts.
Minor injuries (soft tissue, minor fractures, brief recovery): typically $5,000–$25,000. Medical costs are low, lost time is short, and recovery is complete.
Moderate injuries (significant fractures, several weeks or months of treatment, some ongoing care): $25,000–$100,000. Medical bills are substantial. Lost wages add up. There may be residual pain or reduced function.
Severe injuries (permanent impairment, ongoing medical care, lost earning capacity): $100,000–$500,000 or more. The injured person may not return to their prior job. They may need lifetime care or vocational rehabilitation.
Catastrophic injuries (spinal cord injury, paralysis, traumatic brain injury, amputation, severe burns): $500,000 to millions. These injuries cause permanent, life-altering impairment. Lifetime care costs—nursing, medical equipment, home modifications, assistive technology—are the primary driver. Age and remaining earning capacity also matter significantly.
How Much Can You Get for Pain and Suffering?
Pain and suffering (non-economic damages) is often calculated as a multiple of your economic damages. The typical range is 1.5 to 5 times, depending on injury severity.
A minor injury might support a 1.5× multiplier. A severe, permanent injury might support 4× or 5×.
There is no fixed formula. Judges and juries have discretion. Insurance companies, however, often resist high pain-and-suffering claims. They may offer less than what a court might award. That’s why understanding what your injury is worth—and being willing to pursue a claim if the offer is too low—gives you negotiating power.
Key Factors That Influence Your Settlement Amount
Injury type and permanence matter most. A temporary injury settles for less than a permanent one. Paralysis, traumatic brain injury, or amputation command higher settlements because they’re life-altering.
Medical documentation is critical. Clear, detailed records of diagnosis, treatment, and prognosis strengthen your claim. Vague or incomplete records weaken it. Learn how to document injuries for insurance.
Lost income and earning capacity are especially important in catastrophic cases. If you cannot return to work, your lost earnings are calculated over your remaining working life. This is a significant number for younger injured persons.
Age and life expectancy affect settlement value in catastrophic cases. A 30-year-old with a spinal cord injury has 30+ years of care ahead. A 65-year-old has fewer. Younger injured persons typically receive higher settlements.
Liability clarity matters. If the other driver was clearly at fault, settlement is straightforward. If liability is disputed or you share some fault, settlement may be lower.
Insurance policy limits set the ceiling. If the at-fault driver’s coverage is $10,000 and your injury is worth $100,000, you’re capped at $10,000 from their policy. Uninsured or underinsured motorist coverage on your own policy may help.
Strength of evidence can move the needle significantly. Photos of the accident scene, witness statements, police reports, and expert testimony all strengthen your position.
Is $50,000 a Good Settlement for a Car Accident?
It depends entirely on your injury and the facts of your case.
For a minor injury with low medical bills and no lost income, $50,000 may be generous. For a moderate or severe injury with ongoing treatment and lost earning capacity, $50,000 may be far too low.
The only way to know if an offer is fair is to understand what your case is actually worth. That requires honest assessment of your damages (economic and non-economic) and the strength of liability evidence.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
How Much of a Settlement Will I Actually Receive?
Settlement proceeds are reduced before you receive them. Here’s what typically comes out:
Attorney fees are usually 33–40% of the settlement under a contingency agreement (you pay nothing upfront; your attorney takes a percentage of what you recover).
Medical liens allow healthcare providers to claim a portion of your settlement to recover costs they paid for your treatment.
Subrogation claims allow your health insurance or auto insurance to recover what they paid toward your medical care.
Outstanding medical bills and other debts may be paid from the settlement.
Example: A $100,000 settlement minus 33% attorney fee ($33,000) and $10,000 in medical liens leaves approximately $57,000 to you. Your attorney should explain all deductions upfront.
Catastrophic Injury Settlements: What Changes
Spinal cord injuries, paralysis, traumatic brain injury, amputation, and severe burns often result in settlements of $500,000 to millions. Here’s why:
Lifetime care costs are enormous. Nursing, rehabilitation, assistive technology, home modifications, medical equipment, and ongoing treatment can total hundreds of thousands of dollars over a lifetime.
Lost earning capacity is calculated over the injured person’s remaining working life. A 35-year-old who cannot work again has 30 years of lost income ahead. That’s a substantial number.
Younger injured persons receive higher settlements because of longer life expectancy and greater lost-earnings potential.
Structured settlements are common in catastrophic cases. Instead of a lump sum, the injured person receives payments over time. This ensures long-term care funding.
In catastrophic-injury cases, medical documentation, expert testimony about lifetime care needs, and clear liability evidence are critical to achieving fair settlements.
Insurance Coverage and Policy Limits
Florida requires minimum liability coverage of $10,000 per person and $20,000 per accident for bodily injury. Many drivers carry only that minimum.
If the at-fault driver has low coverage and your injury is severe, you may not recover the full value of your claim from their policy. That’s where uninsured or underinsured motorist coverage (on your own policy) becomes important. It can provide additional recovery if the at-fault driver’s coverage is insufficient.
Commercial truck drivers often carry higher liability limits, which can support larger settlements in truck accident cases.
Comparative Fault and Settlement Reduction
Under Florida’s comparative fault rule, if you are found partially at fault, your settlement is reduced by your percentage of fault.
Example: If you are 20% at fault for a $100,000 settlement, you recover $80,000. If you are more than 50% at fault, you recover nothing.
Insurance companies often argue for higher comparative fault percentages to reduce their payout. Clear evidence of the other driver’s negligence strengthens your settlement position. Witness statements, police reports, and traffic camera footage all help.
When Should You Accept a Settlement vs. Pursue a Lawsuit?
Settlement offers should be evaluated against the likely outcome at trial. Consider legal costs, time, and uncertainty. Working with a personal injury attorney can help you weigh these factors.
If liability is clear and damages are well-documented, a settlement may be preferable to the risk and expense of trial. If the insurance company’s offer is significantly below what your case is worth, pursuing a lawsuit may be justified.
An attorney can help you weigh the offer against your case’s actual value and advise whether settlement or litigation makes sense for your situation.
Statute of Limitations: Your Time Window
You have a limited window to file a claim. Under Florida law, the statute of limitations for personal injury actions is 2 years from the date the cause of action accrues. This means you have 2 years from the date of the accident to file a lawsuit. After that, your claim is barred.
Settlement negotiations can happen within that window, but don’t wait until the deadline approaches.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
Understanding Your Specific Settlement Value
Every car accident injury case is unique. Settlement value depends on facts specific to your situation: your injury type and severity, your medical costs, your lost wages, your age, your earning capacity, the clarity of liability, and the strength of your evidence.
If you have been injured in a car accident and are unsure whether an insurance offer is fair—or if you haven’t yet contacted the at-fault driver’s insurance—reaching out to discuss your case can clarify what your claim may actually be worth. Learn about the car accident claim process to understand what comes next.
FAQ
What is considered a catastrophic injury in a car accident?
Catastrophic injuries include spinal cord injury, paralysis (paraplegia or quadriplegia), traumatic brain injury, amputation, and severe burns. These are injuries that cause permanent impairment or loss of function and require lifetime care.
How is pain and suffering calculated?
Pain and suffering is typically calculated as a multiple (1.5 to 5 times) of your economic damages, depending on injury severity and permanence. There is no fixed formula. Judges and juries have discretion.
What if the at-fault driver has no insurance?
Uninsured motorist coverage on your own policy may provide recovery. If you don’t have that coverage, your options are limited. You may need to pursue the at-fault driver directly, which is often difficult if they have few assets.
How long does a car accident settlement take?
Minor cases may settle within weeks or months. Severe or catastrophic cases often take 6 months to 2+ years, especially if litigation is necessary. The complexity of your injury and the strength of liability evidence affect the timeline.
Can I negotiate a higher settlement offer?
Yes. If an insurance company’s offer is below what your case is worth, you can counter-offer or provide additional evidence. You can also pursue a lawsuit. Learn about insurance settlement negotiation tips to strengthen your position.
Do I have to pay taxes on a car accident settlement?
Generally, no. Personal injury settlements are not taxable income under federal law. However, interest on delayed payments may be taxable. Consult a tax professional for your specific situation. “`
Factors That Shape Settlement Value
Medical Expenses
Emergency care, surgery, hospital stays, rehabilitation, ongoing treatment, and assistive devices all factor into what your claim is worth. Catastrophic injuries—like spinal cord damage or traumatic brain injury—often involve years of medical care and lifetime support.
Lost Wages & Earning Capacity
If the accident forced you to miss work or ended your ability to earn, that loss is part of your settlement. For permanent injuries, lost earning capacity over your lifetime can be substantial.
Pain, Suffering & Quality of Life
Compensation accounts for physical pain, emotional trauma, reduced mobility, loss of independence, and diminished enjoyment of life. More severe injuries typically result in higher pain-and-suffering awards.
Liability & Fault
How clearly the other driver caused the crash affects settlement value. Clear negligence strengthens your claim; shared fault may reduce it. Evidence—police reports, witness statements, photos—matters.
Why Settlement Amounts Vary Widely
Injury Severity
A minor whiplash claim settles differently than a spinal cord injury or amputation. Permanent, life-altering injuries command higher settlements because they demand lifetime care and support.
Documentation & Evidence
Medical records, imaging, expert testimony, and accident reconstruction reports strengthen your case. The clearer the evidence of injury and fault, the stronger your settlement position.
Insurance Coverage
The at-fault driver's policy limits cap what you can recover from their insurer. Underinsured motorist coverage or your own policy may provide additional recovery options.
Negotiation & Legal Representation
Insurers often offer less than a claim is worth. An attorney focused on catastrophic injury can identify all damages, counter low offers, and pursue fair compensation on your behalf.
Don't Accept the First Offer
Insurance companies frequently undervalue claims, especially those involving serious or permanent injuries. Before settling, understand the full scope of your damages—medical costs, lost income, and long-term care needs. A low initial offer may not cover years of treatment or lost earning power.
Common Settlement Ranges by Injury Type
Minor Injuries (Soft Tissue)
Sprains, strains, and whiplash typically settle for $5,000–$25,000, depending on medical costs and lost time. Recovery is usually complete within weeks or months.
Moderate Injuries (Fractures, Significant Lacerations)
Broken bones, deep cuts, and injuries requiring surgery often settle for $25,000–$100,000 or more. Medical bills and recovery time are substantial but healing is expected.
Severe Injuries (TBI, Spinal Cord Damage, Amputation)
Catastrophic injuries—traumatic brain injury, paralysis, limb loss, severe burns—frequently settle for $100,000 to several million dollars. Lifetime medical care, lost earning capacity, and permanent disability drive these higher values.
Wrongful Death
Fatal accidents result in claims for funeral costs, lost financial support to the family, and loss of companionship. Settlements vary widely based on the deceased's age, earning potential, and family circumstances.
Time Matters
Evidence fades, witness memories dim, and there are legal time limits for filing claims. The sooner you document your injuries and consult an attorney, the stronger your position. Don't delay.