
Car Accidents | Serving Florida
How Much Do Car Accident Settlements Pay in Florida?
Every claim is different. Here is how Florida car accident settlements are shaped, what drives the value of your case, and how the CHG Personal Injury Lawyers team can help you understand your options.
Why Floridians Call Our Firm
Florida
Florida-based personal injury firm
Free
Confidential first consultation
No Fee
Unless there is a recovery
By CHG Lawyers · Published November 2, 2026
How Much Do Personal Injury Settlements Pay for Car Accidents in Florida?
If you are deciding whether a settlement offer is fair, you do not have to sort it out alone. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Much Personal Injury Settlements Pay for Car Accidents in Florida: Factors and Deadlines
There is no single answer. The amount depends on several things. These include:
- Your medical costs
- Your lost income
- How lasting your injuries are
- Who was at fault
- How much insurance is available
This guide explains each factor. It also explains the Florida rules that shape them. It is written for injured drivers, passengers, pedestrians, and families.
CHG Personal Injury Lawyers is a Florida-based firm. We represent people throughout Florida. That includes Miami, Orlando, Tampa, and Jacksonville. Igor Hernandez, one of the firm’s lawyers, is responsible for this page.
Who This Guide Is For and What a Settlement Covers
A settlement is a negotiated payment. It ends an injury claim. This usually happens without a trial. The injured person accepts the payment instead of taking the claim further.
A car accident settlement can cover several kinds of loss:
- Medical bills, both past and future
- Lost wages and lost ability to earn money later
- Pain, suffering, and loss of enjoyment of life, when Florida’s injury threshold is met (a minimum injury standard, explained later in this guide)
- Vehicle damage, which is often handled through a separate property claim
If a crash causes a death, the family may bring a wrongful-death claim. Florida requires court approval for some settlements while the case is pending.
- A surviving family member objects to the amount.
- A surviving family member objects to how the money is split among the beneficiaries.
- A minor or an incompetent survivor (someone who cannot legally manage their own affairs) is affected.
See § 768.25.
The statute reads: “While an action under this act is pending, no settlement as to amount or apportionment among the beneficiaries which is objected to by any survivor or which affects a survivor who is a minor or an incompetent shall be effective unless approved by the court.” Fla. Stat. § 768.25
In plain words, the court must approve these settlements before they take effect.
Families facing this kind of loss need patient, careful guidance. You can learn more about wrongful-death claims.
Why There Is No Single Average Settlement Number
No single average applies. Every crash and every injury is different. Online averages mix very different cases together. Because of this, they tell you little about your own claim.
A short fender-bender with a few weeks of treatment is not the same as a crash that causes lasting limits. Five factors drive a claim’s value:
- Medical costs and records. What treatment you needed, what it cost, and whether records tie it to the crash.
- Lost income. Time missed from work now, and any lasting loss of earning ability.
- Injury severity and permanence. Whether the injury heals or lasts.
- Degree of fault. Who caused the crash, and by what share.
- Insurance limits. How much coverage the at-fault party and your own policies carry.
Documents shape how a claim is judged. Police reports, photos, medical records, bills, and wage statements show what happened and what it cost. Missing records often slow negotiations. Keep copies of everything you receive.
Florida PIP: How the No-Fault Layer Works
Florida has a no-fault system. It pays personal injury protection (PIP) benefits for many injuries from a car crash.
See § 627.733. The rules sit within the Florida Motor Vehicle No-Fault Law.
The law may be cited and known as the Florida Motor Vehicle No-Fault Law, which covers Sections 627.730-627.7405.
Under § 627.737, a covered owner or driver is exempt from tort liability for bodily injury from the crash, but only to the extent that PIP benefits are payable for that injury. Tort liability means being sued for personal injury damages. Fla. Stat. § 627.737 reads: “unless a person is entitled to maintain an action for pain, suffering, mental anguish, and inconvenience for such injury under the provisions of subsection (2).”
This exemption applies to the extent PIP benefits are payable, or would be payable but for an exclusion authorized by the No-Fault Law. Fla. Stat. § 627.737 reads: “unless a person is entitled to maintain an action for pain, suffering, mental anguish, and inconvenience for such injury under the provisions of subsection (2).” It does not apply when the injury meets the threshold for pain and suffering damages. See § 627.737.
Follow your doctor’s care. Medical decisions belong to you and your doctors. Do not delay treatment because of a claim question. Some people wait to see whether symptoms fade. A prompt medical checkup also creates a record of your injuries.
How Florida Fault Rules Affect What You Can Recover
Florida uses a comparative fault rule (Fla. Stat. § 768.81(6)). If you are more than 50% at fault for your own harm in a negligence case, you cannot recover damages at all. Fla. Stat. § 768.81 reads: “This subsection does not apply to an action for damages for personal injury or wrongful death arising out of medical negligence pursuant to chapter 766.”
This rule does not apply to personal injury or wrongful death claims that arise from medical negligence under chapter 766. See § 768.81.
Florida also does not make each defendant pay the whole amount. A court enters judgment against each liable party based on its own percentage of fault.
Lawyers call the alternative “joint and several liability.” Under that rule, one party can be made to pay the full amount. Florida generally does not use it this way, except for causes of action where joint and several liability is specifically provided by chapter 403, chapter 498, chapter 517, chapter 542, or chapter 895, and the apportionment rule does not apply to actions based upon an intentional tort or to actual economic damages from pollution. Put simply, each party pays its own share. See § 768.81.
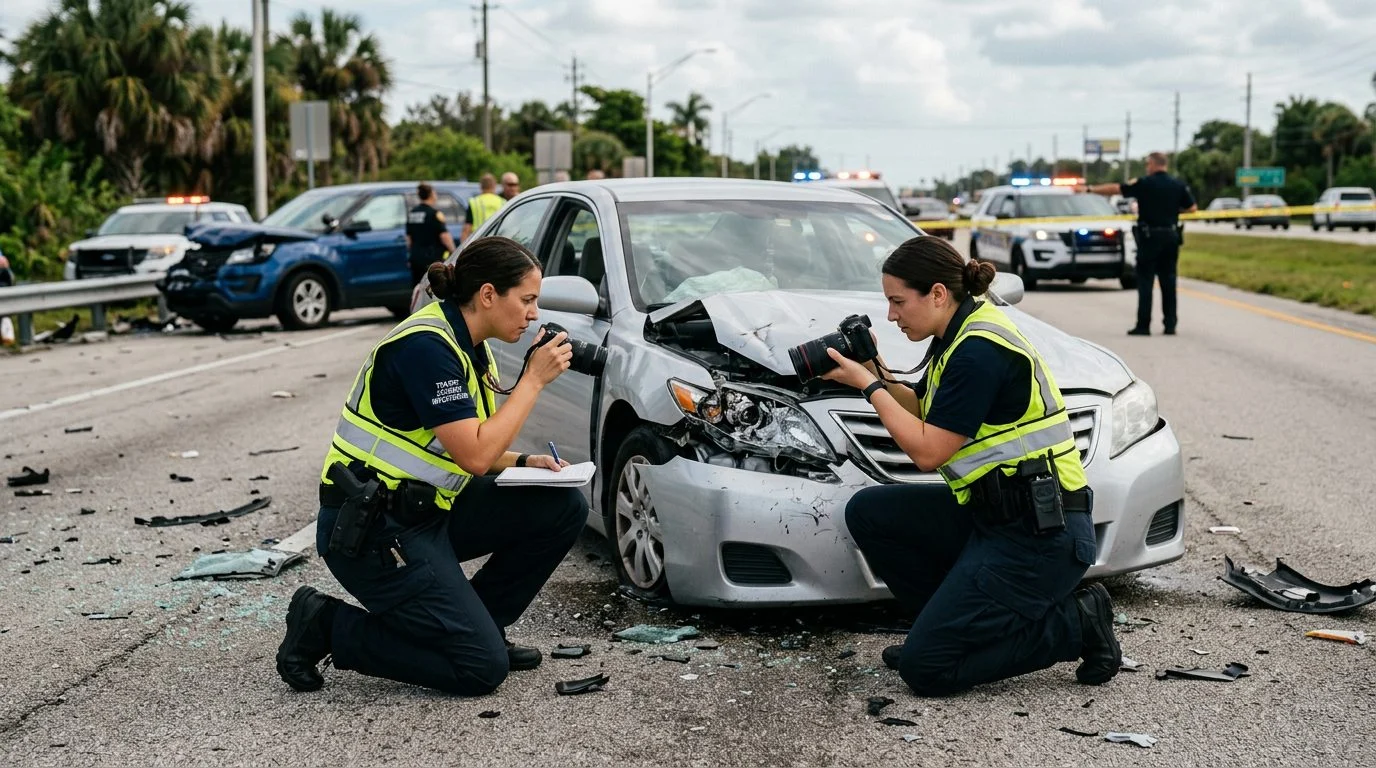
Insurers often dispute fault. Photos, witness statements, scene measurements, and crash data can help show what happened.
Several parties can share responsibility for one crash. A commercial truck company, a rideshare company, or another driver may each play a role. Settling with one party does not release the others who may be liable for the same harm. See § 768.041.
Understand who else may be responsible before you sign any release.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Serious Injuries Change the Value of a Claim
Serious injuries usually raise a claim’s value. They bring larger medical costs. They also bring longer lost income and lasting limits on daily life.
Catastrophic injuries can require lifetime medical care. Examples include spinal cord injuries, paralysis, traumatic brain injuries, amputations, and severe burns. These injuries may also need:
- Medical equipment made for the person’s needs
- Changes to the home
- Long-term help with daily tasks
Florida limits pain and suffering damages in motor vehicle cases. You may recover them only if your injury includes one of the following:
- A significant and permanent loss of an important bodily function
- A permanent injury within a reasonable degree of medical probability, other than scarring or disfigurement
- Significant and permanent scarring or disfigurement
- Death
See § 627.737.
Future care and lost earning capacity often carry the most weight. These projections rest on records and opinions from treating physicians and other qualified professionals. Families often provide daily care that is hard to measure. That burden deserves a clear place in the claim.
From Consultation to Settlement: The Process and Timeline
Your first step is a free, confidential first consultation. There is no obligation to continue.
After that, a claim usually moves through three stages:
- Investigation. Our team collects the records.
- Demand to the insurer. The claim goes to the insurer with supporting records.
- Negotiation. Talks can take months.
Here is how each step works:
- Free first consultation. You share the crash facts, your injuries, and your treatment. Nothing you say obligates you to continue.
- Investigation and records. Our team collects police reports, medical records, bills, and wage documents. Florida law requires a liability insurer to give a sworn statement of its policy limits within 30 days of a written request. See § 627.4137.
- Demand and negotiation. The claim goes to the insurer with supporting records. Talks can take months. The length depends on your treatment and how the insurer responds.
- Settlement or lawsuit. If an offer fairly reflects the claim, the case may settle. If it does not, a lawsuit may be the next step.
Timelines vary widely. They depend on how long your medical recovery takes and how quickly insurers respond. CHG charges no attorney’s fees and no case costs unless there is a recovery.
Frequently Asked Questions About Florida Car Accident Settlements
Settlement value depends on the facts of each claim. No single figure answers these questions.
Is a $30,000 or $50,000 settlement good?
Whether an offer is fair depends on several things. These include medical costs, lost income, permanence, fault, and insurance limits. A dollar figure alone cannot show whether it reflects your claim.
How much of a settlement do I keep?
Collateral sources include health coverage. This applies unless the source has a subrogation or reimbursement right.
Subrogation means the payer can seek repayment from your award. Medicare, Medicaid, and workers’ compensation are not treated as collateral sources. See § 768.76.
A letter of protection is an agreement. In it, a provider agrees to wait for payment until the case settles. See § 768.0427.
What is the deadline to file?
Florida sets filing deadlines by statute. For some claims, the deadline can be as short as two years. See § 95.11.
Deadlines apply to your claim. Contact us promptly.
Do I need to go to court?
Many claims resolve through negotiation. Some move into a lawsuit when a fair offer is not made.
Can I recover pain and suffering damages?
Possibly. It depends on whether your injury meets Florida’s threshold for motor vehicle claims. See § 627.737.
Talk to a Florida Car Accident Lawyer About Your Claim
If you are deciding whether a settlement offer is fair, you do not have to sort it out alone. Our team can review with you:
- The crash
- Your injuries
- Your PIP timing
- The at-fault insurance limits
Igor Hernandez and our team of licensed attorneys offer a free, confidential first consultation. There is no obligation to continue.
Florida deadlines apply. Early contact protects your options. Contact CHG Personal Injury Lawyers to start.
What Shapes the Value of a Car Accident Claim
Medical Costs
Past and future treatment, including emergency care, surgery, therapy, and medication, is a central part of any claim.
Lost Income
Time away from work and reduced ability to earn in the future can be part of how a claim is valued.
Lasting Effects
Permanent injuries, scarring, and changes to daily life often affect a claim far more than short-term symptoms.
Insurance Limits
The available insurance coverage on each side can affect what settlement discussions look like.
Before You Accept Any Offer
An early settlement offer may arrive before the full extent of your injuries is known. Follow your doctors' care, keep records of your treatment and expenses, and talk with a lawyer before you sign a release or accept a payment.
Questions Florida Families Ask Most
Is a $30,000 or $50,000 offer good?
Whether an offer is fair depends on medical costs, lost income, permanence of injuries, fault, and insurance limits. A dollar figure alone cannot show whether it reflects your claim.
How much of a settlement do I keep?
Certain sources of payment, such as health coverage, may affect what remains after medical bills and other obligations are addressed. Our team can walk you through how this applies to your situation.
Does a settlement always mean a lawsuit?
Many car accident claims are resolved through negotiation with insurers. Some require a lawsuit. The path depends on the facts of your case and the parties involved.
What should I do first?
Seek medical care, keep copies of every record and bill, and contact a lawyer promptly so your claim can be reviewed while the details are still clear.