

Slip and Fall Claims
What Is Your Slip and Fall Settlement Worth?
Understand how damages are calculated and what you may recover for your injury.
By CHG Lawyers · Published October 03, 2026
A slip and fall settlement is money paid by the property owner’s insurance company to resolve your injury claim without going to trial. It covers your documented losses—medical bills, lost wages, pain and suffering, and ongoing care—and gives you a faster, more certain outcome than litigation.
If you fell on someone else’s property and were injured because the owner failed to maintain safe conditions or warn of hazards, you may be entitled to compensation. This guide explains what settlements cover, what determines their value, and what you can realistically expect to receive.
What a Slip and Fall Settlement Covers
Your settlement compensates you for all losses caused by your injury. These include:
- Medical expenses: emergency room visits, hospital stays, surgery, physical therapy, ongoing treatment, medications, and medical equipment
- Lost wages: income you missed while recovering or unable to work
- Pain and suffering: compensation for physical pain, emotional distress, and reduced quality of life
- Permanent disability or scarring: additional damages if your injury causes long-term impairment
- Future medical care: ongoing treatment or therapy your injury will require
- Reduced earning capacity: if your injury limits your ability to earn in the future
The foundation of every settlement is your documented medical expenses. Everything else builds from there.
If you fell on someone else's property and were injured because they failed to maintain safe conditions, you may have a claim—and our team can evaluate it at no cost. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Average Slip and Fall Settlement Amounts: What to Expect
Settlement values depend entirely on injury severity, medical documentation, and how strong the evidence is against the property owner. Here’s what cases typically look like:
- Minor injuries (sprains, minor fractures, small cuts): $2,000–$10,000
- Moderate injuries (broken bones, significant cuts, soft tissue damage): $10,000–$50,000
- Serious injuries (multiple fractures, head injury, permanent scarring, significant time off work): $50,000–$200,000+
- Catastrophic injuries (spinal cord injury, paralysis, amputation, traumatic brain injury, severe burns): $200,000–$1,000,000+
- Wrongful death: highly variable, depends on age, earning potential, and family circumstances
These are ranges based on typical cases, not promises. Your settlement depends on your specific facts: how clear the property owner’s fault is, how severe your injury is, your medical records, your lost income, and your age and earning potential.
What Makes a Settlement Valuable: Six Key Factors
Settlement value increases when you have strong evidence of the property owner’s negligence and clear proof of your injury’s severity.
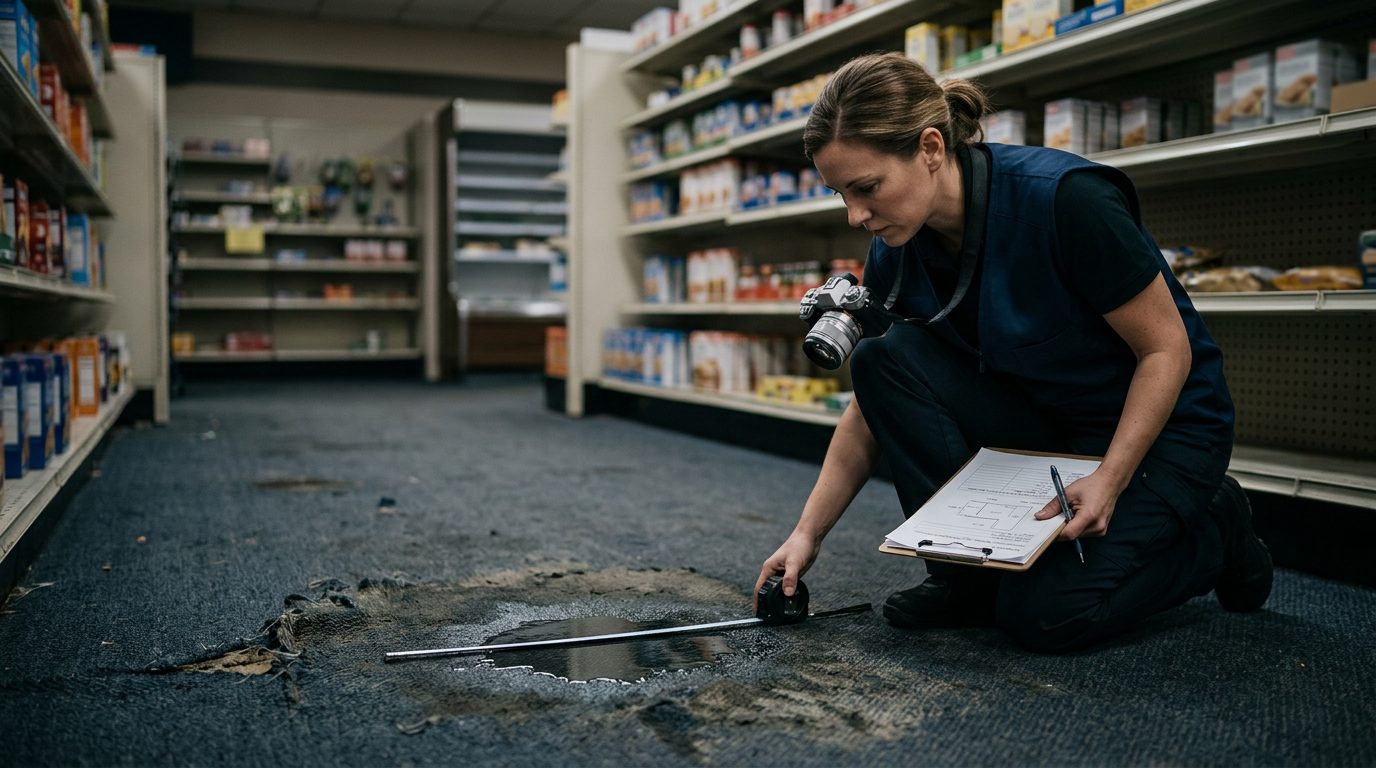
Clear negligence by the property owner means you can show they knew or should have known about the hazard and failed to fix it or warn you. Evidence includes maintenance records showing neglect, prior complaints from other customers, or photos of the dangerous condition.
Documented medical treatment is essential. Hospital records, imaging (X-rays, MRI, CT scans), surgical reports, and ongoing physical therapy prove your injury is real and serious. Gaps in treatment reduce settlement value.
Long-term disability or scarring increases damages significantly. Permanent impairment—chronic pain, reduced mobility, visible scarring—means higher compensation than injuries that fully resolve.
Strong evidence of the hazard includes photos of the dangerous condition, witness statements, and maintenance records showing the property owner ignored the problem. This strengthens liability.
Lost wages and reduced earning capacity are concrete, easily documented losses. Pay stubs, employer verification, and medical records showing you cannot return to your previous job all increase settlement value.
Prior complaints or incidents at the same location are powerful. If others were injured at the same spot, it proves the property owner knew about the hazard and did nothing.
How Settlement Value Is Actually Calculated
Insurance companies use a formula to value your claim:
- Start with medical expenses: all documented bills and the cost of future care
- Apply a multiplier: multiply medical bills by 1.5 to 5, depending on injury severity and liability strength (minor injuries get 1.5×; catastrophic injuries get 4–5×)
- Add lost wages: calculated from pay stubs and employer records
- Add pain and suffering: based on injury type, recovery duration, permanent effects, and jury verdict trends in your area
- Assess liability: how clear is the property owner’s fault? Stronger liability = higher settlement
- Check insurance limits: the property owner’s policy may cap the available payout
Example: A moderate injury with $8,000 in medical bills, $5,000 in lost wages, and clear liability might settle for $8,000 × 3 (multiplier) + $5,000 = $29,000.
How Much Will You Actually Take Home?
A settlement’s gross amount isn’t what you receive. Several deductions come first:
- Attorney contingency fee: typically 25–40% of the settlement (you pay nothing upfront)
- Medical liens: healthcare providers or insurance may claim a portion to recoup treatment costs
- Court costs and expert witness fees: typically $1,500–$5,000
- Outstanding medical bills: may be paid directly to providers
Example: A $100,000 settlement – Attorney fee (33%): $33,000 – Remaining: $67,000 – Costs and liens: $8,000–$15,000 – Your net: approximately $52,000–$59,000
Example: A $20,000 settlement – Attorney fee (33%): $6,600 – Remaining: $13,400 – Costs and liens: $1,500–$3,000 – Your net: approximately $10,400–$11,900
Smaller settlements have proportionally higher deductions, which is why injury severity and liability strength matter so much.
Is It Worth Suing for a Slip and Fall?
Yes, if you have:
- Clear liability: the property owner’s negligence caused your injury
- Documented medical treatment: records prove your injury is real and quantifiable
- Damages that exceed the cost of pursuing the claim: attorney fees and costs are typically recovered from the settlement
- Financial need: you cannot afford to pay your medical bills or lost wages
No, if:
- Liability is unclear: you were partly at fault, or the hazard was obvious
- Your injury is very minor: settlement value may not justify the time and cost
An attorney can evaluate your specific situation and advise whether a claim makes financial sense.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Timeline: How Long Does a Settlement Take?
Most slip and fall cases settle within 6–12 months:
- Investigation and demand (2–4 months): gathering medical records, photos, witness statements, and liability evidence
- Insurance negotiation (1–3 months): back-and-forth offers and counteroffers
- Settlement agreement (2–4 weeks): finalizing paperwork and release documents
- Payment (2–4 weeks after signing): insurance processes the check
If settlement fails, litigation can take 1–3 years or more. Most cases settle before trial.
Florida’s Statute of Limitations: Act Quickly
In Florida, you have two years from the date of your injury to file a personal-injury claim. After that deadline, you lose your right to sue. Evidence also fades, and witnesses become harder to locate. Contact an attorney as soon as possible after your injury.
Comparative Fault: What If You Were Partly at Fault?
Florida follows modified comparative fault: if you’re found 50% or less at fault, you can still recover—but your settlement is reduced by your percentage of fault. If you’re found more than 50% at fault, you recover nothing.
Example: You slip on a wet floor you didn’t see. If the property owner failed to place a wet-floor sign and you’re found 20% at fault, your $50,000 settlement is reduced to $40,000.
Steps to Maximize Your Settlement
- Seek immediate medical attention: document your injury with hospital or urgent care records
- Report the incident: notify the property owner in writing; request an incident report
- Gather evidence: take photos of the hazard, the scene, and your injuries; collect witness contact information
- Keep detailed records: save all medical bills, receipts, pay stubs, and communication with the property owner
- Follow medical advice: complete all prescribed treatment; gaps in care reduce settlement value
- Avoid social media: do not post about your injury or recovery; insurance companies monitor your online activity
- Do not settle quickly: initial offers are often low; allow time for negotiation
- Hire an attorney: experienced representation typically results in significantly higher settlements
Frequently Asked Questions
Q: Do I have to go to court to get a settlement?
A: No. Most slip and fall cases settle through negotiation with the insurance company. You only go to court if settlement fails.
Q: How long do I have to file a claim?
A: In Florida, you have two years from the date of injury. Act quickly.
Q: Can I settle if I was partly at fault?
A: Yes, but your recovery is reduced by your percentage of fault under Florida’s comparative negligence rules.
Q: What if the property owner doesn’t have insurance?
A: You may still have a claim against the owner personally, though collection can be difficult. An attorney can advise on your options.
Q: Do I need an attorney to settle my claim?
A: You can negotiate alone, but an attorney typically recovers significantly more than the cost of representation.
Q: What if I’m still treating for my injury?
A: You can still settle; the settlement includes compensation for future medical care based on medical opinion about your prognosis.
If you fell on someone else's property and were injured because they failed to maintain safe conditions, you may have a claim—and our team can evaluate it at no cost. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Why Choose CHG Personal Injury Lawyers
We focus exclusively on personal-injury claims, including slip and fall cases, across Florida and nationwide. Our team includes licensed Florida Bar attorneys with years of experience evaluating and negotiating these cases.
We work on contingency: you pay nothing unless we recover for you. We handle all communication with insurance companies, gather evidence, and build a strong liability case. We provide honest assessments of your claim and realistic settlement expectations.
We serve English and Spanish-speaking clients throughout Florida and beyond. When you contact us, you get a free case evaluation with no obligation.
If you fell on someone else’s property and were injured because they failed to maintain safe conditions, you may have a claim—and our team can evaluate it at no cost. Contact CHG Personal Injury Lawyers for a free case evaluation.
What We Consider When Valuing Your Claim
Medical Costs
Emergency care, hospitalization, surgery, physical therapy, medications, and ongoing treatment—past and future.
Lost Wages
Income you lost while recovering, and earning capacity if your injury prevents you from returning to work.
Pain and Suffering
Compensation for physical pain, emotional distress, and reduced quality of life caused by your injury.
Liability and Negligence
Whether the property owner knew or should have known about the hazard and failed to fix it or warn you.
How Slip and Fall Settlements Work
Gather Evidence
Document the scene with photos, collect witness contact information, report the incident to the property owner, and obtain medical records. The stronger your evidence, the stronger your claim.
Prove Negligence
Show that the property owner created the hazard or knew about it and did nothing to fix, remove, or warn about it. Negligence is the foundation of your case.
Negotiate or Litigate
Most cases settle through negotiation with the property owner's insurance company. If settlement talks stall, your case may proceed to court.
Receive Your Recovery
Once settlement is reached or a judgment is awarded, you receive compensation for your medical bills, lost income, pain, and other damages.
Act Quickly
In Florida, you have a limited window to file a slip and fall claim. Delays can hurt your case and may bar your claim entirely. The sooner you report the incident and preserve evidence, the stronger your position.
Common Questions About Slip and Fall Settlements
Do I have to go to court?
No. Most slip and fall cases settle through negotiation with the insurance company. You only go to court if settlement talks fail.
What if I was partly at fault?
Florida law allows you to recover even if you were partially responsible, as long as you were not more than 50% at fault. Your recovery is reduced by your percentage of fault.
How much is my case worth?
Settlement amounts vary widely based on the severity of your injury, medical costs, lost wages, and the strength of your evidence. An attorney can review your case and provide an estimate.
Do I pay fees upfront?
No. We work on contingency—no fees unless there is a recovery. You pay nothing out of pocket while we handle your claim.