

Car Accident Damages
How Much Can Someone Sue for a Car Accident?
Understanding economic and non-economic damages, and what your claim may be worth.
By CHG Lawyers · Published September 30, 2026
Car Accident Damages in Florida: What You Can Recover
When you’re injured in a car accident in Florida, there’s no simple answer to “How much is my claim worth?” What you recover depends on your injury’s severity, who was at fault, insurance coverage, and how strong your evidence is.
You may recover economic damages—measurable costs like medical bills and lost wages—and non-economic damages like pain and suffering. Settlement amounts vary widely: from a few thousand dollars for minor injuries to hundreds of thousands or more for permanent, life-altering harm.
This guide explains what Florida law allows you to recover, why each claim is different, and what you need to document to strengthen your case.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Economic vs. Non-Economic Damages
Economic damages are out-of-pocket costs directly caused by the accident. They have receipts and documentation:
- Medical expenses: emergency room care, hospital stays, surgery, physical therapy, medications, and medical equipment (wheelchairs, braces, mobility aids, home modifications).
- Lost income: wages you missed while recovering, and lost earning capacity if the injury causes permanent disability that reduces your future earning ability.
- Property damage: repair or replacement of your vehicle and damage to personal belongings.
- Transportation and care costs: rideshare expenses during recovery, or costs for in-home care or assistance.
Non-economic damages compensate for harm without a price tag but with serious life impact:
- Pain and suffering: physical pain from the injury and ongoing treatment.
- Emotional distress: anxiety, depression, post-traumatic stress, or fear triggered by the accident.
- Loss of enjoyment of life: reduced ability to participate in hobbies, sports, social activities, or intimate relationships. A runner who can no longer run or a parent who cannot play with their children has a claim for this loss.
- Mental anguish: the psychological toll of permanent injury, disfigurement, or disability.
- Loss of consortium: if you are married, your spouse may recover damages for loss of companionship and intimacy.
Wrongful death damages (if the crash is fatal): surviving family members may recover funeral and burial expenses, financial support the deceased would have provided, and loss of companionship.
Why Settlement Amounts Vary Dramatically
Online claims about “average” car accident settlements in Florida are misleading. The truth is simple: settlement amounts depend entirely on your specific case facts, and variation is enormous.
Scenario 1: Minor soft-tissue injury. You are rear-ended at low speed. You have neck and back pain, visit urgent care twice, receive a few physical therapy sessions, and recover in six weeks. Medical bills: $2,400. Missed work: three days. Settlement range: $3,000–$8,000.
Scenario 2: Moderate injury with ongoing treatment. You suffer a fractured tibia, require surgery, spend two weeks in a cast, and undergo three months of physical therapy. Medical bills: $35,000. Lost wages: $12,000 (eight weeks). You have lingering pain and reduced mobility. Settlement range: $40,000–$90,000.
Scenario 3: Catastrophic, permanent injury. You suffer a spinal cord injury resulting in paraplegia. You require emergency surgery, spend three weeks hospitalized, and face lifetime medical care including therapy, equipment replacement, home modifications, and attendant care. First-year medical bills exceed $500,000. You cannot return to your previous job. Lifetime medical needs: $2–$3 million. Settlement range: $500,000 to $2 million or more.
Your claim’s worth depends on your specific injury, documented costs, lost income, age, occupation, and evidence strength.
What Drives Your Car Accident Damages Claim’s Value
Injury Severity and Permanence
The nature and permanence of your injury is the single largest factor.
- Minor injuries (soft-tissue damage, minor cuts, minor fractures that heal completely): lower settlement value because recovery is quick and long-term impact is minimal.
- Moderate injuries (significant fractures, substantial soft-tissue injury, injuries requiring surgery or extended treatment): moderate settlement value, especially if you have permanent limitations or chronic pain.
- Serious or catastrophic injuries (spinal cord injury, traumatic brain injury, amputation, severe burns, permanent paraplegia or quadriplegia): dramatically higher settlement value because of lifetime medical needs, permanent disability, and lost earning capacity.
A spinal cord injury creates lifetime needs for medical care, mobility equipment, home modifications, attendant care, and vocational rehabilitation—costs that can total millions of dollars over a lifetime.
Documented Medical Costs
Your medical bills form the foundation of your economic damages claim. Insurance companies will scrutinize every charge, so documentation is critical.
Gather and preserve: – Emergency room and hospital records and invoices. – Surgical reports and anesthesia records. – Physical therapy and rehabilitation records. – Prescription receipts. – Medical equipment invoices (wheelchairs, braces, orthotics). – Home modification estimates or invoices (ramps, accessible bathrooms, widened doorways). – Future medical care projections from your treating physicians.
Future medical costs are also recoverable. If your physician projects ongoing physical therapy, pain management, or equipment replacement for years, these projected costs increase your claim’s value. An attorney can work with medical professionals to develop credible future care projections.
Lost Income and Lost Earning Capacity
If the injury caused you to miss work or reduced your future earning ability, these losses are recoverable.
- Lost wages: income you actually lost while recovering. Document this with pay stubs, tax returns, and a letter from your employer confirming missed work dates and your hourly rate or salary.
- Lost earning capacity: if the injury causes permanent disability that reduces your future earning potential. A 35-year-old who earned $60,000 annually before the injury but can now only earn $30,000 annually has a claim for the difference over remaining working years—potentially $900,000 or more.
Younger people and high-income earners typically recover more for lost earning capacity because they have more working years ahead and higher earning potential.
Liability Clarity
If the other driver was obviously at fault—ran a red light, texted while driving, or was speeding—your claim is stronger and settlement negotiations are more straightforward. If liability is disputed or shared, your recovery may be reduced.
Florida follows comparative negligence: you can recover even if you are partially at fault, as long as you are less than 50% responsible. Your recovery is reduced by your percentage of fault. If you are found 25% at fault and your damages are $100,000, you recover $75,000.
Insurance companies often try to assign you more blame than you deserve. Strong evidence—accident reports, witness statements, photographs, traffic camera footage—protects your recovery.
Insurance Policy Limits
Florida requires minimum liability insurance of $10,000 per person and $20,000 per accident for bodily injury. Many drivers carry only this minimum; others carry higher limits ($50,000, $100,000, $250,000, or more).
Your recovery from the at-fault driver’s insurance is capped by their policy limit. If your damages are $150,000 but their policy limit is $25,000, the insurance company pays only $25,000. You would then pursue other sources—your own uninsured or underinsured motorist (UM/UIM) coverage, the at-fault driver’s personal assets, or their employer’s coverage.
Evidence Quality
The strength of your evidence directly affects settlement value. Insurance companies will challenge weak claims and offer less for cases with poor documentation.
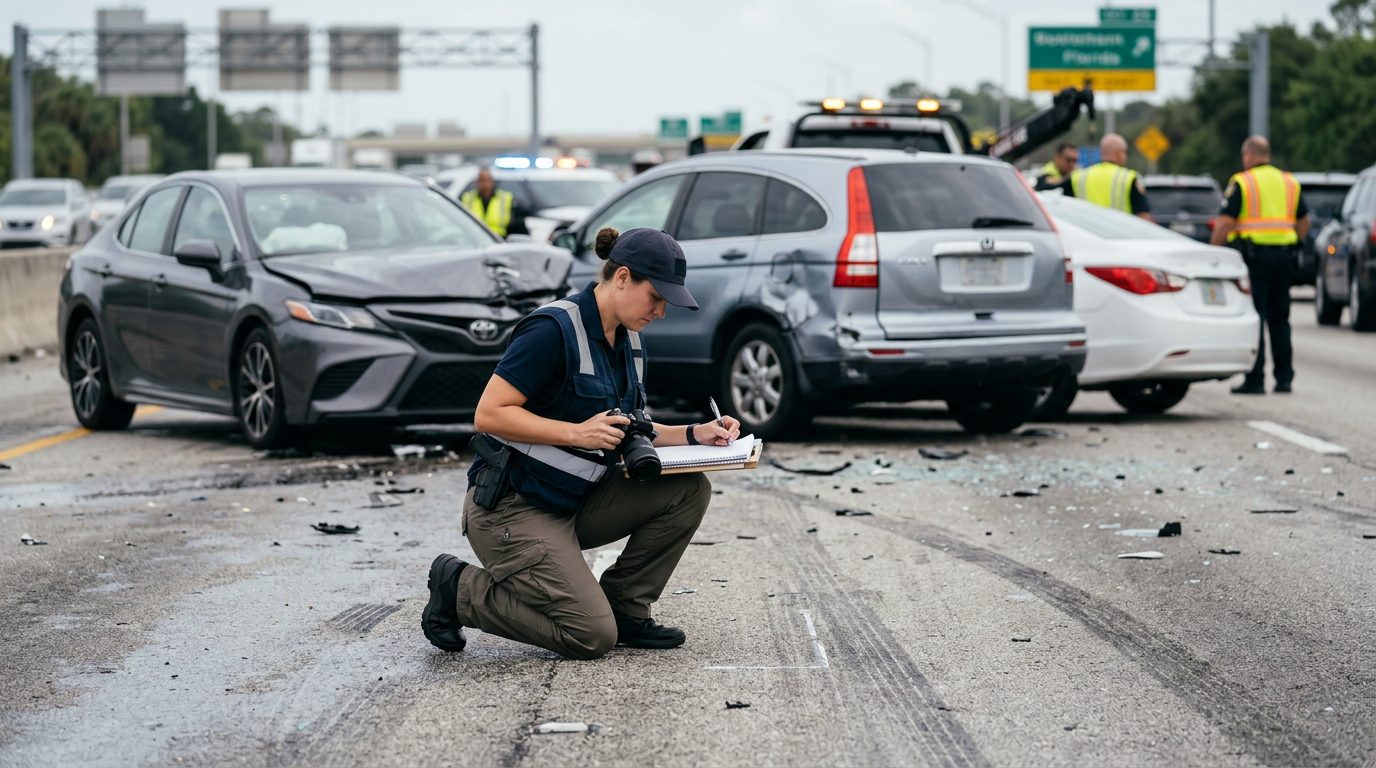
Strengthen your claim by preserving: – Medical records: complete treatment records, imaging (X-rays, MRIs, CT scans), surgical reports, and physician notes documenting your injury, symptoms, and functional limitations. – Accident reports: the police or highway patrol report, which often includes the officer’s assessment of fault. – Photographs and video: photos of vehicle damage, accident scene, your injuries, and any visible impact on your daily life (mobility aids, home modifications). – Witness statements: contact information and statements from people who saw the accident. – Expert testimony: medical testimony about your injury, prognosis, and future care needs; accident reconstruction testimony about how the crash occurred; vocational rehabilitation testimony about lost earning capacity.
Age and Occupation
Younger people typically recover more for lost earning capacity because they have more working years ahead. A 25-year-old with 40 years of work ahead recovers more for permanent disability than a 60-year-old nearing retirement.
High-income earners recover more for lost wages and lost earning capacity than lower-income workers.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Understanding Pain and Suffering in Florida Car Accident Claims
Pain and suffering is a non-economic damage—compensation for physical pain, emotional distress, and reduced quality of life. Florida law allows recovery for pain and suffering in car accident claims, but there is no fixed formula.
Pain and suffering is valued based on:
- Injury severity: a spinal cord injury causing permanent paralysis generates higher pain and suffering damages than a minor fracture.
- Duration: an injury causing pain for six weeks generates less compensation than one causing chronic pain for years.
- Impact on daily life: an injury preventing you from working, exercising, caring for yourself, or participating in hobbies generates higher pain and suffering damages than one with minimal functional impact.
- Permanent scarring or disfigurement: visible, permanent scarring or disfigurement increases pain and suffering damages.
- Medical evidence: treatment notes documenting pain, physician testimony about pain severity, and your own testimony about how pain affects your daily life all support pain and suffering claims.
Example: A 40-year-old construction worker suffers a severe burn injury to his hands and forearms. He undergoes multiple surgeries, skin grafting, and months of physical therapy. He has permanent scarring and reduced grip strength, preventing him from returning to construction work. He experiences chronic pain and psychological distress from the disfigurement. His pain and suffering damages might be $150,000–$300,000 or more, depending on the specifics of his injury and its impact on his life.
Key Deadlines: The Statute of Limitations
For most Florida negligence and personal-injury claims, the deadline to file a lawsuit is two years from the date of the accident. Property damage claims also have a two-year deadline.
Insurance claims should be reported promptly; most insurers require notice within a reasonable time (often 30 days). Waiting too long can result in lost evidence, faded witness memories, and difficulty proving your claim.
Act quickly. Preserve evidence, document your injuries and treatment, and consult an attorney early. The sooner you begin, the stronger your case.
Recovering Beyond the At-Fault Driver’s Policy Limit
If your damages exceed the at-fault driver’s policy limit, you may pursue additional recovery sources:
- Your own uninsured or underinsured motorist (UM/UIM) coverage may cover the shortfall between your damages and the at-fault driver’s policy limit.
- The at-fault driver’s personal assets: If the driver has significant personal wealth, you may pursue a judgment against them personally. This is often difficult but possible in high-damage cases.
- The at-fault driver’s employer: If the driver was working at the time (delivery driver, rideshare driver, commercial driver), their employer may have commercial insurance providing additional coverage under vicarious liability.
- Catastrophic injury claims frequently exceed standard policy limits. Spinal cord injuries, traumatic brain injuries, amputations, and severe burns often result in lifetime medical needs and lost earning capacity far exceeding $10,000 or $20,000 in coverage.
An attorney can investigate all available recovery sources and pursue the maximum compensation available to you.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
Frequently Asked Questions
What is the difference between economic and non-economic damages?
Economic damages are measurable, out-of-pocket costs with documentation: medical bills, lost wages, vehicle repair. Non-economic damages compensate for pain, suffering, emotional distress, and reduced quality of life and don’t have a fixed dollar amount.
Can I recover if I was partially at fault?
Yes, as long as you are less than 50% at fault under Florida’s comparative negligence rule. Your recovery is reduced by your percentage of fault.
How is pain and suffering calculated?
There is no fixed formula. Pain and suffering is based on the injury’s severity, duration, and impact on your daily life, supported by medical records, physician testimony, and your own testimony.
What if the at-fault driver has no insurance?
Your own uninsured motorist (UM) coverage may cover your damages up to your policy limit. If you don’t have UM coverage, recovery is more difficult but not impossible; an attorney can explore other options.
How long do I have to file a lawsuit?
You have two years from the date of the accident to file a personal injury lawsuit in Florida.
Should I accept the insurance company’s first settlement offer?
No. Understand the full value of your claim before settling. Insurance companies often offer less than your claim is worth. An attorney can help you evaluate settlement offers and negotiate for fair compensation.
If you’ve been injured in a car accident in Florida—whether the injury seems minor now or you’re facing serious, ongoing medical treatment—the next step is understanding what your specific claim might be worth. Contact CHG Personal Injury Lawyers for a free case evaluation to discuss your accident, your injuries, and what damages you may be able to recover.
Types of Damages You May Recover
Economic Damages
Measurable, out-of-pocket costs with documentation: medical bills and ongoing treatment, lost wages and lost earning capacity, vehicle repair or replacement, property damage, and transportation costs.
Non-Economic Damages
Compensation for pain and suffering, emotional distress, reduced quality of life, scarring or disfigurement, loss of enjoyment of activities, and permanent disability or impairment.
Factors That Affect Claim Value
The severity of your injuries, clarity of liability (who was at fault), insurance policy limits, your degree of fault (if any), medical evidence and documentation, and the long-term impact on your life and work.
Special Circumstances
Catastrophic injuries—spinal cord damage, paralysis, traumatic brain injury, amputation, or severe burns—often result in substantially higher claim values due to lifetime care needs and permanent impairment.
Important: Liability Matters
The amount you can recover depends heavily on proving that the other driver was at fault. Even if you were partially responsible for the accident, you may still have a claim. The specifics of your situation—the police report, witness statements, vehicle damage, and medical records—all play a role in determining what your case may be worth.
Why Documentation Matters
Medical Records
Detailed medical documentation of your injuries, treatment, and prognosis is essential to establish the full scope of your damages.
Proof of Lost Income
Pay stubs, tax returns, and statements from your employer help quantify wages lost due to your injury and recovery.
Police Report & Evidence
The accident report, photos, witness statements, and vehicle damage assessments establish liability and the severity of the collision.
Impact on Daily Life
Documentation of how the injury has affected your ability to work, care for yourself, or enjoy activities strengthens your claim for non-economic damages.