

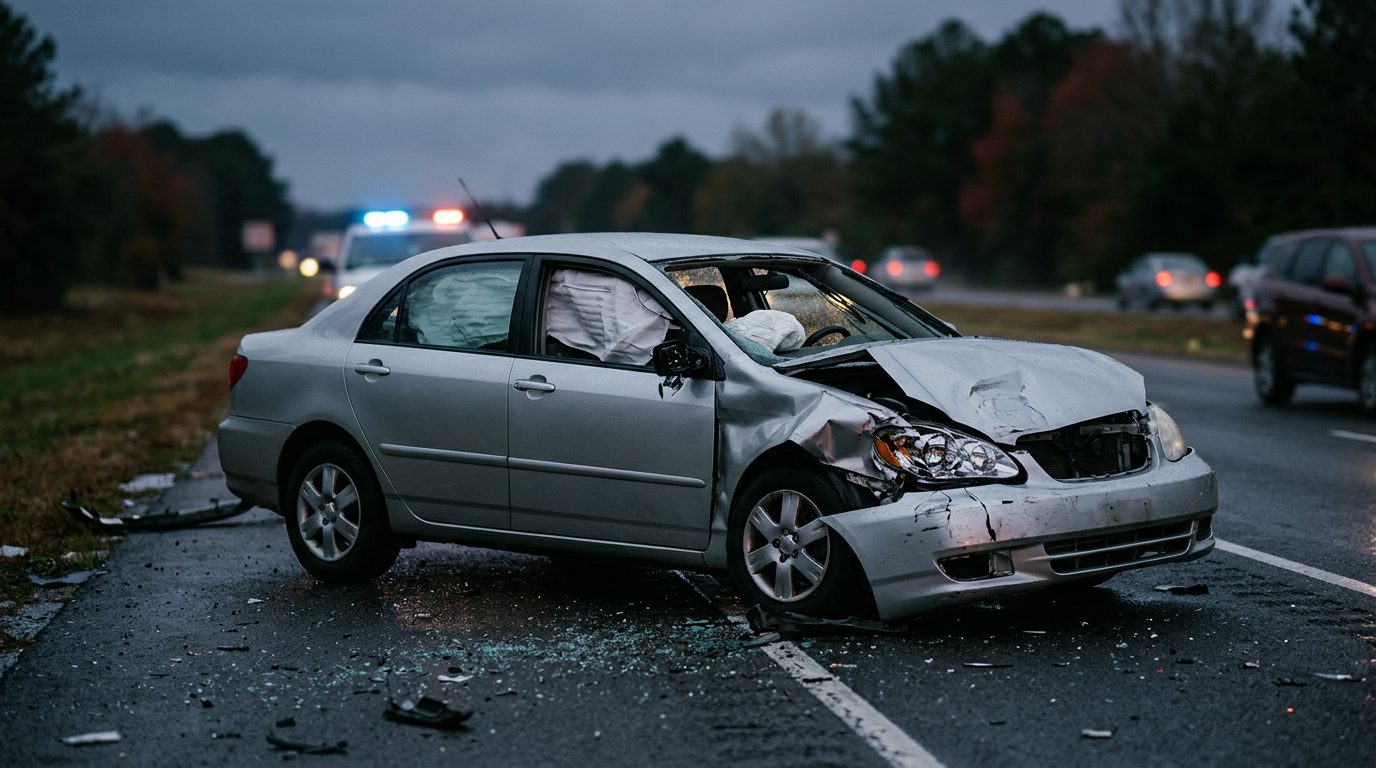
Car Accident Injuries
How Much Is a Broken Leg Worth in a Car Accident?
Understanding the value of your claim and what factors determine compensation for a broken leg injury.
By CHG Lawyers · Published October 05, 2026
Broken Leg from a Car Accident: What Your Claim Is Actually Worth
You’re in pain. You can’t work. Your medical bills are mounting. The question running through your head isn’t abstract—it’s urgent: What is my broken leg actually worth?
The answer depends on two categories of loss: the bills and income you’ve lost (economic damages) and the pain, lost mobility, and disruption to your life (non-economic damages). There’s no fixed price for a broken leg. A simple fracture that heals cleanly in eight weeks is worth far less than a compound fracture that requires surgery, months of physical therapy, and leaves you with chronic pain or permanent mobility loss.
What matters most right now: Florida sets a strict deadline for filing a personal injury lawsuit, and it may be closer than you think. Because these time limits vary by case, confirm your deadline with an attorney as soon as possible. Acting early—documenting your injury, preserving evidence, and understanding your rights—protects your claim and your recovery.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How Fracture Type and Location Drive Settlement Value
Not all broken legs are equal. The bone that broke, how it broke, and what it took to fix it determine a large part of what your claim is worth.
Simple fractures break cleanly in one place. The bone stays aligned, and a cast or brace often does the job. Recovery is faster, medical costs are lower, and you return to work sooner. These cases settle for less.
Compound fractures break the bone and may pierce the skin, while comminuted fractures shatter the bone into three or more pieces. They require surgery, metal plates, pins, or screws. The hospital stay is longer. Infection risk is higher. Recovery takes months, not weeks. These cases are worth significantly more.
Location matters enormously. A break in the tibia (shin bone) or fibula may heal in 6 to 8 weeks with a cast. A femur (thighbone) fracture is a different story—it bears your body weight, requires surgery in most cases, and takes 4 to 6 months or longer to heal. A femur break that sidelines you from work for half a year creates far larger lost-wage damages than a tibia break.
Surgery and hardware push settlement value up. Every plate, screw, or pin means higher medical bills, longer anesthesia time, infection risk, and extended recovery. It also means future complications are more likely—hardware sometimes needs removal, bones don’t always heal perfectly, and chronic pain is common.
Economic Damages: The Measurable Costs of Your Injury
Economic damages are straightforward: they’re the money you’ve actually spent or lost because of the broken leg. Insurance companies can verify these with receipts, medical records, and pay stubs.
Emergency and surgical care includes the ambulance, emergency room, operating room time, anesthesia, imaging (X-rays, CT scans), and hospital stay. A compound fracture requiring surgery can be very costly, depending on fracture complexity, whether complications arose, and how long you stayed hospitalized.
Ongoing treatment is where costs compound. Physical therapy to regain strength and range of motion often runs 2 to 3 months, sometimes longer. Each session costs money. You may need a walker, crutches, or wheelchair during recovery. Some fractures require follow-up surgeries if the bone doesn’t heal properly or hardware causes problems.
Lost wages are real money out of your pocket. If you earn $2,000 per week and can’t work for three months, that’s $24,000 in lost income—money you needed to pay rent, utilities, and other bills. Physical jobs (construction, nursing, retail) mean higher lost-wage claims because you can’t work while healing. Desk jobs may mean you can work from home sooner, but if you can’t, the lost income is just as real.
Future medical care matters if your break causes lasting complications. Chronic pain, arthritis, nerve damage, or infection may require ongoing medication, physical therapy, or specialist visits for years. These future costs can add substantially to your settlement, depending on your prognosis.
Mobility aids and home modifications count as compensable expenses. Crutches, a walker, a wheelchair, grab bars in the bathroom, ramps, or modifications to your bedroom or bathroom to help you move during recovery—all of these are costs the at-fault driver’s insurance should cover.
Non-Economic Damages: Compensation for Pain, Suffering, and Lost Life
Non-economic damages don’t have a receipt, but they are real and compensable. They reflect what the injury has actually taken from you.
Pain and suffering includes the physical pain during recovery and any chronic pain that lingers after the bone heals. A broken femur that heals but leaves you with constant aching is different from a break that heals completely. Doctors’ notes about your pain level, treatment for pain management, and your own journal entries documenting daily pain all support this part of your claim.
Loss of mobility and independence is the frustration of not being able to walk, drive, or do everyday tasks. If you normally walk your dog, play sports, or care for your children, a broken leg that sidelines you for months is a real loss. That loss has value.
Emotional distress from the accident itself—anxiety, depression, trauma, or fear of driving again—is compensable. Some people develop PTSD after a serious accident. That’s real harm.
Loss of enjoyment of life applies if the injury prevents you from hobbies, sports, or activities you loved. If you’re a runner and the break leaves you with permanent mobility loss, that’s a measurable impact on your quality of life.
Scarring or disfigurement from surgery or the injury itself can affect your appearance and self-image. If the break required surgery that left visible scars, that’s part of your claim.
Insurance adjusters often use a multiplier to estimate non-economic damages. They take your economic damages and multiply them by a number—typically 1.5 to 5 or higher—depending on injury severity. A simple fracture with full recovery might get a 1.5 multiplier. A compound fracture with permanent effects might get a 3 to 5 multiplier or higher. The multiplier reflects how serious the injury is and how much it has changed your life.
What Settlement Ranges Look Like in Real Cases
Uncomplicated fractures that heal cleanly without surgery, with straightforward recovery and minimal lost work time, tend to settle for lower amounts. These are breaks that required casting and physical therapy but nothing more.
Moderate fractures requiring surgery, extended recovery (3 to 6 months), and significant lost wages tend to settle for more. These include compound fractures, multiple breaks, or breaks that required pins, plates, or screws.
Severe fractures with permanent complications—chronic pain, arthritis, permanent mobility loss, or inability to return to your previous job—can settle for considerably higher amounts. These cases require strong medical evidence of lasting harm and clear documentation of how the injury has changed your life and earning capacity.
These are general patterns, not promises. Your actual settlement depends on the specific facts of your accident, the quality of your medical evidence, how clear liability is, and the insurance company’s assessment of trial risk.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
Factors That Shift Settlement Value Up or Down
Liability and fault matter enormously. If the other driver ran a red light and hit you, liability is clear—your settlement is stronger. If both drivers share fault, Florida’s comparative fault rule applies: you can still recover, but your award is reduced by your percentage of fault (Fla. Stat. § 768.81(2)). If you’re found 30% at fault, you recover 70% of what your claim is worth. If you’re found more than 50% at fault, you recover nothing.
Insurance policy limits are a hard ceiling on recovery. If your broken leg claim is worth more than the at-fault driver’s available coverage, you may be capped at that policy limit—unless you have your own uninsured or underinsured motorist (UM/UIM) coverage.
Your own UM/UIM coverage can bridge the gap. If you have more UM/UIM coverage than the at-fault driver’s policy limits, you can tap your own coverage for the difference. This coverage is critical if the other driver is underinsured.
Medical documentation quality directly affects settlement value. Clear records of treatment, imaging results, doctor’s notes, surgical reports, and prognosis statements strengthen your claim. Insurance adjusters rely heavily on medical evidence. Vague or incomplete records weaken your position.
Your age and overall health influence recovery timeline and long-term prognosis. A 25-year-old with a broken femur may recover fully but lose six months of wages. A 65-year-old with the same break may face complications, chronic pain, or permanent mobility loss that affects the rest of their life. Both factors increase claim value, but for different reasons.
Your job and lost earning capacity matter significantly. If you’re a construction worker who can’t return to physical work for six months, your lost wages are substantial. If you’re a desk worker who can work from home after two weeks, lost wages are lower—but if the injury is permanent and you can never do physical work again, your lost earning capacity over your remaining career could be enormous.
Long-term prognosis is crucial. If doctors expect full recovery with no lasting effects, the settlement is typically lower. If the break causes permanent disability, chronic pain, reduced mobility, or prevents you from returning to your previous job, the settlement is higher.
What You Can Recover in a Broken Leg Claim
Economic damages (medical bills, lost wages, future care costs, mobility aids) may be part of your claim, but non-economic damages (pain, suffering, lost quality of life) are available only if your injury meets the threshold Florida law sets for motor vehicle cases. In most Florida car accident cases against private drivers, there is no cap on non-economic damages, but claims against the state, its agencies, or its subdivisions are limited to $200,000 per person and $300,000 per incident.
Punitive damages—meant to punish reckless or intentional conduct—are rare in ordinary car accidents. They may be available if the other driver was driving under the influence, fleeing police, or acting with gross negligence or intent to harm.
Your actual recovery is limited by available insurance coverage and the at-fault driver’s personal assets. Most people cannot pay a large judgment out of pocket, so the insurance policy limit is often the practical ceiling.
The Two-Year Deadline: Why It Matters Now
Florida sets a strict deadline for filing a personal injury lawsuit, and the exact time limit depends on your case. Missing that deadline can bar your claim. Florida law does pause the time limit in some situations, such as when the person to be sued is absent from the state, but you should not count on an exception.
Why does this matter right now? Because acting early protects your claim:
- Evidence preservation: Photos of the accident scene, vehicle damage, and road conditions fade or disappear. Witness memories fade. Early action preserves this evidence.
- Medical records: Seek treatment immediately and keep detailed records. Gaps in treatment or delayed diagnosis can hurt your claim.
- Witness statements: Contact witnesses soon after the accident while their memory is fresh.
- Insurance deadlines: Notify the at-fault driver’s insurance promptly. Delays can complicate your claim.
- Legal strategy: An attorney can identify all sources of coverage, preserve evidence, and build a strong case before the statute of limitations approaches.
Don’t wait until month 23 to contact a lawyer. By then, evidence may be lost, witnesses may be unavailable, and you’ll have less time to build a strong case.
Steps to Take After a Broken Leg from a Car Accident
Seek immediate medical attention. Some fractures worsen without proper treatment. Early diagnosis and care are critical. Go to the emergency room, get imaging, and follow your doctor’s treatment plan exactly.
Document everything. Keep all medical records, bills, receipts, and records of lost work days. Take photos of the accident scene, vehicle damage, and your injuries. Write down the names and contact information of witnesses.
Report the accident to police and obtain a copy of the accident report. This report is important evidence of what happened and who was at fault.
Notify the at-fault driver’s insurance company. Be factual but brief. Don’t accept a settlement offer without understanding the full value of your claim. Insurance adjusters often lowball initial offers.
Keep a journal of your pain, recovery progress, and how the injury affects your daily life—work, family, hobbies, sleep. This supports your non-economic damages claim and shows the real impact of the injury.
Do not post about the accident or your recovery on social media. Insurance adjusters may use it against you.
Don’t sign anything or give a recorded statement without legal advice. Insurance companies use these to limit their liability.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
When You Should Talk to a Lawyer
If your broken leg required surgery, caused significant lost wages, or is expected to have lasting effects, an attorney can help maximize your recovery. An attorney can also help if the insurance company is slow to respond, offers a low settlement, or denies your claim.
Many personal injury attorneys work on contingency, meaning you pay nothing unless your case is resolved and you receive compensation. This makes legal help accessible even if you’re facing medical bills and lost income.
An attorney can also ensure you don’t miss the two-year filing deadline and can identify all available sources of coverage—the at-fault driver’s policy, your own UM/UIM coverage, Med Pay, and any other insurance that applies.
Frequently Asked Questions
How long does it take to settle a broken leg claim?
Most broken leg claims settle within 6 to 12 months, though complex cases with permanent injuries may take longer. The timeline depends on how quickly you heal and how willing the insurance company is to negotiate.
Can I still file a claim if I was partly at fault for the accident?
Yes. Florida follows a modified comparative fault rule, which can reduce or limit the damages you recover if you are found partly at fault for the accident (Fla. Stat. § 768.81(6)). Your recovery is reduced by your percentage of fault. If you’re 20% at fault and your claim is worth $50,000, you recover $40,000.
What if the at-fault driver doesn’t have insurance?
Your own uninsured motorist (UM) coverage can cover your damages. If you don’t have UM coverage, you may need to file a claim against your own health insurance or pursue the driver’s personal assets, which is often difficult and rarely successful.
Do I need a lawyer to settle a broken leg claim?
You can handle a simple claim on your own, but an attorney is valuable if the injury is serious, recovery is prolonged, or the insurance company is difficult. An attorney can negotiate on your behalf, ensure you’re not accepting less than your claim is worth, and protect you from missing deadlines.
What is the deadline to file a lawsuit for a broken leg from a car accident?
In Florida, there is a strict deadline for filing a personal injury lawsuit, and the exact time limit depends on your case. This deadline is absolute. Don’t wait; contact an attorney early to preserve evidence and meet this deadline.
If you’ve broken your leg in a car accident, the clock is running. The sooner you act—documenting your injury, preserving evidence, and understanding your rights—the stronger your claim will be. Reach out to discuss your situation with our team. We can review your medical records, explain your options, and help you understand what your case may be worth.
Factors That Affect Your Claim's Value
Severity of the Fracture
A simple break that heals cleanly is valued differently than a compound fracture requiring surgery, multiple procedures, or ongoing treatment. Breaks that affect your ability to work or move are worth more.
Medical Costs
Emergency care, surgery, hospital stays, physical therapy, imaging, and follow-up visits all add up. Your claim includes past medical bills and the cost of future care you'll need.
Lost Wages and Income
If the injury kept you from work—whether for weeks or months—you can recover those lost earnings. If a permanent injury affects your earning capacity, that loss is also part of your claim.
Pain, Suffering, and Disability
Beyond medical bills, the law recognizes the physical pain, emotional distress, and loss of quality of life that comes with a broken leg. This is often the largest part of a settlement.
Time Matters
Florida law sets a deadline for filing a personal injury claim. The sooner you act, the sooner we can gather evidence, medical records, and witness statements while details are fresh. Don't wait.
What We Do to Build Your Case
Gather Medical Evidence
We collect all your medical records, imaging, surgical reports, and treatment plans to document the full extent of your injury and recovery.
Investigate the Accident
We obtain the police report, witness statements, traffic camera footage, and vehicle damage photos to establish who was at fault.
Negotiate with Insurance
Insurance companies often undervalue claims. We handle all communication and push back against low offers on your behalf.
Calculate Fair Compensation
We work with medical professionals and economists to determine what your injury is truly worth—including future care and lost earning potential.
Common Questions About Broken Leg Claims
How long does it take to settle a broken leg claim?
Most broken leg claims settle within 6 to 12 months, though complex cases with permanent injury may take longer. The timeline depends on how quickly you heal and how willing the insurance company is to negotiate.
Can I still file a claim if I was partly at fault for the accident?
Yes. Florida allows you to recover compensation even if you share some responsibility for the crash, as long as you were not more than 50% at fault (Fla. Stat. § 768.81(6)). Your recovery is reduced by your percentage of fault.
What if the other driver was uninsured?
You may be able to file a claim under your own uninsured motorist coverage. We can help you navigate this process and hold the at-fault driver accountable.
Do I need an attorney to settle my claim?
You can try to settle on your own, but insurance companies often offer less to people without legal representation. An attorney levels the playing field and helps ensure you receive fair compensation.