

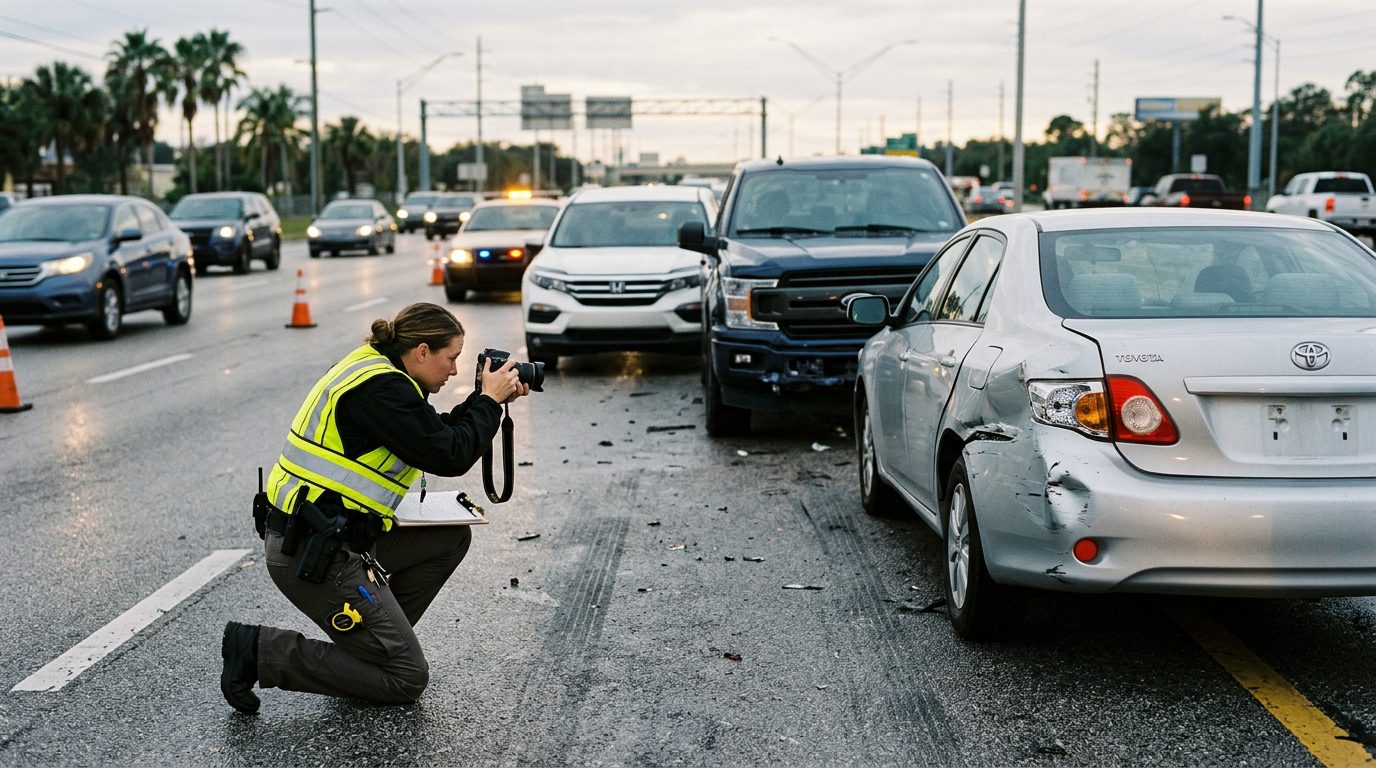
Car Accident Claims | Florida
How Long Does a Minor Car Accident Settlement Take in Florida?
Understanding the timeline from accident to resolution—and what affects how quickly you get paid.
By CHG Lawyers · Published September 13, 2026
How Long Does It Take to Settle a Minor Car Accident?
For most minor car accident claims with clear liability and straightforward injuries, settlement takes 2 to 6 weeks for simple cases, or 3 to 4 months if medical treatment extends or liability is disputed. The exact timeline depends on how quickly you gather evidence, complete medical care, and reach agreement with the insurance company. This guide walks you through each stage of a minor car accident settlement so you know what to expect.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What Counts as a Minor Car Accident?
A minor car accident typically involves a low-speed collision with minimal property damage and no serious injuries—or only minor injuries like cuts, bruises, or whiplash that resolve quickly.
For settlement purposes, what matters is that the claim is straightforward: liability is clear, injuries are not life-altering, and property damage can be repaired without major expense.
Even a minor accident involves a formal claims process. An insurance adjuster will investigate, and you’ll need to provide documentation. Understanding this process explains why settlement takes as long as it does, even when the accident itself was small.
How Long Do Most Car Accident Settlements Take?
Most minor car accident settlements are finalized within 1 to 3 months, though timelines vary based on your case facts.
- Property-damage-only claims may settle within 1 to 2 weeks.
- Claims with minor injuries typically take 2 to 6 weeks if your medical treatment is brief.
- Longer treatment extends the timeline.
“Settlement” means the insurance company agrees to pay you a specific amount and you receive the funds. This timeline assumes no lawsuit has been filed.
If the insurance company refuses to settle and you file a lawsuit, the timeline extends dramatically—often 6 months to 2 or more years depending on court schedules and case complexity.
The Settlement Timeline: Stage by Stage
Stage 1: Report the Accident and File a Claim (1–3 Days)
You contact the at-fault driver’s insurance company or your own insurer with basic accident details. An adjuster is assigned to your claim. This stage usually happens within a day or two of the accident.
Stage 2: Investigation and Evidence Gathering (1–4 Weeks)
The adjuster reviews the police report, photographs, medical records, repair estimates, and statements from both drivers. They assess fault and whether your medical treatment was reasonable.
Clear liability moves this stage quickly. Disputed fault or unclear circumstances extend investigation time.
Stage 3: Medical Treatment and Recovery (Weeks to Months)
You receive medical care for your injuries. The adjuster typically waits until your treatment is complete or you reach maximum medical improvement—the point where your condition has stabilized and further treatment won’t significantly improve your health—before valuing the claim.
This is often the longest stage for injury claims.
- Quick recovery means faster settlement.
- Ongoing physical therapy or other care extends the timeline.
Stage 4: Demand Letter and Negotiation (1–3 Weeks)
You (or your attorney, if you have one) submit a settlement demand letter stating the claim’s value. The insurance company makes an initial offer.
- Close amounts mean brief negotiation.
- Far-apart amounts mean longer back-and-forth discussion.
Stage 5: Settlement Agreement and Payment (3–7 Days After Agreement)
Once both sides agree on an amount, you sign a settlement agreement. The insurance company processes the check or arranges direct deposit. Payment typically arrives within 3 to 7 business days.
If you have an attorney, they may hold funds briefly to pay medical providers or satisfy liens before releasing your portion.
Do Insurance Companies Want to Settle Quickly?
Yes—insurance companies generally prefer to settle minor claims quickly. Keeping a claim open costs them money in administrative overhead.
However, they will not pay more than they believe the claim is worth. They will not finalize settlement until medical treatment is complete or reaches maximum medical improvement.
Straightforward minor claims with clear liability often settle faster than disputed or complex ones because less investigation is needed and less room exists for disagreement about fault.
Have questions about what happened?
Ask our team directly. The first conversation is free, confidential, and there is no obligation to continue.
What Slows Down a Minor Car Accident Settlement?
Several factors extend the timeline:
Unclear liability. If both drivers share fault or accident circumstances are disputed, the adjuster needs more time to investigate. Under Florida’s modified comparative-fault rule, a claimant found more than 50% at fault generally recovers nothing. At 50% or less, damages are reduced by their share of fault. Disputed liability means more investigation.
Ongoing medical treatment. If you’re still receiving care when you submit your settlement demand, the adjuster will wait until treatment ends or plateaus before finalizing claim value. This is the most common reason minor claims take longer than expected.
Missing documentation. An incomplete police report, missing medical records, or delayed repair estimates add weeks to the process.
Insurance company delays. Some insurers are slower than others. Some require additional forms, inspections, or internal approvals before making an offer.
Disagreement over value. If you and the insurance company disagree significantly on claim value, negotiation extends the timeline.
What Can Speed Up a Minor Car Accident Settlement?
Several steps accelerate the process:
- Clear liability. If the other driver is obviously at fault (for example, they ran a red light), the adjuster can move forward quickly without extensive investigation.
- Complete documentation. Provide the police report, medical records, repair estimates, and photographs promptly. Missing documents force delays.
- Quick medical recovery. If your injuries are minor and you recover quickly, the claim can be valued sooner.
- Reasonable settlement demand. If your demand aligns with actual injury and property damage value, negotiation is shorter and less contentious.
- Working with an attorney. A lawyer can handle insurance company communication, often accelerating the process and ensuring you’re not undervalued.
How Long After a Settlement Do You Get Paid?
Once you and the insurance company sign a settlement agreement, payment typically arrives within 3 to 7 business days. The insurance company will issue a check or arrange direct deposit.
If you have an attorney, they may hold funds briefly to pay medical providers or satisfy any liens before releasing your portion to you.
What If the Insurance Company Won’t Settle?
If negotiation stalls and the insurance company refuses a fair offer, you can file a lawsuit. However, filing a lawsuit extends the timeline significantly—often 6 months to 2 or more years depending on court schedules and case complexity.
For minor accidents, most cases settle before trial; a lawsuit is usually a last resort.
In Florida, the deadline to file a lawsuit for a personal-injury claim is generally two years from the accident date. If you’re considering a lawsuit, don’t wait until the deadline is near.
Want to know where you stand?
Tell us what happened and our team will walk you through the options available to you, at no cost.
How Long Does a Minor Accident Affect Your Car Insurance?
An accident typically stays on your Florida driving record for 3 to 5 years. Your insurance rates may increase for 3 to 5 years after an accident, even if you were not at fault, depending on your policy and insurer.
This is separate from the settlement timeline—how long your claim takes to settle does not affect how long the accident impacts your insurance rates.
Key Takeaways
- Minor car accident settlements typically take 2 to 6 weeks for straightforward claims, or up to 3 to 4 months if medical treatment or liability questions extend the process.
- The timeline depends on how quickly you gather documentation, complete medical treatment, and reach agreement with the insurance company.
- Clear liability and complete evidence speed up settlement; unclear fault and ongoing treatment slow it down.
- Payment arrives 3 to 7 days after you sign the settlement agreement.
- An accident stays on your driving record for 3 to 5 years, independent of when your claim settles.
Frequently Asked Questions
Can I speed up my settlement by refusing medical treatment?
No. Refusing or stopping treatment early often results in a lower settlement offer because the insurance company will argue your injuries were minor. Complete the medical care you need, then submit your demand.
What if I disagree with the insurance company’s settlement offer?
You can negotiate, submit a counteroffer, or decline the offer and pursue a lawsuit. An attorney can help you evaluate whether the offer is fair and what your options are.
Do I need a lawyer for a minor car accident claim?
For straightforward claims with clear liability and minor injuries, many people settle without a lawyer. However, a lawyer can often negotiate a higher settlement and handle all communication with the insurance company, potentially speeding up the process. Learn more about working with a car accident attorney.
How do I know when my medical treatment is “complete”?
Your doctor will typically tell you when you’ve reached maximum medical improvement—the point where your condition has stabilized and further treatment won’t significantly improve your health. At that point, you can submit your settlement demand.
What if my insurance claim is denied?
If your claim is denied by the insurance company, you have options including appealing the denial, filing a complaint with the Florida Department of Financial Services, or pursuing a lawsuit. An attorney can help you understand your next steps.
If you’re currently waiting for your minor car accident claim to settle and have questions about the process or your rights—or if the insurance company is delaying or offering less than you believe is fair—reach out to discuss your options and understand what you should realistically expect next. We’re here to help clarify your path forward.
The Settlement Timeline: What to Expect
Days 1–14: Immediate Steps
Report the accident to police and your insurance company. Seek medical attention, even if injuries seem minor. Collect photos, witness contact information, and the other driver's details. Document everything in writing.
Weeks 2–8: Medical Treatment & Documentation
Complete all recommended medical care. Keep records of every appointment, prescription, and bill. Your medical records are the foundation of your claim—the more complete they are, the faster the process moves.
Weeks 8–12: Demand & Negotiation
Once treatment is finished, submit a demand letter to the insurance company with all medical records, bills, and proof of lost wages. Expect their initial response within 2–4 weeks. Most minor accidents settle during this back-and-forth phase.
Weeks 12–16: Resolution
If the parties agree on a settlement amount, paperwork is signed and funds are released. Simple cases often resolve in 3–4 months total. Complex disputes may take longer.
Don't Rush to Accept the First Offer
Insurance companies often make low initial offers. You have the right to negotiate. Refusing or stopping medical treatment early to speed up settlement usually backfires—insurers will argue your injuries were minor and offer even less.
What Affects Your Settlement Timeline
Completeness of Medical Records
Gaps in treatment or missing documentation slow everything down. Finish all recommended care and gather every bill and report before submitting your demand.
Insurance Company Response Time
Some carriers respond quickly; others drag their feet. A demand letter with clear, organized evidence speeds up their review and decision-making.
Clarity About Fault
If liability is obvious (the other driver clearly caused the accident), settlement moves faster. Disputed fault claims take longer to resolve.
Willingness to Negotiate
If both sides are reasonable, settlement happens quickly. Unrealistic demands or refusals to budge extend the timeline significantly.
Complexity of Injuries
Minor injuries with straightforward treatment settle faster than cases involving ongoing pain, multiple providers, or unclear long-term effects.
Legal Representation
An attorney handling your claim can speed up the process by managing paperwork, communicating with insurers, and pushing for fair resolution.
Common Questions About Settlement Timelines
What if I disagree with the insurance company's offer?
You can negotiate, submit a counteroffer, or reject it entirely. If you can't reach agreement, you may file a lawsuit. This extends the timeline but may result in a better outcome.
Can I speed up settlement by refusing medical treatment?
No. Refusing or stopping treatment early usually results in a lower settlement offer because the insurance company will argue your injuries were minor. Complete the care you need, then submit your demand.
How much will my settlement be?
Settlement amounts depend on medical bills, lost wages, pain and suffering, and the strength of your claim. Every case is different. An attorney can evaluate what your claim is worth based on the facts.
Do I need a lawyer for a minor accident?
Many minor cases settle without legal help. However, an attorney can ensure you're not undercompensated, handle negotiations, and protect your rights if the insurer refuses a fair offer.